

Home寧波河流

Search History
Popular Searches
Dealer Login / Sign Up
车型概览

Ford Ranger 值不值得买,关键不是它看起来有多吸引,而是它能不能解决你的真实用车需求。这篇文章会把重点放在它和同级车相比的生活适配度。
价格落在 RM 116,838 - 273,838,买家可以先用它判断预算压力和同级定位。
购车价格指南
Ford Ranger 的购车预算可以先从 RM 116,838 - 273,838 开始衡量。这个数字真正影响的是月供、保险和现金流,而不只是展厅里的标价。
如果你在几个版本之间犹豫,可以把 2026 3.0T AT Raptor Sport Petrol(RM 273,838)、2025 3.0T AT Raptor Petrol(RM 263,888)、2025 3.0T AT WildTrak Diesel(RM 192,838)、2025 2.0T AT Platinum Diesel(RM 192,838) 放在同一张清单里比较。日常通勤买家优先看舒适与安全,常跑高速的买家则更应重视动力、辅助驾驶和座舱便利。
核心参数汇总
看 Ford Ranger 的核心规格,最重要是把数字翻译成生活里的感受。
涡轮增压、4缸的动力底子,适合拿来判断市区跟车和高速巡航是否轻松。 397 Ps、583 N·m的输出,真正意义在于满载、上坡和超车时不会太吃力。 车长 5381 mm、车宽 2028 mm、车高 1922 mm、轴距 3270 mm,可以帮助你预判停车难度和后排乘坐空间。 自动变速箱 变速箱、四轮驱动布局 的设定,会影响起步顺滑度、湿地稳定感和长途巡航感。
优缺点分析
Ford Ranger 的优点不必夸张,真正有价值的是它能不能让日常使用更省心:预算位置清楚,方便和同级车直接比较、动力输出能支撑高速和超车需求、空间和车身尺寸便于家庭买家预判实用性。
需要留意的是,市区停车和狭窄路段仍要看个人驾驶习惯。这些不是扣分项,而是下订前应该先想清楚的生活细节。
购车常见问题解答
购买 Ford Ranger 前,买家最常问的不是单一规格,而是它能不能融入自己的生活。
这辆车适合谁?适合把它和同级车相比的生活适配度放在首位的买家。 家庭用户要看什么?优先看后排乘坐、儿童座椅、行李和日常上下车是否顺手。 每天开会不会麻烦?如果能源成本、停车便利和版本配置都符合你的生活节奏,它会比较容易相处。
竞品对比内容
把 Ford Ranger 放进同级车名单时,不建议只看品牌或外形。真正有用的比较顺序是:先用 RM 116,838 - 273,838 锁定预算圈、再看动力是否足够应付高速和满载、最后看空间是否适合家人和行李。
这样筛选出来的结果更贴近日常生活。你会更清楚它是适合城市通勤、家庭代步、长途巡航,还是更适合作为一辆讲求个性的选择。
用车全周期指南

拥有 Ford Ranger 的重点,是确认保险、路税、保养和轮胎成本都在可接受范围内。买车不是一次付款结束,而是每天都要相处。
如果你常跑南北大道,动力和座舱舒适度会比单纯低价更重要;如果主要在市区,停车灵活性、视野和低速顺滑度会更影响心情。

车型概览

Bentley Supersports 值不值得买,关键不是它看起来有多吸引,而是它能不能解决你的真实用车需求。这篇文章会把重点放在日常场景里的便利程度。
版本方面,Bentley Supersports 目前可围绕 2025 4.0T Standard 来比较。
购车价格指南
评估 Bentley Supersports 的购车预算时,建议先从版本定位和后续拥车成本下手。价格不是唯一重点,真正决定是否划算的是每天会不会用到那些配置。
如果你在几个版本之间犹豫,可以把 2025 4.0T Standard 放在同一张清单里比较。日常通勤买家优先看舒适与安全,常跑高速的买家则更应重视动力、辅助驾驶和座舱便利。
核心参数汇总
看 Bentley Supersports 的核心规格,最重要是把数字翻译成生活里的感受。
Bentley Supersports 的核心价值应回到日常场景判断:你要它负责通勤、家庭出行、长途,还是作为更有个性的选择。
优缺点分析
Bentley Supersports 的优点不必夸张,真正有价值的是它能不能让日常使用更省心:车型定位清楚,适合先作为同级比较对象。
需要留意的是,最终取舍会落在版本配置、保险和长期保养成本。这些不是扣分项,而是下订前应该先想清楚的生活细节。
购车常见问题解答
购买 Bentley Supersports 前,买家最常问的不是单一规格,而是它能不能融入自己的生活。
这辆车适合谁?适合把日常场景里的便利程度放在首位的买家。 家庭用户要看什么?优先看后排乘坐、儿童座椅、行李和日常上下车是否顺手。 每天开会不会麻烦?如果能源成本、停车便利和版本配置都符合你的生活节奏,它会比较容易相处。
竞品对比内容
把 Bentley Supersports 放进同级车名单时,不建议只看品牌或外形。真正有用的比较顺序是:先从版本定位、品牌售后和日常用途开始比较。
这样筛选出来的结果更贴近日常生活。你会更清楚它是适合城市通勤、家庭代步、长途巡航,还是更适合作为一辆讲求个性的选择。
用车全周期指南
拥有 Bentley Supersports 的重点,是确认保险、路税、保养和轮胎成本都在可接受范围内。买车不是一次付款结束,而是每天都要相处。
如果你常跑南北大道,动力和座舱舒适度会比单纯低价更重要;如果主要在市区,停车灵活性、视野和低速顺滑度会更影响心情。

车型概览

Acura Integra 值不值得买,关键不是它看起来有多吸引,而是它能不能解决你的真实用车需求。这篇文章会把重点放在它和同级车相比的生活适配度。
版本方面,Acura Integra 目前可围绕 2026 1.5T MT A-Spec Technology、2026 1.5T CVT Standard 来比较。
购车价格指南
评估 Acura Integra 的购车预算时,建议先从版本定位和后续拥车成本下手。价格不是唯一重点,真正决定是否划算的是每天会不会用到那些配置。
如果你在几个版本之间犹豫,可以把 2026 1.5T MT A-Spec Technology、2026 1.5T CVT Standard 放在同一张清单里比较。日常通勤买家优先看舒适与安全,常跑高速的买家则更应重视动力、辅助驾驶和座舱便利。
核心参数汇总
看 Acura Integra 的核心规格,最重要是把数字翻译成生活里的感受。
Acura Integra 的核心价值应回到日常场景判断:你要它负责通勤、家庭出行、长途,还是作为更有个性的选择。
优缺点分析
Acura Integra 的优点不必夸张,真正有价值的是它能不能让日常使用更省心:车型定位清楚,适合先作为同级比较对象。
需要留意的是,最终取舍会落在版本配置、保险和长期保养成本。这些不是扣分项,而是下订前应该先想清楚的生活细节。
购车常见问题解答
购买 Acura Integra 前,买家最常问的不是单一规格,而是它能不能融入自己的生活。
这辆车适合谁?适合把它和同级车相比的生活适配度放在首位的买家。 家庭用户要看什么?优先看后排乘坐、儿童座椅、行李和日常上下车是否顺手。 每天开会不会麻烦?如果能源成本、停车便利和版本配置都符合你的生活节奏,它会比较容易相处。
竞品对比内容
把 Acura Integra 放进同级车名单时,不建议只看品牌或外形。真正有用的比较顺序是:先从版本定位、品牌售后和日常用途开始比较。
这样筛选出来的结果更贴近日常生活。你会更清楚它是适合城市通勤、家庭代步、长途巡航,还是更适合作为一辆讲求个性的选择。
用车全周期指南
拥有 Acura Integra 的重点,是确认保险、路税、保养和轮胎成本都在可接受范围内。买车不是一次付款结束,而是每天都要相处。
如果你常跑南北大道,动力和座舱舒适度会比单纯低价更重要;如果主要在市区,停车灵活性、视野和低速顺滑度会更影响心情。

Recently, Bloomberg NEF released the "2026 Electric Vehicle Outlook" industry report. Under the baseline scenario, it drastically cut the prediction for the share of new EV sales in the US by 2030 from 48% to 17%. This is the second consecutive year the prediction has been lowered, with expectations reduced by nearly two-thirds over the past two years.
At the same time, the China Passenger Car Association revealed May retail data: New energy passenger vehicle penetration has reached 62.9%, with no fuel vehicles among the top 15 models.
One side is downgrading long-term forecasts, while the other is shattering penetration records. The world's two largest automotive markets have taken completely opposite paths in the same wave of electrification.
The divergence behind this lies not in technological gaps, nor policy strength, but in the underlying structure of the industrial ecosystem.

Since September 2025, following the official termination of the $7,500 federal tax credit, the US EV market bled out on the spot.
In Q1 2026, US new energy vehicle sales plummeted 28% year-on-year, the worst in five years. April was even more exaggerated; pure electric sales were only 64,500 units, down 46.7% year-on-year. According to BNEF statistics: at least 27 EV models were cut, delayed, or canceled in the past year. Stellantis, Ford, GM, and Honda combined EV business losses exceeded $64 billion.
This isn't a problem just a few companies can't handle; the entire new energy supply chain has collapsed.

Ford: In April 2026, it officially dissolved its standalone EV business unit, Model e. This division, which invested $30 billion heavily in 2021, accumulated losses of over $12.8 billion over five years, burning through $4.8 billion alone in 2025. The profits from Ford's traditional ICE business, Ford Blue, were almost entirely consumed by the EV business. The F-150 Lightning, once the "flagship of electric pickups," was stopped on the spot, along with a write-off of $19.5 billion in asset impairments. The next-gen F-150 shifts from a pure electric architecture to extended range, installing a gasoline generator to charge the battery, claiming a range of 700 miles. Ford CEO Jim Farley's exact words were "We want to meet customers where they are." Aku translates: If consumers don't buy pure EVs, we change direction. Three-row pure electric SUV projects were cut, commercial vans for Europe were cut, and the North American E-Transit was also switched to gasoline and hybrid versions. Jim also said a more intriguing remark: Now the real object of benchmarking and research is BYD.

GM: The Cadillac Ultium battery platform was internally classified as a "financial burden." The Chevrolet Silverado EV, combined with the F-150 Lightning and Rivian R1T, sold only 12,000 units in the first four months of 2026, indicating that pickup truck users simply don't care. Range anxiety and reduced towing capacity are hard injuries; no amount of subsidies can fix that.

Honda: Lost the most severely, suffering its first annual loss in nearly 70 years since listing, with a net loss of 423.9 billion yen. Impairments and restructuring costs related to electrification were as high as 1.45 trillion yen. Adding future expected additional costs, the total impact approaches 2.5 trillion yen, almost the sum of Honda's profits over the past three years.
President Teruhiro Numabe set a goal upon taking office in 2021: "Phase out all sales of fuel vehicles by 2040." Five years later, the goal is dropped. All three 0-series pure EVs were canceled, two of which were already at the "eve of production"; the premium EV brand Afeela, jointly built with Sony, also ended; the CAD 11 billion EV industrial chain project in Canada was frozen indefinitely. If inventory sells out, pure electric vehicles will disappear completely from Honda's North American product line.
After returning from a trip to China, Teruhiro Numabe also expressed his opinion in an internal meeting: "Facing such an opponent, we have no chance of winning." Later summarizing to the media: "China has entered the smartphone era, while we are still using flip phones." Retired executives jointly petitioned to force him out, compelling him to cut his salary by 30%. However, while the system changed, the elders' influence is no longer what it was, and Teruhiro kept his seat. Meanwhile, over the next three years, Honda will invest 4.4 trillion yen in hybrids and fuel vehicles, keeping only 800 billion for pure electric, completely shifting from "betting everything" to "stopping the bleeding to survive."

Tesla: Model S and Model X "retired with glory." The production line was converted into robots. Q1 losses were $2.8 billion. Margins dropped from 15% in 2021 to 3%.
Lucid: Laid off 18% in the US, the COO position was directly removed, and the second shift at the Arizona factory was closed.

From automakers to battery factories to startups, the entire production line is on a downward trajectory. Globally, more than 60 EV startups were founded from 2021 to 2023, raising over $150 billion. However, in 2024 to 2026, more than 40 declared bankruptcy or stopped production.
Where is the essence of the problem? The US lacks a complete battery supply chain. Cathode materials, separators, electrolytes, key links rely entirely on imports from China, Japan, and Korea. What can be done locally is only assembly and software. Automotive-grade chips are also fighting for production lines with AI. Storage increased 180% after three months; high-end models increased 300%. Without a supply chain, there is no cost advantage; without cost advantage, it relies on subsidies; once subsidies go, the whole system loses blood.

The data given by BNEF is even more striking: The average price of EVs in the US market is 24% higher than同级 ICE vehicles. China is the only market where the average price of EVs is lower than同级 ICE vehicles, while Germany, Italy, and the UK are 17% higher, and the US is nearly a quarter higher. Prices cannot come down, and global consumers also refuse to buy.
Charging infrastructure is a hard injury: As of June 2026, there are approximately 250,000 public charging ports in the entire US, of which DC fast charging is only 74,000. At the same time, China's public charging piles reached 4.907 million, nearly 20 times that of the US. The US has a large land area and scattered living; many users cannot install private piles. About 50% of US households do not have the conditions to install home charging piles. Calculate a bill as a consumer: Unable to charge, range reduction in winter, one-quarter more expensive than fuel cars; who wouldn't refuse to buy?

Then something interesting happened: HEV (Strong Hybrid) became the true winner in the US market. April HEV sales reached 209,000 units, up 10.1% year-on-year. For two consecutive years, it climbed from a monthly sales figure of 92,000 units all the way to over 200,000 units, more than doubling. Toyota held a 37.9% share. Honda set a monthly sales record in May with 42,583 units. CR-V hybrids accounted for 54% of that model's sales. The new RAV4 even directly canceled the pure fuel version. The logic for hybrids in the US is very simple: No change to refueling habits, no change to usage methods, no need for charging piles, but fuel consumption drops 30%-40%. In the first four months of this year, the growth curve of HEV was almost a mirror image of BEV: HEV has a steady upward trend, while BEV oscillates between 60,000 and 80,000 units.
This is no coincidence, indicating that consumers in the US market are also voting with their feet: In countries without charging conditions, hybrids are a "painless entry."

BNEF lowered the estimated EV share for the US in 2030 from 48% to 17%. Two-thirds of expectations have been wiped out. This is not a minor adjustment; it is a heavy judgment on the industry direction.
02. On the China Side: Subsidies Withdrawn, Penetration Still RisingMany people think domestic electrification was fed by subsidies, but the data given in 2026 directly refutes this judgment.
New energy vehicle purchase subsidy policies were terminated at the end of 2022. Purchase tax exemption changed to a half-exemption. The reduction cap was lowered from 30,000 to 15,000. Subsidies are decreasing, but penetration is rising. May was 62.9%, and the first two weeks of June reached 63.9%. At the end of 2023, most industry analysts predicted penetration "breaking 60%" would happen in 2027, but the result was more than a year early.
Because the engine of China's electrification is not subsidies, it is the ecosystem.

One-stop supply chain: From mine to car, the only complete industry chain globally is in China. CATL plus BYD accounts for over half of global power battery installations. LFP doubled in price? BYD's second-gen Blade Battery said, "We passed the new national standard 6 years ago." Lithium carbonate price increase was offset by salt lake lithium extraction and recycling systems; chip price increase was covered by Horizon Robotics and Black Sesame. This isn't because one link is strong; it's that every link has alternative solutions.
68% of global EVs in 2025 came from Chinese brands; in Brazil, Chinese brands accounted for 96%; in Thailand, 88%. This is not simple export; it is market suppression.

Involution drives iteration: One model update a year, one generation replacement every two years. No second market globally runs at this pace. Overseas automakers take 36 months to develop an EV, while domestic automakers take 18-24 months, compressing it by half directly. At the Chongqing Auto Show, Changan demonstrated a 120 km/h tire blowout automatic braking; Seres shouted "Safety before Intelligence." At the end of the competition, those who survive are not the cheapest, but the most capable.
Penetration rates in Tier 3 and Tier 4 cities rose from 38% at the end of 2025 to 52% in May 2026. Pure electric and plug-in hybrid vehicles below 100,000 RMB exploded, pulling a large number of first-time buyers directly into the new energy camp — also announcing that sinking markets are no longer blind spots for electrification.

Policy changed posture, direction unchanged: Two mandatory national standards landed on July 1, raising the threshold again — thermal runaway no fire for 2 hours, underbody impact test, 300 fast charging cycles, physical one-button power off mandatory standard. Previously, policy "pushed" the industry; now it "forces" compliance. Those who do poorly are cleared out; those with real ability stay. Starting August 1, all newly produced charging piles must pass CCC mandatory certification.

Charging networks have left the US by an order of magnitude: As of the end of April 2026, the total number of domestic charging facilities reached 21.955 million, public charging piles reached 4.907 million, nearly 20 times that of the US. Charging coverage in highway service areas is 98.8%. During the May Day holiday, daily new energy vehicle traffic on national highways reached 15.4 million trips, with total charging volume reaching 94.93 million kilowatt-hours. BYD plans to build 20,000 flash charging stations by the end of the year. Li Auto has built 4,057 supercharging stations. NIO swap stations exceed 3,800. V2G vehicle-grid interaction has started large-scale pilot programs in 9 cities.
China's charging network has moved from "whether there is any" to "whether it is good", while the US is still worrying about "whether there is any".

Going global has changed from selling cars to rooting: Q1 exports reached 2.226 million units, up 56.7%; new energy exports 954,000 units, also doubled; single-month exports in May reached 784,000 units, a year-on-year surge of 75.1%;
Starting in January, pure electric passenger vehicles needed export licenses from the Ministry of Commerce, down to April battery tax rebate reduction. New energy exports are also shifting from low-price volume to local manufacturing. BYD's Szeged factory in Hungary has an annual capacity of 300,000 units, production in Q4; currently looking for a second base in Spain. Executive Vice President Ke Li stated in an interview, "There is absolutely no time to start a new factory project now; all we can do is find existing factories to take over and retrofit." It's not building factories; it's seizing factories. Chery is producing jointly at Nissan's Barcelona plant and exploring contract manufacturing at Nissan Sunderland plant in the UK; Leapmotor uses Stellantis' two factories in Spain for layout; Geely plans to acquire some of Ford's capacity in Valencia; Xpeng is negotiating with Volkswagen to share European capacity;
Jefferies Investment Group estimates Chinese automakers could ultimately produce over 2 million vehicles annually in Europe. At the same time, export structure has changed: Previously low-price vehicles went for volume; now BYD Seal and Zeekr 001 sell over a thousand units per month in Europe, tearing a hole from the stereotype of "cheap but average quality" towards mainstream brands.

The core logic is one sentence: Build the ecosystem first, then scale, finally clear the field with standards. Although policies change at each stage, the direction is always moving forward.
03. Why the Divergence? Three Core DifferencesIndustrial Chain Depth: China's new energy full chain is localized. Lithium carbonate price increase has salt lake lithium extraction for offset; chip price increase is covered by Horizon Robotics and Black Sesame. What about the US? Batteries rely on imports; chips are grabbed by AI; what can be done locally is only assembly. One link gets stuck, and the whole vehicle has to wait. BNEF report also points out: Battery capacity in North America and Europe is expanding, but manufacturing costs will remain higher than China in the short term. It's not product technology that differs; it's industrial structure. Chinese automakers' development cycles are 18-24 months, US is 36 months. It's not that Americans are slow; it's that every part change requires transoceanic coordination; speed cannot be raised.

Market Logic: China is "Supply creates Demand." You launch 800V fast charging + urban NOA + 300km refueling in 5 minutes, and consumers are willing to pay. Tier 3 and 4 city penetration rises 14 percentage points a year; vehicles below 100,000 RMB explode — supply is in place, demand automatically follows. US is "Demand waits for Supply" — consumers first ask "Where are the charging piles?", "Range reduction in winter?", "How much more than fuel cars?". If they can't answer one of these three questions, they won't buy. April BEV sales 64,500 units, HEV sold 209,000 units, three to one. Supply pushes, demand doesn't respond, trapped in a vicious cycle. HEV became the "electrification painkiller" for US consumers; no change to any usage habits, but fuel consumption drops by a third. If the painkiller works, who wants to do surgery?

Policy Logic: China is "Raise the Baseline" — new national standards don't offer subsidies, but non-compliant products cannot be sold; industry-wide thresholds are raised. US is "Pay You to Do It" — subsidies follow, once subsidies are withdrawn, they immediately turn around. Honda cut losses of 2.5 trillion yen then instantly switched to hybrids; invested 4.4 trillion yen in hybrids and fuel for three years, kept only 800 billion for pure electric — not because hybrids are better, but because hybrids don't rely on that charging network and battery chain that hasn't been built. Ford's extended range F-150 uses a gasoline generator to charge the battery; essentially finding an electrification detour that "doesn't rely on the charging network" in a country without charging infrastructure.

The opposite curves of China and the US clarify one thing: Electrification cannot run just by policy pushing; it must be backed by an ecosystem.
Battery supply chain, charging network, intense iteration — if one of the three conditions is missing, it will slow down or even retreat.
The US lacks the first two; automakers collectively turned to hybrids as stepping stones. They don't not want to do pure electric; they can't. Ford's extended range F-150, Ram's Ramcharger, GM's hybrid pickup — the three major Detroit pickup manufacturers unconsciously took the same path. This isn't heroes thinking alike; they were forced into a corner by the same reality. When Honda's Teruhiro Numabe said the "flip phone" phrase after returning from China, Aku felt what he truly wanted to say was: China built the entire ecosystem from mine to charging pile to car in ten years; most countries haven't even properly set up the charging piles.
China has all three conditions, so when subsidies withdrew, the market kept rising; standards increased, the industry kept competing, exports tightened, automakers kept selling. This isn't because policy is stronger; it's because the ecosystem is thicker.

But it also means: Global electrification will not be a straight line. China's 62.9% penetration rate does not represent the world will reach this number. The BNEF industry report has already adjusted the estimated global EV share for 2040 from 73% down to 66%. How fast global markets can run depends on whether local industrial chains, infrastructure, and consumption logic can keep up.
China has carved out its own path, but others may not be able to walk this road.
【CNMO 科技消息】6 月 15 日,特斯拉宣佈:中國智造嘅 Model Y 成為 2026 年 5 月日本進口車品牌單一車型新車註冊量第一位。

據 CNMO 科技了解,今年 6 月,特斯拉公司副總裁陶琳發文稱,特斯拉喺韓國拿下進口車銷量第一,新加坡迎來第 10000 位車主、由上海超級工廠製造嘅 ModelY L 亦喺當地開始交付。喺印度班加羅爾、日本東京、泰國曼谷等,一家家特斯拉新店相繼開業。
喺中國市場,2026 年 5 月狹義乘用車零售量 151 萬輛,同比下跌 22.1%,環比增長 9.2%。其中,新能源乘用車零售量高達 95 萬輛,同比下跌 7.5%,環比增長 12.4%,市場滲透率近 63%,成功創下歷史新高位。當月燃油車零售量僅 56 萬輛,同比下跌 39%,環比微增 5%。
中型轎車細分市場方面,特斯拉 Model 3 以 1.84 萬輛嘅成績列為第一位。豐田凱美瑞同大眾邁騰均以 1.22 萬輛並列第二、三位。頭部位置仍有合資燃油車佔據,但本田雅閣、日產天籟、別克君威等經典車型銷量均未超過 0.5 萬輛,後續表現顯疲態。新能源車型方面,特斯拉 Model 3、比亞迪秦 L、海豹 06 等位居前列,純電同插混車型合計銷量已接近中型轎車市場一半。
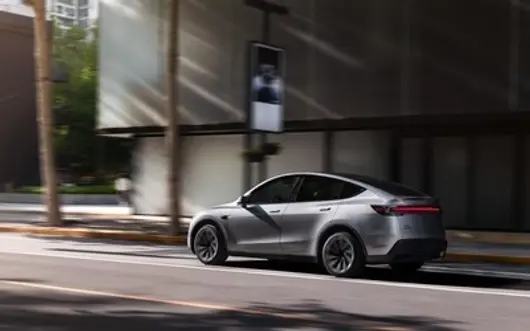
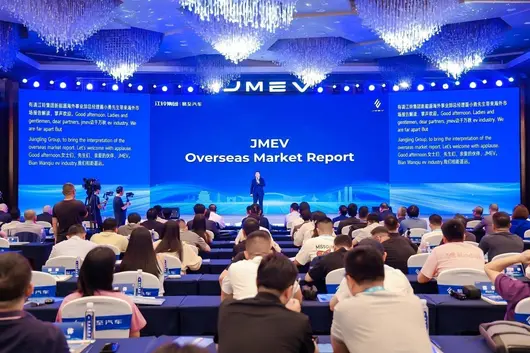
As China's new energy vehicle exports have ranked first globally for three consecutive years, JMC New Energy has achieved accelerated growth in overseas markets relying on a clear strategic path and solid execution capabilities. Currently, the company's business has expanded to over 40 countries and regions, covering five continents: Europe, Africa, the Middle East, Southeast Asia, and South America. Export business has maintained positive growth for three consecutive years. The global layout is steadily moving from the "Product Going Global" phase to a new stage of "Value Deepening".

Reconstruct Strategic System, Solidify Global Competition Foundation
The foundation of "Value Deepening" lies in systemic reconstruction on the strategy. JMC New Energy deeply recognizes that true globalization is far from simple product output, but the deep rooting of the value system. During the "15th Five-Year Plan" period, the enterprise will focus on three major tracks: "Refining Small Cars, Strengthening Mobility Cars, Optimizing Autonomous Cars", building six major strategic pillars: "Technology Leadership, Model Innovation, Low-Carbon Empowerment, Full-Chain Strict Control, Digital Intelligence Drive, Talent Accumulation", comprehensively solidifying the development foundation.
At the technical level, JMC New Energy relies on mature core three-electric technologies, combined with intelligent connectivity and lightweight body dual empowerment, inheriting JMC Group's "Safe and Reliable, Economical and Durable" quality genes, creating core advantages such as extreme low energy consumption and full-domain safety protection. Yichi 05 meets high-standard collision requirements, won EU WVTA certification certificates, and passed localization regulation certifications in countries such as Australia, Thailand, UAE, etc., crossing the world's strictest technical thresholds with reliable quality.
From Technical Certification to Ecological Co-Construction, Globalization Path Clearly Accelerated
Technical capability is the "entry ticket" to participate in global competition, but true globalization tests the upgrade of the model. To this end, JMC New Energy focuses on promoting product localization, manufacturing localization, and team localization, building a full-chain globalization system of "R&D - Production - Marketing - Service", joining hands with global partners to co-build energy ecosystems, mobility ecosystems, and intelligent ecosystems, realizing the transformation from single product trade to co-creation and win-win.

Latest data shows that JMC New Energy's overseas market has expanded to over 40 countries and regions, with business footprint covering five continents: Europe, Africa, the Middle East, Southeast Asia, and South America. Export business has achieved positive growth for three consecutive years, increasing 70% year-on-year in 2023, 25% year-on-year in 2024, and 203% year-on-year in 2025, showing an accelerated growth trend.
Behind this achievement is a clear globalization promotion path. From the first car landing in Singapore opening the door to the South Asian market, to the sequential listing in Mauritius, Sri Lanka, Nepal, and Pakistan, deeply cultivating the Indian Ocean and Southeast Asian core markets; from the first appearance at the Canton Fair to the official release of Yichi 05S, then to hundreds of Yichi 05S batches driving globally, JMC New Energy illuminates the global map with solid steps. In 2025, Yichi 06 appeared at the WNEVC World New Energy Vehicle Conference, centrally displaying the company's system solutions in the field of intelligent mobility. On May 26, 2026, the all-new Ezu EV3 was listed globally simultaneously, bringing new choices for a better mobility experience for global users.

Worth noting is that JMC New Energy is not "fighting alone" in the overseas market. The enterprise actively builds a deep cooperation network with local dealers and service providers, and has formed a relatively complete sales and after-sales service system in regions such as Southeast Asia, the Middle East, and Africa, truly realizing the leap from "Selling Cars" to "Rooting".
Looking forward, JMC New Energy will continue to steadily promote the globalization strategy with technology as the cornerstone, model as the driver, and cooperation as the bridge. The greatest path is the simplest, practical work is key. Ezu Automobiles is writing a new chapter of Chinese new energy vehicles going global with practical actions.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


