

Home湖南河流

Search History
Popular Searches
Dealer Login / Sign Up
车型概览

ARCFOX αT5 值不值得买,关键不是它看起来有多吸引,而是它能不能解决你的真实用车需求。这篇文章会把重点放在它是否容易融入日常生活。
ARCFOX αT5 的现有版本和车型定位已经足够作为购车筛选起点,重点应放在日常需求是否吻合。
购车价格指南
评估 ARCFOX αT5 的购车预算时,建议先从版本定位和后续拥车成本下手。价格不是唯一重点,真正决定是否划算的是每天会不会用到那些配置。
对注重性价比的买家来说,最稳妥的做法是先确认常用场景,再决定预算上限;这样比单纯追高配或追低价更容易买到适合自己的车。
核心参数汇总
看 ARCFOX αT5 的核心规格,最重要是把数字翻译成生活里的感受。
ARCFOX αT5 的核心价值应回到日常场景判断:你要它负责通勤、家庭出行、长途,还是作为更有个性的选择。
优缺点分析
ARCFOX αT5 的优点不必夸张,真正有价值的是它能不能让日常使用更省心:车型定位清楚,适合先作为同级比较对象。
需要留意的是,最终取舍会落在版本配置、保险和长期保养成本。这些不是扣分项,而是下订前应该先想清楚的生活细节。
购车常见问题解答
购买 ARCFOX αT5 前,买家最常问的不是单一规格,而是它能不能融入自己的生活。
这辆车适合谁?适合把它是否容易融入日常生活放在首位的买家。 家庭用户要看什么?优先看后排乘坐、儿童座椅、行李和日常上下车是否顺手。 每天开会不会麻烦?如果能源成本、停车便利和版本配置都符合你的生活节奏,它会比较容易相处。
竞品对比内容
把 ARCFOX αT5 放进同级车名单时,不建议只看品牌或外形。真正有用的比较顺序是:先从版本定位、品牌售后和日常用途开始比较。
这样筛选出来的结果更贴近日常生活。你会更清楚它是适合城市通勤、家庭代步、长途巡航,还是更适合作为一辆讲求个性的选择。
用车全周期指南
拥有 ARCFOX αT5 的重点,是确认保险、路税、保养和轮胎成本都在可接受范围内。买车不是一次付款结束,而是每天都要相处。
如果你常跑南北大道,动力和座舱舒适度会比单纯低价更重要;如果主要在市区,停车灵活性、视野和低速顺滑度会更影响心情。

车型概览

Alfa Romeo Giulietta 值不值得买,关键不是它看起来有多吸引,而是它能不能解决你的真实用车需求。这篇文章会把重点放在长期相处时会不会带来额外压力。
版本方面,Alfa Romeo Giulietta 目前可围绕 2025 Standard 来比较。
购车价格指南
评估 Alfa Romeo Giulietta 的购车预算时,建议先从版本定位和后续拥车成本下手。价格不是唯一重点,真正决定是否划算的是每天会不会用到那些配置。
如果你在几个版本之间犹豫,可以把 2025 Standard 放在同一张清单里比较。日常通勤买家优先看舒适与安全,常跑高速的买家则更应重视动力、辅助驾驶和座舱便利。
核心参数汇总
看 Alfa Romeo Giulietta 的核心规格,最重要是把数字翻译成生活里的感受。
Alfa Romeo Giulietta 的核心价值应回到日常场景判断:你要它负责通勤、家庭出行、长途,还是作为更有个性的选择。
优缺点分析
Alfa Romeo Giulietta 的优点不必夸张,真正有价值的是它能不能让日常使用更省心:车型定位清楚,适合先作为同级比较对象。
需要留意的是,最终取舍会落在版本配置、保险和长期保养成本。这些不是扣分项,而是下订前应该先想清楚的生活细节。
购车常见问题解答
购买 Alfa Romeo Giulietta 前,买家最常问的不是单一规格,而是它能不能融入自己的生活。
这辆车适合谁?适合把长期相处时会不会带来额外压力放在首位的买家。 家庭用户要看什么?优先看后排乘坐、儿童座椅、行李和日常上下车是否顺手。 每天开会不会麻烦?如果能源成本、停车便利和版本配置都符合你的生活节奏,它会比较容易相处。
竞品对比内容
把 Alfa Romeo Giulietta 放进同级车名单时,不建议只看品牌或外形。真正有用的比较顺序是:先从版本定位、品牌售后和日常用途开始比较。
这样筛选出来的结果更贴近日常生活。你会更清楚它是适合城市通勤、家庭代步、长途巡航,还是更适合作为一辆讲求个性的选择。
用车全周期指南
拥有 Alfa Romeo Giulietta 的重点,是确认保险、路税、保养和轮胎成本都在可接受范围内。买车不是一次付款结束,而是每天都要相处。
如果你常跑南北大道,动力和座舱舒适度会比单纯低价更重要;如果主要在市区,停车灵活性、视野和低速顺滑度会更影响心情。

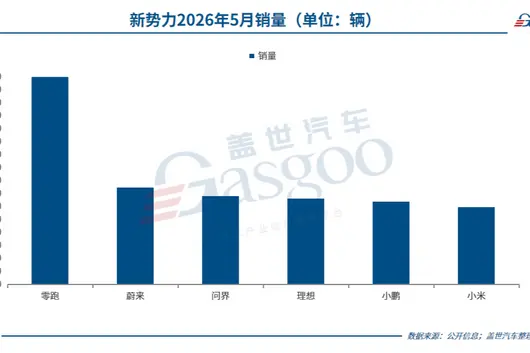
At the beginning of June, various automakers successively released their sales performance reports for May 2026. According to the forecast data released by the CPCA (China Passenger Car Association) on May 23, domestic new energy passenger car retail volume was expected to reach 950,000 units, penetration rate approximately 62.5%, setting a new historical high. This data further confirms the continued deepening of electrification transformation, as the new energy vehicle market is steadily transitioning from "policy-driven" to "market-driven".
Looking at specific sales data, the top tier pattern of new forces experienced severe differentiation in May - Leapmotor led by a "huge gap" with monthly sales exceeding 80,000 units. At the same time, traditional auto groups represented by BYD, Changan, Geely, etc., saw their self-incubated new energy brands also show a collective surge in volume in May, and the strategic value of multi-brand matrices is accelerating realization.
New Forces Matrix: Leapmotor 80,000+ "Huge Gap Lead", Multiple Brands Gathered in the 30,000 Bracket

The new forces market pattern in May showed distinct tiered characteristics: Leapmotor exceeded 80,000 units in a single month, forming a leading advantage; NIO, relying on three-brand synergy, reached sales volume of 37,700 units; Li Auto, Xpeng, Xiaomi, AITO, and other brands were concentrated in the 30,000-35,000 unit range, forming the most competitive core battlefield.

Image Source: Leapmotor
Leapmotor became the undisputed biggest highlight of May. According to Leapmotor official data, May total delivery volume reached 81,569 units, year-on-year growth 81%, month-on-month growth 14.26%, once again breaking the brand's single-month delivery historical record. Leapmotor also became the first enterprise among Chinese new automakers to exceed 80,000 units in single-month delivery.
Looking at specific models, Leapmotor A10 exceeded 20,000 units in single-month delivery, D19 new orders continued to maintain above 10,000 units, C Series global cumulative sales already exceeded 800,000 units. By the end of May, Leapmotor cumulative delivery in the first five months exceeded 300,000 units.
Leapmotor's 2026 annual sales target is 1.05 million units. Behind this ambition is Leapmotor Chairman Zhu Jiangming's proposed "2026 Sprint to 1 Million Units" strategic goal. With June C Series refresh, D99 pre-sale, and Lafa5 large-scale overseas expansion, Leapmotor is expected to launch a shock at the new milestone of 90,000 units monthly delivery.

Image Source: NIO
NIO Company also showed steady performance in May. Data shows, NIO May delivery of new cars 37,705 units, year-on-year growth 62.3%, month-on-month growth 28.4%.
NIO's growth benefits from the strategic effectiveness of three brands working together - NIO brand delivered 20,013 units, year-on-year growth 50.8%; ONVO brand delivered 12,029 units, year-on-year growth 91.5%, month-on-month increase as high as 124.8%; Firefly brand delivered 5,663 units, year-on-year growth 53.9%.
From the product level, flagship SUV NIO ES8 sold 11,475 units in May, maintaining competitiveness in the high-end market above 400,000 yuan. By the end of May, NIO company cumulative delivery this year reached 150,500 units, year-on-year growth 68.7%, cumulative delivery total has reached 1.148 million units.
Li Auto May delivery 33,350 units, by end of May historical cumulative delivery volume has reached 1.703 million units. Li Auto Chairman and CEO Li Xiang stated, since first quarter this year delivery volume has entered a growth track, among them Li Auto i6 delivered volume exceeded 20,000 units for three consecutive months, stable in top three pure electric SUV sales; May, new Li Auto L9 officially released and started delivery, L Series models entered new upgrade cycle, new L9 Livis order volume exceeded 10,000 units within two weeks of release.

Image Source: Xpeng
Xpeng Group May delivery 32,158 units, month-on-month growth 3.7%, creating a new monthly delivery high since 2026. This growth mainly stems from the continuous effort of existing product matrix - 2026 Model P7+, G6, G9 and G7 Super Range Extender versions etc. models have completed capacity ramp-up, MONA M03 maintains hot sales in 150,000 yuan level pure electric market.
On May 20, new tech flagship Xpeng GX officially launched and started delivery, providing pure electric and super range extender two power, total 8 models, 12 hours after launch firm orders reached 24,863 units, among them Ultra flagship version ratio exceeds 80%.
Xiaomi Auto May delivery volume continued to exceed 30,000 units, holding steady the "30,000+" step for the second consecutive month. Xiaomi has evolved from early SU7 "single product holding the flag" to SU7 Series and YU7 Series dual-line parallel product pattern.
By end of May, Xiaomi Auto first five months cumulative delivery volume approx 140,000 units, completed full year 550,000 units delivery target 25.5%. As a new force entered market only two plus years, Xiaomi maintaining monthly sales 30,000+ level already belongs to difficult, but second half year average monthly delivery needs to reach approx 55,000 units to achieve full year target, challenge still exists.

Image Source: HarmonyOS Intelligent Alliance
May 2026, HarmonyOS Intelligent Alliance single month delivery volume reached 46,122 units, achieving year-on-year and month-on-year dual growth. Among them, AITO Auto full series models May delivery 34,320 units, month-on-month growth 48.2%, 1-5 months cumulative year-on-year growth 28.7%.
New generation AITO M9 launched 24 hours firm orders exceeded 20,000 units, and achieved launch and delivery immediately; AITO M6 launched first month delivery exceeded 20,000 units.
From competitive landscape perspective, besides Leapmotor, remaining several new force brand delivery volumes front and back gap not big, ranking may interchange at any time, pattern highly dynamic. From this "30,000 bracket cluster", it can be seen, new forces from "break 30,000" to "stand firm 40,000" still need to cross growth threshold - this both tests product matrix richness, and puts higher requirements on supply chain management and delivery system.
Domestic New Energy: Multiple Brands Work Together, Enter Fast Lane

In the domestic new energy brand matrix that traditional auto groups are accelerating promoting, May also handed in an outstanding answer sheet. Looking at overall data released by major vehicle groups, the trend of steady improvement in new energy penetration rate is converting into tangible sales volume scale.

Image Source: BYD Auto
BYD May sales 383,000 units, ranking first in industry, among them passenger car sales 377,000 units. Dynasty Network and Ocean Network sales 330,200 units, still BYD sales cornerstone; Fangchengbao sales 30,186 units; Denza sales 16,303 units; Yangwang sales 286 units.
In terms of overseas market, BYD May export new energy vehicles total 160,600 units, year-on-year growth 80.7%, creating new historical high again.
Geely Auto May group total sales volume 238,000 units, realized same month-on-month dual growth for three consecutive months. That month new energy model sales volume 133,000 units, accounted for sales volume ratio 56.1%, exceeded 50% for four consecutive months.
Underlying Zeekr brand May delivery 34,377 units, year-on-year growth 81.8%, creating new historical high again - Zeekr 009, 9X, 8X etc. models ratio nearly 50%, driving brand single car transaction average price year-on-year increase 52.4%, holding steady in luxury brand camp.
Lynk & Co brand May sales 20,732 units, new energy sales 14,688 units, month-on-month growth 17%, new energy sales ratio as high as 71%.

Image Source: Changan Auto
Changan Auto May global delivery 209,000 units, new energy vehicle delivery 92,000 units. Changan electrification transformation shows multi-brand matrix head-to-head competition characteristic: Changan Qiyuan May delivery 34,528 units, among them new Q05 delivery 15,812 units, Thailand launch three days orders exceeded 3,000 units; Deepal Auto May global sales 33,243 units, year-on-year growth 30%, 1-5 months overseas cumulative sales 28,704 units, year-on-year growth 167%; Avatr May delivery 7,336 units, showing continuous upward trend. Sorting out data of each month this year, Avatr from January 2,216 units, February 4,033 units, March 5,143 units, April 5,279 units climbed up to May 7,336 units, visible its growth momentum.
SAIC Motor Group May vehicle sales volume 349,000 units, among them new energy vehicle sales 182,000 units, year-on-year growth 46.49%. Underlying IM Motors May delivery 10,023 units, holding steady 10,000 unit gateway for two consecutive months, 1-5 months cumulative sales year-on-year growth 115%; SAIC Passenger Car new energy 1-5 months cumulative reached 174,000 units, year-on-year surge 195%, MG4 Family 8 months sales broke 10,000.

Image Source: eπ Tech
Dongfeng system domestic new energy brands also performed outstandingly. Dongfeng eπ Tech May delivery 24,830 units, year-on-year growth 42%, 1-5 months cumulative delivery 109,600 units, overseas market year-on-year growth 194%. Voyah Auto May delivery 13,003 units, year-on-year growth 30%, 1-5 months cumulative delivery 62,041 units, year-on-year growth 35%.
Hyper Aion BU May sales 33,140 units, year-on-year growth 23.76%, among them Aion i60 monthly sales continued over 10,000. Arcfox Auto May sales 17,943 units, year-on-year growth 32.82%, overall performance steady, Alpha S5, Koala etc. models are its main force models, May started pre-sale Arcfox Beta S3 and launched Wayfind V9 future will further support its overall sales.
Conclusion:
From overall industry view, May new energy penetration rate approx 62.5%, new high again. Domestic brands have become important market force, traditional big factory late advantage showed - Geely new energy ratio exceeded 56%, Changan new energy approaching 100,000 units, SAIC new energy year-on-year increase over 46%. But there is a problem still cannot ignore, multi-brand matrix at the same time covering segmented markets, also faces resource integration and internal friction control test.
Looking forward subsequently, as multiple new models enter delivery cycle, new energy market expected to continue growth. Can Leapmotor stabilize "One Super" status? Who in 30,000 bracket cluster will break out first? These will be the highlights coming next.

講起國產汽車品牌,相信唔少人對佢哋嘅印象,可能仲係停留喺主銷普通家用车嘅階段。不過呢已經係幾年前的老皇曆,要知道而家嘅國產汽車品牌,唔單止喺國內市場壓住合資品牌打,甚至仲喺高端化、海外出口等多個賽道上,對外國汽車品牌實現反超,好似我哋而家要講嘅吉利汽車。

增長勢頭領先行業
根據官方公佈嘅最新數據,吉利汽車喺5月嘅累計銷量為237637輛,連續3個月同環比雙增長,並以穩定增速同亮眼成績實現領跑市場大盤。然而相對於呢個表現已經非常優秀嘅總成績,好多識行的人睇完吉利汽車旗下各個品牌嘅銷量成績後,就會驚嘆佢嘅含金量亦都越來越高。

眾所周知,汽車市場最难搞嘅市場有兩個,分別係豪華高端市場同海外出口市場。
我哋就拿吉利汽車嚟講,佢旗下嘅「全球豪華科技品牌」——極氪汽車,5月交付量達到34377輛,同比增長81.8%、環比增長8.1%,連續四個月實現同環比雙增長,車均成交價亦都同比增長52.4%。更為令人震驚嘅係,售價高達四十到五十萬嘅極氪9系、8系,銷量佔比竟然高達近50%!

不止於此,吉利汽車旗下嘅「全球新能源高端品牌」——領克汽車,5月銷量亦都高達20732輛,當中新能源車型銷量佔比達70.8%,並且品牌累計銷量亦已突破180萬輛。由此可見,吉利汽車嘅高端車型,唔單止憑藉出色嘅產品力獲得咗大量消費者嘅認可,仲喺品牌層面完成咗量價齊升嘅轉變。

當然啦,作為國內無可爭議嘅龍頭車廠,吉利汽車嘅目光唔再局限喺國內市場,佢選擇走出国门去挑戰難度更高嘅海外市場。唔係咩,5月就憑藉85144輛嘅海外出口成績,創下出海銷量新高紀錄。唔該提一提,吉利汽車各品牌喺海外嘅熱銷產品,亦多為高端或新能源車型。

例如,極氪已經進入50多個國家同地區,極氪7X全球累計交付量超過16萬輛;吉利銀河星艦7 EM-i ,3-4月蟬聯哈薩克斯坦新能源插混SUV銷量冠軍;吉利銀河E5,一季度蟬聯澳洲、阿根廷、阿聯酋、摩洛哥、烏拉圭純電SUV-C市場銷量冠軍,穩居巴西、烏茲別克斯坦、印尼新能源純電SUV-C車型前三!

硬核實力鑄就輝煌
好明顯,無論係迅猛嘅銷量增長態勢,定係喺新能源、高端市場同海外市場嘅熱銷,都離唔開硬實力作為支撐。我哋就拿作為中國汽車運動第一品牌嘅領克汽車嚟講,佢甚至頂尖技術唔可以只停留喺宣傳層面,而係要去賽道上拚先至證明實力,因此佢喺唔久前就宣佈攜03+TCR賽車、03++賽車、03CUP EVO三款賽車,同步參與TCR China、CTCC中國杯同領克杯三大赛事。

擁有硬實力嘅領克汽車,自然都唔怕高難度嘅檢驗,03+ TCR賽車喺TCR China兩回合正賽中,憑藉硬核嘅性能實力斬獲4冠1亞2季嘅成績;喺CTCC中國杯中,領克縱橫車隊更加斬獲2冠2亞1季嘅成績。同時,喺2026賽季FIA TCR世界巡迴賽揭幕戰中,吉利中國星車隊(Geely Cyan Racing)嘅星瑞TCR賽車,亦喺正賽強勢奪冠並帶回歷史上頭一次勝利,這唔單只意味著星瑞TCR已具備世界級競爭力,仲標誌住吉利中國星車隊正式完成咗吉利汽車運動新時代嘅第一篇章。

同時,喺智能化同安全等技術層面,傳承吉利同沃爾沃安全底蘊嘅千里浩瀚,一年輔助駕駛里程增長215%,以增速第一實現領跑全行業。喺唔久前嘅Euro NCAP官方測試中,吉利銀河星艦7 EM-i(Geely STARRAY EM-i),更加喺法國UTAC試驗室成功完成咗超標雙側連環極限碰撞測試,這既直觀印證咗吉利領先嘅整車安全技術同成熟嘅體系化安全實力,又為中國汽車安全技術走向國際、參與全球行業標準,打下咗堅實嘅根基!

大俠車談:相信好多人睇完吉利汽車嘅銷量數據後,腦海中就會浮現「佢都太全面嘅」嘅讚賞,畢竟能夠同時喺新能源、高端化、海外出口,仲有喺賽道上皆斬獲亮眼成績嘅車企,唔好話喺自主品牌呢個圈子內,就算係全球汽車行業中,都搵唔幾間車企能夠同時做到這些!
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


