

HomeGoing Overseas

Search History
Popular Searches
Dealer Login / Sign Up
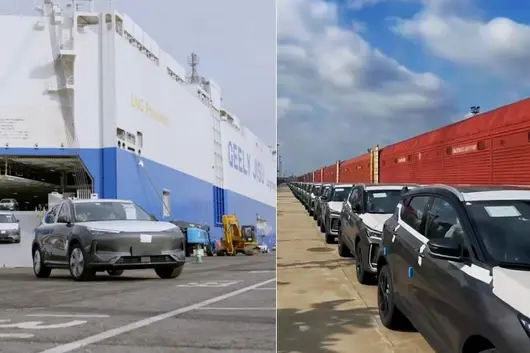
On October 19, BYD Executive Vice President Li Ke confirmed in an interview in Belgium: the company bought another 10 car transport ships. The total value of this order exceeds $1 billion, with a single ship price over $100 million, scheduled for delivery between 2029 and 2031. Once all new ships are in place, BYD's own fleet will increase from 8 to 18 ships, with total capacity exceeding 130,000 CEU.
This is not the first time BYD has bought ships. In 2022, the first batch of 8 Ro-Ro ships was initiated, with a total investment of about 5 billion yuan. They were all put into operation in September 2025, including Pioneer 1, Changzhou, Hefei, Shenzhen, etc. Among them, Shenzhen is currently the world's largest car Ro-Ro ship, capable of loading 9,200 standard vehicles.
From 8 ships to 18 ships, from guaranteeing basic capacity to supporting global expansion, the significance of this matter goes far beyond buying a few more ships.

Why is BYD in a rush to buy ships? The direct reason is that the export volume is growing too fast.
In September 2026, BYD's overseas sales reached 180,000 vehicles, a year-on-year increase of 154%, accounting for 39% of the total sales for that month. From January to September, cumulative exports totaled 1.338 million vehicles, a year-on-year increase of 92%. BYD had already raised the annual export target from 1.3 million vehicles to 1.5 million vehicles in March 2026. At this growth rate, relying on rented ships or depending on third-party shipping companies carries too much uncertainty.
Global Ro-Ro ship capacity is already tight. In June 2026, the one-year charter rate for medium-to-large car transport ships had risen to $70,000 per day, a 65% increase from $42,500 at the end of 2025. The daily rent for some 6,500-vehicle-space Ro-Ro ships even reached $80,000. Some institutions estimate that about 1 million Chinese vehicles, due to insufficient Ro-Ro ship capacity, were forced to switch to container ship transport.
High rental costs are one thing, but more crucially, delivery schedules are subject to others' control. Cars are built, but ships are not scheduled, so overseas dealers and users have to wait. For a brand rapidly expanding its overseas market, this waiting cost is higher than the rent itself. Building a self-owned fleet is essentially buying certainty: when to dispatch ships, where to dispatch them, what cars to load, the company decides itself.
Li Ke's timing of confirming this order is also noteworthy. She was interviewed in Belgium, while Europe is one of the markets with the most rapid growth for BYD overseas. The delivery cycle for the new ships is 2029 to 2031, meaning BYD is paving the way for overseas scale three to five years in advance, not an emergency measure, but planning.

Placing the matter of buying ships into the coordinate system of BYD brand development, it marks an identity shift.
In the past, for Chinese automakers going overseas, the core capability was to build a competitive car, then hand it over to shipping companies for transport and local dealers for sale. The carmaker's role was concentrated on the product end, while logistics and channels relied more on external systems. This model was efficient when export volumes were small, but when a brand's annual export scale approaches the two million vehicle level, any uncontrollable link in any link will be magnified.
BYD's choice is to hold the key links in its own hands. The fleet is one step; overseas factories are another step. The Thailand factory is already in production; the Brazil factory went into production in July 2025 with an initial annual capacity of 150,000 vehicles; the Hungary factory plans to launch Phase 1 with 150,000 vehicle capacity in Q2 2026, with annual overseas localization capacity expected to break 500,000 vehicles. Building ships and building factories, one manages flow, the other manages landing, combined they form a complete set of overseas infrastructure.
The most direct value brought by this infrastructure is supply chain resilience. In the first half of 2026, factors such as Red Sea situation, port congestion, capacity tightness, etc., repeatedly disturbed global automotive logistics; whoever has ships has the initiative. BYD's self-built fleet, during capacity shortages, is not subject to rent fluctuations and cabin allocation; after vehicles leave the production line, they can be shipped according to their own rhythm, providing more stable expectations for parts supply and complete vehicle delivery of overseas factories.
Looking deeper, controlling the logistics link also supports brand elevation. BYD is no longer selling low-price cars in Europe; models like Seal, Dolphin, Denza, etc., have entered the core areas of mainstream joint venture brands. High-end brands require higher delivery experience; if cars arrive at the port but cannot be picked up, or wait for ships for months, the damage to brand reputation far exceeds an order. A self-owned fleet makes delivery schedules predictable, which for a Chinese carmaker establishing global brand recognition, the value is hard to measure by freight rate differences.

BYD buying ships, viewed within the big picture of Chinese automotive exports, represents a switch in a stage.
Chinese car exports surpassed Japan to become number one globally in 2023, but prior overseas expansion was mostly product export, relying on cost-performance and product strength. By 2025 and 2026, the overseas sales scale of leading carmakers had become so large that relying solely on third-party logistics and local dealer systems could no longer support it; the core of competition began to extend from the product level to the system level.
SAIC, Chery, Changan, and other carmakers have already placed orders for own transport ships; BYD currently leads by a margin in scale and speed. This race is not a simple arms race; it reflects a common judgment: for Chinese automobiles to truly stand firm in the global market, they cannot just build cars well, but must also transport cars well, deliver well, and serve well.
Ro-Ro ship capacity tightness is a global structural problem, and Chinese automotive export growth rate is far higher than the expansion speed of the global Ro-Ro fleet. Under this supply-demand mismatch, whoever first establishes their own controllable deep-sea transport capability gains an extra layer of safety cushion in overseas expansion. BYD's 18-ship fleet, while not the largest in the global automotive shipping pattern, is already a scaled deep-sea capacity among Chinese carmakers.
More worth attention is the technical choice for new ships. This time, 9,200 CEU LNG powered car transport ships are ordered, adopting a dual-fuel propulsion system. LNG power is significantly superior to traditional fuel in carbon and sulfur oxide emissions. European ports have stricter requirements for ship emissions; choosing LNG power is not just a transport tool upgrade, but also preparing compliance for entering markets with higher environmental standards. Chinese automotive exports have reached today where even emission standards of transport ships begin to enter the scope of consideration; this itself is a footnote to system capability improvement.

Auto Review:
10 ships, $1 billion, delivery schedule arranged to 2031. If this account is calculated only based on freight rates, it is hard to calculate clearly. But if it is placed in the overall picture of BYD's global layout, the logic becomes clear: product export relies on cars, system export relies on ships, factories, and a global network one can control.
Chinese automotive brands' overseas stories over the past few decades mostly stayed at the level of selling cars. BYD buying ships indicates leading players are already thinking about the next step: after cars are sold, how to transport them, how to deliver them to users, how to make the whole link not subject to others. These problems have no shortcuts, only building ship by ship, a port by port.
Direction is correct, the rest is time. And BYD obviously does not plan to let others decide this time.
The Ministry of Finance issued this notice, causing quite a stir in the circle of car companies going overseas. The 4 percentage point cut in the export tax rebate rate may not look like a big number, but for car companies relying on low prices and high volume, it can truly swallow up half a year's profits.

Don't underestimate this 4%. Many independent brands focusing on Southeast Asia, the Middle East, and Latin American markets have a net profit of only 5 or 6 percent per exported car, following a strategy of thin profits and high turnover. The tax rebate rate dropping from 13% to 9% means the policy subsidy received directly decreased by one-third. Stripping away this portion, the profit per car is directly cut in half. Some entry-level volume cars that were already running on cost could potentially turn from micro-profits into losses. For them, this isn't a question of earning more or less; it's a matter of whether they can survive in this market.
Of course, it depends on who can withstand it. Companies like BYD, which control the supply chain tightly and have large export scales, can still absorb part of the cost through procurement and economies of scale, or share the price adjustment space with overseas dealers, so it won't be fatal. What they fear most are the SME brands that have just gone overseas for less than two years. They originally relied on low prices to capture the market, channels aren't stable, brand awareness is low. Raise prices and they lose orders; don't raise prices and they can't afford it, directly stuck in the middle with no way forward or back. They might even be forced to withdraw from some niche markets they just squeezed into.
But this matter shouldn't be calculated only in terms of money; one must also look at the policy trend. In previous years, the tax rebate rate was given high, encouraging everyone to stake out territory and seize the overseas market first; now lowering it, quite simply, means no longer encouraging going overseas by relying on low-price cutthroat competition. Relying on tax rebate subsidies to fight price wars will forever keep you wandering in the low-end market and easily attract anti-dumping investigations. The policy is forcing car companies to move up — don't always think about competing on price, compete more on products, brands, and premiums. Earning money with technical content is the long-term way.
Fuel vehicles didn't benefit from this dividend, nor did they suffer this blow. Originally, fuel vehicle exports were not large, nor were they the direction of policy support. This adjustment targets new energy vehicles precisely, aiming to cool down the rapidly growing export heat and squeeze out the excess. In the past two years, everyone rushed to go overseas, pushing prices down on each other. To grab orders, profit margins were thinner than paper. Exports looked like they were booming, but in reality, they made a name for themselves without making much money. Lowering the tax rebate rate just right washes out those players who relied on tax rebates to survive and had no core competitiveness.
In fact, visionary car companies started avoiding reliance on tax rebates long ago. Either build factories overseas for localized production, layout in multiple points like Thailand, Brazil, Europe, make locally and sell locally, avoiding tariffs and not being affected by export tax rebate fluctuations; or move towards the high-end, like NIO and Zeekr going overseas directly targeting luxury brands. The per-car profit margin is enough, that fluctuation in the tax rebate rate doesn't hurt the core. What they fear most are those who compete domestically then compete abroad, with no advantage other than cheapness. This wave just happens to hit them right in the crosshairs.
Short-term, this is growing pains, a batch of export players living on policy dividends will feel very uncomfortable; long-term, it is a good thing. Squeeze out the bubbles of low-level cutthroat competition, forcing Chinese car exports to shift from "quantity increase" to "quality improvement". Chinese cars cannot forever rely on policy subsidies to get by worldwide; sooner or later they must stand on their own feet with product strength and brand power. These four percentage points are both pressure and a turning point.

The export tax rebate rate for new energy vehicles drops from 13% to 9%, Chinese automakers need to recalculate the profits going overseas.
On October 12, the Ministry of Finance and the State Taxation Administration announced that starting from April 1, 2027, the VAT export rebate rate for new energy vehicles will be reduced from 13% to 9%. Superficially, this is just 4 percentage points, but for domestic automakers striving to go global, this could be a profit account that must be recalculated.
Why specifically now? Because exports have gradually transformed from incremental business into a crucial pillar supporting sales. According to CPCA data, from January to September 2026, new energy passenger vehicle exports from domestic markets reached 3.887 million vehicles, a year-on-year increase of 138.8%. September alone saw exports of 558,000 vehicles, a 163.5% increase year-on-year.
Domestic market pressure, overseas sales high-speed growth. On one hand, going overseas becomes more important; on the other, export tax incentives are tightening. The signal sent by the policy is clear: competition in automotive exports cannot rely forever on low prices and policy space.
01 Four Percentage Points, How Much Profit Is Actually LostFirst, a potentially confusing concept needs correction. 13% down to 9% refers to China's VAT export rebate rate, not a 4% tariff surcharge on Chinese cars added overseas, nor paying 4% tax on the retail price per car sold. According to current export tax rules, production enterprises usually apply the 'exempt, credit, and rebate' method. The difference where the rebate rate is lower than the VAT applicable rate results in a portion that cannot be exempted or deducted, ultimately accounted for in export costs.
Let's use an understandable assumption. A car company exports one new energy vehicle overseas. The FOB price used for tax calculation is 150,000 Yuan, applicable VAT rate is 13%, no special deductions like bonded materials. After the rebate rate drops from 13% to 9%, estimated under general 'exempt, credit, and rebate' terms, the new non-deductible cost corresponding to this car is approximately 6,000 Yuan.
If the profit margin in the original export link was only 10,000 Yuan, with other conditions unchanged, the book value might drop to only 4,000 Yuan. Profits decrease by 60%, far from the casual description of 'down 4%'.

But 6,000 Yuan cannot be regarded as a fixed loss for all car models. The actual amount depends on the export FOB price, whether the operating entity is a production enterprise or a foreign trade enterprise, imported bonded materials, input tax vouchers, and specific tax calculation methods. Results can vary significantly between different models and companies.
What is certain is that under the same transaction price and cost structure, a reduction in the rebate rate will squeeze the profitability of the domestic export link. Who ultimately bears the cost depends on subsequent negotiations.
02 Overseas Selling Prices May Not Rise AccordinglyThe most intuitive reaction is to pass on the new costs to overseas consumers. However, going overseas for car companies is not just converting domestic guidance prices with exchange rates. From the domestic factory to the overseas user's hand, there is ocean freight, insurance, import duties, certification, channel sharing, marketing, after-sales service, and local VAT. Changes in export rebates act on the Chinese export link. Overseas terminal transaction prices are determined by the entire value chain and market competition. The two are not a simple 4% against 4%.
Taking the 150,000 Yuan FOB price car from just now as an example again. If the new tax cost is assumed to be 6,000 Yuan, and the overseas landing transaction price converts to 300,000 Yuan, 6,000 Yuan is only equivalent to 2% of the terminal price. But even with only 2%, car companies dare not raise prices easily. Local consumers might be comparing BYD, Hyundai, Volkswagen, and Tesla. If the same class products offer better financial plans or promotional discounts, buyers might turn away completely.
A more realistic situation is cost sharing. Stronger brands and supply-tight models can attempt to moderately raise wholesale prices. For highly competitive models, manufacturers might first absorb part of the cost themselves, then renegotiate rebates and marketing budgets with importers and dealers. Some low-profit orders might simply not be accepted.

What the policy truly changes is not necessarily all overseas prices rising in sync, but rather the price floors of different models and dealer negotiation capabilities.
03 Who Is More Injured? Cannot Just Look at Group Gross MarginFor models with high gross margins and brand premiums, losing 4 percentage points in rebate is certainly uncomfortable, but not necessarily crippling. For models relying on extreme low prices to fight the market, this cut might hit the thinnest profit margin. Assuming two car companies export at the same FOB price, one originally has 12% profit space, the other only 4%. Under the simplified condition of no price increase and unchanged costs, the latter's operational impact is significantly larger.
Here we cannot directly rank based on group gross margins published by car companies. Financial report gross margins mix domestic sales, overseas sales, different models, parts, and other businesses, and cannot replace single-car export profits. True pressure distribution depends on the company's overseas sales structure, regional pricing power, supply chain costs, and export transaction chains.
BYD, Geely, SAIC, and Chery are all going overseas, but brand positioning, exported models, and localization progress are not the same. Within the same group, high-profit models and low-profit volume models may be affected completely differently.

Another easily overlooked target: foreign brands produced and exported in China. This policy targets export commodities meeting conditions and their tax treatment, not inherently targeting only domestic brands. Models produced and exported in Shanghai also need to judge applicable policies based on the actual export entity, commodity codes, and tax regulations.
This is not a simple 'Chinese Brand vs Overseas Brand' competition, but a change in cost structure of the Chinese manufacturing export link.
04 Europe's Trouble: Multiple Cost OverlapsIf Southeast Asia and Latin American markets mostly test price and channels, the situation in Europe is much more complex. The EU has already implemented countervailing duties on some purely electric passenger cars originating from China. EU final ruling states that the corporate tax rates corresponding to BYD, Geely, and SAIC are 17.0%, 18.8%, and 35.3% respectively, in addition to general import duties and other market costs. Note that countervailing duties and China's export rebates are two different policies, not simply added directly on the overseas retail price.
So for a company exporting complete vehicles from China to Europe, pressure does not appear alone. Export rebate space shrinking, import trade barriers, exchange rate and ocean freight cost changes, plus local brand price competition in Europe. Any item could affect final profits.
More critically, overseas markets usually do not allow guideline price adjustments as easily as domestic ones. Contract cycles, dealer inventory, model certification, and product launch rhythms all make price adjustments lag.

However, this does not mean Chinese car companies in Europe can only raise prices or exit. Models with high brand recognition may continue to hold selling prices with product power; enterprises with lower cost structures still have room for cost reduction; enterprises that have advanced overseas production have another choice.
This round of adjustment may accelerate car companies evaluating the economic account of complete vehicle exports vs overseas production. But relying solely on rebate changes, one cannot judge if a certain enterprise will definitely move production lines abroad.
05 Watershed: Export or Overseas ManufacturingBYD has been increasing overseas factories in recent years to shorten delivery cycles, get closer to consumers, adapt to tariffs and rules of origin, and build local supply chains. BYD's 2025 annual report disclosed that the Brazil passenger car factory achieved its first car off the line, the Thailand factory continues production, and overseas manufacturing layouts like Hungary are also progressing.
After the export rebate policy adjustment, the strategic value of this global manufacturing system will only be recalculated. However, overseas production is not a magic card that can immediately offset 4 percentage points. Factory construction, labor, energy, local supplier cultivation, production ramp-up, and quality control all require spending.
If it's just exporting parts made in China for overseas assembly, it involves tax on the parts themselves, local rules, and origin certification. For models with limited annual sales, moving factories overseas might be more expensive than losing part of the rebate.

Clearer division of labor may appear in future overseas expansion. Markets with large scale and stable sales prioritize local manufacturing; new markets still verifying demand continue to test the waters with complete vehicle exports; orders with too thin profits and heavy after-sales investment raise quotes or actively give up. This is both a recalculation triggered by tax changes and a lesson Chinese car companies must learn moving from 'selling cars out' to 'long-term operations locally'.
Tech Jungle CommentaryIn the view of Tech Jungle, the real impact of this export rebate drop from 13% to 9% is not 'Chinese EVs globally raising prices by 4%', nor 'car company profits immediately dropping by 4%'. It is more like pulling out a cushion originally used to buffer low-price competition from the industry chain, causing some problems masked by sales growth to resurface. What determines pricing? How much profit is made in each market? After export scale expansion, do profits grow in sync?
From the policy trail, photovoltaic, battery, and other products have already experienced export rebate adjustments. New energy vehicles now enter this sequence. After industrial development reaches a certain scale, policy focus is shifting from encouraging products to be sold out quickly to testing real competitiveness and sustainable operational capabilities. This is an industry judgment based on policy trends, not equivalent to official announcement to restrict new energy vehicle exports, nor can export rebate reduction be directly interpreted as an exchange condition for European trade negotiations.
Profits will be under pressure, overseas pricing may undergo adjustments, but in the end, it will absolutely not be a uniform result for all car companies. Enterprises that can build brand premiums, control costs, grasp overseas channels, and promote reasonable localization layouts still have ways to digest it. Enterprises relying on a few thousand yuan of profit to grab orders and with thin dealer networks may not be so composed.
The easiest thing for Chinese cars going overseas to present in the past was 'how many cars were sold'. Starting from 2027, another question will become more important: how much money did these cars actually make?
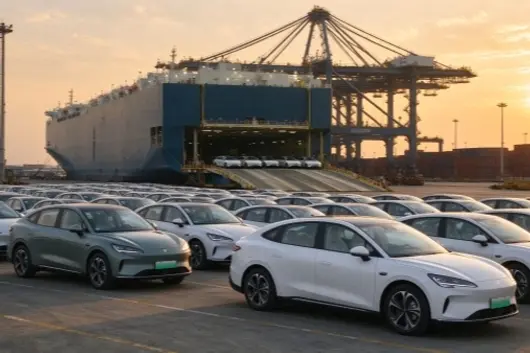
The continuous "price war" intensifies market involution, while also prompting Chinese automakers to expand into overseas markets. However, as the scale of China's automotive exports continues to grow, the competitive order and compliance in overseas markets are becoming the industry's focus.
Recently, the Ministry of Commerce, the Ministry of Industry and Information Technology, and the State Administration for Market Regulation jointly released a document—"Guidelines for Overseas Competitive Behavior and Compliance Construction in the Automotive Industry". This document directly points to a series of controversies triggered by frequent price cuts by Chinese automakers in overseas markets in recent years, and for the first time at the official level, systematically set clear compliance requirements for automakers' overseas pricing, promotions, and localized operations, among other behaviors.

Among them, Chery Automotive's response was swift and steady, clearly stating it will establish a scientific pricing system in overseas markets and regulate terminal prices and promotional behaviors. GAC Group was not left behind, with its statement stating, "Integrating compliance concepts throughout the entire R&D, production, supply, sales, and service chain". Moreover, BYD, Great Wall Motor, and Geely Holding Group also issued statements in response in succession.

From the industry's top-level call to standardize benign competition and eliminate spillover involution, to automakers generally recognizing the ineffective competition of low-price killing, the whole industry has formed a unified consensus on breaking the deadlock. However, reaching a consensus does not mean risks automatically dissipate; the warning bell against "involution" spillover must still ring long.
1
Export Acceleration, Compliance Faces Challenges
The background for the release of the "Guidelines" is the explosive growth in the scale of Chinese automotive "going global". Data shows that in the first 7 months of this year, China exported 6.14 million automobiles, a year-on-year increase of 66.8%. The monthly export volume first broke through the 1 million mark in June of this year, and July continued this trend, achieving consecutive two months of over 1 million automobiles exported. Industry predictions suggest the full year may hit 10 million.

Against the background of intensified competition in the domestic market, overseas exports have become the core growth engine for numerous Chinese automakers. Taking August sales as an example, BYD's single-month overseas sales exceeded 180,000, setting a new historical high; Chery exported 197,000, a year-on-year increase of 52.1%, with cumulative exports exceeding 7.18 million; Geely's overseas exports in August reached 110,100, a significant increase of 205% year-on-year. Great Wall Motor's overseas sales of 289,000 in the first half of this year have surpassed its domestic sales of 286,700; this is the first time in Great Wall's history that overseas sales have exceeded domestic sales.
Behind rapid expansion, the hazards of extensive overseas expansion are gradually emerging. Some enterprises expanding overseas continue to use the domestic "trade price for volume" strategy, with frequent price cuts, channel channeling, and failure to fulfill promises to dealers occurring from time to time. This not only harms consumer interests but also impacts the overall brand image of Chinese automobiles.
2
Overseas Markets Can No Longer "Price Arbitrarily"
Pricing is the core focus of this guideline. It is reported that the document urges vehicle and component manufacturers to avoid fierce price wars and significant price-cut promotions in overseas markets. It requires enterprises to base pricing on costs and local market supply and demand, avoiding frequent and large price cuts. Different configurations must have clear price gradients and cannot rely on low prices to disrupt local market order. At the same time, dealer channels must be regulated, and a complete compliance system for overseas after-sales, quality, and data security must be improved.

The intent of "admonishing" in this section is obvious, referring precisely to the "involution" spillover that everyone has been very familiar with in recent years. Many automakers, after expanding overseas, adopted aggressive methods such as price cuts to quickly grab market share. Although this was due to market behavior, it did exert certain impacts on the stability of the local market. There are already some negative cases, for example, in the Thai market, some automakers made successive price cuts in Thailand, raising the dissatisfaction of users who had already purchased cars. Thai public institutions also launched investigations into this matter.
This scene inevitably recalls the past lessons of Chinese motorcycle exports to Southeast Asia. If Chinese auto enterprises continue to blindly "involute" and replicate the domestic price war tactics, it will only undermine the value of Chinese brands, and even trigger anti-dumping and trade protection investigations by local regulators. This is a very dangerous signal for Chinese automakers who are just beginning to emerge in overseas markets.

The purpose of the state issuing relevant guidelines this time is clear: no longer solely encouraging the expansion of export scale, but beginning to standardize and manage the increasingly complex global business layout. In other words, previously Chinese automobiles competed on "whether they could go out", but now they are competing on "whether they can stay".
Overseas markets are full of gold mines, automakers must not mess this up. Chinese automakers going overseas cannot just think about selling cars; they must also learn to do business long-term and in a compliant manner. After all, the outcome of long-term competition no longer depends on who has the lower price or faster shipment, but on the comprehensive ability of localized operations, global compliance governance, supply chain collaboration, and brand building.

Currently, China's automotive export faces dual pressures of intensifying trade barriers and the spillover of internal price wars. The joint release of compliance guidelines by the Ministry of Commerce and two other ministries is precisely to curb malicious competition. Of course, the guidelines are essentially guiding, non-mandatory regulations. To be implemented, it ultimately depends on whether enterprises can reach a true industry consensus and take concrete actions.
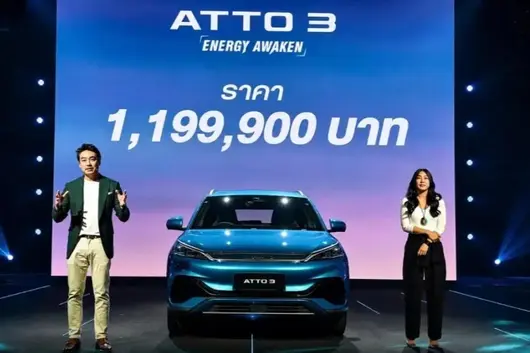
On September 1, 2026, the Ministry of Commerce, the Ministry of Industry and Information Technology, and the State Administration for Market Regulation jointly released a document titled "Guidelines for Overseas Competition Behavior and Compliance Construction in the Automotive Industry."

The document consists of four chapters and twenty articles, with clear core requirements: establish a cost-based overseas pricing strategy to avoid affecting the interests of overseas consumers and brand image due to frequent and significant price fluctuations; at the same time, require automakers to strengthen product overseas assessment to avoid launching products that do not meet the needs of the target market and usage environment.
Going global has been one of the themes of the automotive industry in recent years. In 2025, China's automobile exports reached 8.32 million units, sold to over 200 countries and regions. Meanwhile, Chinese automakers have also invested in the local automotive manufacturing industry in over 80 countries and regions.
However, at this time, the issuance of such a document related to overseas market competition for automobiles might indicate a problem: behind the scale expansion, concerns about overseas order are surfacing. Why this timing? The answer may be hidden in an event from more than twenty years ago: the entire process of Chinese motorcycles going from peak to collapse in Southeast Asia.
#Motorcycle Tragedy: Lessons from Market Share Dropping from 80% to Less Than 1%#
In the late 1990s, Chinese motorcycles had already gone abroad and welcomed a highlight period in the Southeast Asian market.
Previously, the motorcycle market in Southeast Asia was firmly held by Japanese brands. Top brands like Honda, Yamaha, and Suzuki monopolized over 90% of the Southeast Asian motorcycle market. The average unit price at that time was around $2,000.
After 1997, Chinese motorcycle brands such as Loncin, Jialing, and Zonsun sequentially went out in batches. Relying on significantly lower prices than Japanese brands, they quickly seized the market with extremely low pricing of $500-$700. By around 2002, Chinese motorcycles completely suppressed Japanese brands in market share in core areas like Vietnam.

Motorcycle companies at that time produced parts in China and assembled them in local markets like Vietnam. Market share rose rapidly from 23.8% in 1999 to 75.2% in 2000, reaching 80.5% in 2001. In 2001, the market share of Chinese brands exceeded 60%; in 2002, the export value reached 1.92 billion US dollars, and the overall market share climbed to 80%.
However, such prosperity did not last long. Seizing the market through price made these motorcycle companies taste the sweetness. The short-term rising market share also made them believe that this extensive competition logic would continue to work.
Thus, bottomless price involution appeared. Competitors frantically snatched orders and continuously cut prices. The profit per vehicle export was directly compressed to single-digit US dollars. Motorcycle companies no longer valued quality, only volume; some even started one-off deals, dumping unsold domestic products in the local market, selling off inventory and running away, with absolutely no after-sales service.
The result of such competition was predictable. Product quality experienced a systemic collapse in the short term. Cost pressure forced them to cut corners on parts. Vehicles普遍 showed serious faults such as engine oil leaks, frame fractures, and uncontrolled fuel consumption. In the eyes of Southeast Asian consumers at that time, Chinese motorcycles had a very high repair rate, frequent minor faults, requiring major repairs in less than 3 years, and being scrapped after 4-5 years.

In 2004, a motorcycle made in China suddenly fractured its frame while driving in Ho Chi Minh City, causing serious injuries to the rider. Vietnamese media reported wildly, and the country was swept up in a hot discussion about the durability of Chinese products.
Against this background, Japanese brands began to fight back. Honda launched affordable models, combined with buyout after-sales, deep localized supply chains, building a full-cycle service barrier that Chinese manufacturers could not resist. Finally, within the two years from 2004 to 2006, the market share of Chinese motorcycles plummeted from 80% to less than 1%. Subsequently, Japanese motorcycles regained 95% of the market share with stable quality.
Chinese motorcycles failed in Southeast Asia. The root cause here might not be that Japanese brands have an absolute technological gap in the motorcycle field, but simply endless involution. As of 2025, the total annual motorcycle sales in the Thai market reached 1.7118 million units. Japanese brands like Honda and Yamaha had a market share as high as 96.2%, while mainland Chinese brands retained only 0.69%.
Twenty years have passed, and this lesson seems to be being forgotten, especially as today's Chinese automotive industry seems to be a mirror image of the motorcycle industry twenty years ago.
#Chinese Automobiles: Running Wild While Planting Mines#
In recent years, after the Chinese automotive industry started industrial transformation, domestic car companies have not slowed down on this runaway road, especially in the overseas field. Starting from less than a million units in 2020, Chinese automobile exports completed a stunning leap in just a few years.
Total car exports in 2025 reached 7.098 million units (data from China Association of Automobile Manufacturers), up 21.1% year-on-year. Among them, new energy vehicle exports reached 2.615 million units, doubling year-on-year; and calculated by the broader statistical scope of the China Passenger Car Association, total exports in 2025 were as high as 8.32 million units.

Entering 2026, this momentum did not decrease at all. Car exports in the first half of the year reached 5.096 million units, a猛增 of 65.3% year-on-year, breaking the 5 million unit mark for the first time in half a year; July single-month exports were 918,000 units, up 87.8% year-on-year. Multiple forecasts predict that Chinese car exports in 2026 are expected to break through 10 million units for the first time.
It has to be said that these data look very eye-catching, but behind the brilliance, Chinese cars going overseas are encountering risks highly similar to the motorcycle tragedy back then.
Chinese automakers have already involutioned to the limit domestically. In the first half of 2026, the profit margin of the automotive industry's whole vehicle manufacturing dropped to 1.5%, reaching a new low in nearly ten years; 630 new cars clustered to launch, 95% monthly sales did not exceed 10,000; domestic sales dropped more than 20% year-on-year. Involution cannot continue in the domestic market, so many automakers turned their attention overseas.
Overseas markets are undoubtedly blue oceans compared to the domestic market,本该 be a incremental market with larger survival space and broader prospects. But the bad thing is, some automakers took the domestic tactics overseas as well.
Signs of 'involution' spillover have already appeared. In incremental markets such as Southeast Asia, the Middle East, and South America, some Chinese automakers concentrated into the A-level new energy passenger car track. Prices overlapped heavily in the 100,000-150,000 yuan range. The domestic tactic of 'trading price for volume, rapid distribution' was translated over, forcing other automakers to adopt similar response strategies.
In some regional channels, disorderly marketing behaviors such as cross-regional siphoning by dealers belonging to the same Chinese brand and frequent price cuts appeared; even more, some enterprises compressed after-sales spare parts reserves and user service investments to rush short-term sales rankings, simplifying overseas channel construction into an extensive model of 'finding agents, selling wholesale'.

In the Thai market, the selling price of Chinese brand electric vehicles has dropped from an average of about 1.2 million baht in 2023 to an 800,000 baht range in 2026. The BYD Dolphin partial version price dropped from 800,000 baht to more than 500,000 baht. The price plunge triggered a chain of negative effects: vehicle second-hand residual value significantly shrunk, a large number of owners' loan balances exceeded vehicle valuation, and some brands faced consumer complaints for dropping prices too aggressively.
From 2024 to 2026, the Thailand Consumer Protection Committee and Consumer Committee collectively accepted 1,348 complaints related to electric vehicles. The complaints focused on four aspects: frequent price drops destroying user asset expectations, resource mismatch of emphasizing sales over after-sales, instability of new forces' operations causing consumer anxiety, and vehicle actual performance not matching promotion.
The new version of the 'Lemon Law' (Draft Law on Product Defect Liability) being promoted in Thailand has clearly included electric vehicles in the scope of key protection, implementing inverted burden of proof. If a fault occurs within 1 year of vehicle delivery, it is directly presumed that the defect existed at delivery, and the automaker/seller must prove the defect was not factory-integrated, without consumers needing to collect evidence themselves.
At the same time, issues and doubts such as chassis rust and missing after-sales are emerging. A foreign car review website summarized the five high-frequency problems of Chinese electric vehicles: unstable software, insufficient after-sales network, spare parts supply delays, ADAS calibration weaknesses, and rapid depreciation of residual value. Doubts such as 'chassis rust through in two years', 'missing after-sales', 'parts supply interruption' continue to ferment on overseas social media.
#Signals of the Motorcycle Tragedy Have Already Appeared#
Chinese automobile brands are facing multiple challenges in overseas markets. With exports aiming for the 10 million unit mark in 2026, some problems also began to expose concentrated.
From the perspective of the product itself, product quality concerns are the most direct and also have a relatively large impact factor. Many models exported overseas are basically developed in China's native land. However, overseas markets differ from China's native environment. After entering overseas markets, some adaptability issues will occur.
For example, high electricity consumption on unlimited speed highways in Germany; in Russia, Northern Europe, etc., chassis is prone to rust due to de-icing agents; in Mexico and other areas with complex road conditions, power and noise control performance is poor. Overseas user complaints include battery faults, range shrinkage, unstable software, intelligent driving assistance system (ADAS) calibration defects, etc. Multiple Chinese automakers have had recalls overseas.

In addition, Chinese cars ran overseas, but the entire after-sales service system has not caught up. Currently, overseas markets generally suffer from insufficient after-sales outlets, delayed spare parts supply, lack of repair technicians, etc. Moreover, inconsistent charging standards across different countries and fragmented APP ecosystems also increase service difficulty.
One point worth noting is that if after-sales related issues do not catch up, it brings a series of chain reactions.
Recently, several overseas insurance companies have tightened or even refused to provide insurance services for Chinese new energy vehicles. In mid-August, Dutch top insurer Univé (members over 1.8 million) updated underwriting rules citing 'shortage of parts, imperfect repair network, lack of technical data'.
Brands like Hongqi, Changan, Voyah, Leapmotor, Jetour, OMODA, and Mengshi, the insurance company completely refused coverage; brands like Dongfeng, Nio, Firefly, Zeekr could only purchase the legally minimum third-party liability insurance; BYD, MG, Lynk & Co have complete localized service systems locally and are currently unaffected.

Univé emphasized that this move has nothing to do with vehicle quality or country of origin. The root cause is that some brands' 'after-sales service system construction did not catch up with the expansion rhythm', for example, a repair shop waited for a Chinese brand electronic control unit for nearly 200 days, during which additional costs like replacement cars, parking fees, etc. approached 18,000 euros, equivalent to five months of wages for a regular full-time employee in the Netherlands.
The same situation exists in the UK. Due to lack of historical claims data, high repair costs, and immature supply chains, insurance companies generally hold a cautious attitude towards Chinese brand vehicles. A survey shows that half of Chinese brand insurance requests were rejected, and even for insurable policies, prices were sometimes nearly double that of equivalent fuel cars.
Like Jaecoo 7 with an average annual premium of 1,103 pounds, while the equivalent Skoda Karoq is only 577 pounds. The reason also comes down to after-sales. The UK Association of British Insurers report shows that repair costs for some Chinese brand models are 30%-50% higher than equivalent European brands. These issues all point to one factor: selling the product is just the first hurdle; building a perfect, reliable localized service system is the key to whether one can truly stand in the overseas market.
#Involution Domestically Then Overseas, Why Lose Rationality?
Chinese automakers clearly know the harm of involution. Whether it's industry gatherings or national appeals, everyone actually knows involution does harm and no benefit. However, domestic appeals have been made for so many years, without a single person stopping. As for why still take the fire overseas? This is actually a question worth thinking about.
The reasons behind this are nothing more than these points.
First, involution has become unviable domestically. The total volume of the domestic market has basically stabilized at the current magnitude. New incremental volumes will definitely not appear in the near future. The data that domestic sales dropped more than 20% year-on-year already illustrates the problem. However, under such circumstances, domestic automakers dare not stop, because stopping means exiting the market. Then going overseas is no longer a choice for new incremental volume, but a choice to survive.
Secondly, overseas might have higher profit margins. Currently, the pricing of Chinese brand products overseas is generally higher than domestic. Moreover, whether new energy or intelligence, compared to products in overseas markets, this is still considered a differentiated advantage of Chinese automakers. So with the domestic industry profit margin left at only 1.5% now, the opportunity in the overseas market forces people to have a gambling mentality.
Finally, domestic capacity needs an outlet. Now the total design capacity of domestic whole vehicles is to exceed 40 million units, but the current capacity utilization rate is only less than 60%. These capacities no longer have space in the domestic market to consume. So going overseas actually becomes the only choice.
But the problem is that now many automakers go overseas to make money, to survive. From a human nature perspective, we all know that under extreme conditions, people are very likely to make some irrational things. So the means of involution naturally some people will not let go. However, the most critical problem is that overseas markets are by no means a simple externalization of the Chinese market.
But as mentioned before, 'Chinese medicine' cannot cure involution, but there are plenty of 'Western medicine' means. Chinese cars going overseas好不容易 gained the current scale. If we never remember the historical lessons before, then it is very likely that due to short-sighted behaviors of some enterprises, the achievements and credit accumulated by the whole industry over the years will be destroyed.
#Where is the Solution? Only Refined Operations Can Leverage the Market#
The 'Guidelines for Overseas Competition Behavior and Compliance Construction in the Automotive Industry' released by the three departments is exactly the official response to this problem. The document emphasizes the basic principles of compliance with laws and regulations, fair competition, and mutual benefit and win-win. Essentially, it is guiding automakers to shift from 'price-driven' to 'value-driven'.
To truly achieve benign expansion overseas, there is only one road: refined operations coupled with deep local planting.
BYD's approach in Japan is an example worth referencing. In July this year, BYD's pure electric K-Car 'Otter' (RACCO) exclusively designed for the Japanese market officially launched, with a guide price of 2.145 million to 2.497 million yen. This is not selling Chinese models under a new name to Japan, but a car developed 'from scratch' targeting Japanese consumption scenarios.

Right-hand steering, column shifter, four seats, vertical umbrella slot, A-pillar triangular window to reduce blind spots. To adapt to K-Car specifications, length, width, height do not exceed 3400/1480/2000mm. BYD redesigned body dimensions, battery layout, and space plans. More importantly, BYD gave up the tactic Chinese markets are best at in Japan: not fighting on price, fighting on configuration.
Otter is equipped with two blade battery types of 22.4kWh and 35.84kWh. Range reaches 210 km and 320 km respectively, the longest range among Japanese pure electric K-Cars. The whole series comes standard with V2L external discharge and V2H car-to-home power supply. In comparison, Nissan Sakura and Mitsubishi eK XEV are equipped with 20kWh batteries, range 180 km, starting price 2.33 million to 2.39 million yen. The Otter entry-level version not only has a price about 190,000 yen lower, but range increased by 30 km instead.
Within two weeks, 1,000 orders were secured, about 80% from the top configuration version. In the context of the Japanese domestic market imported car total market dropping 10% year-on-year, the Otter grew by 69%.
Furthermore, Chery partnered with EBRO in Spain to revitalize the former Nissan factory in Barcelona; Geely acquired 34% equity of Ford's Spain factory for 221 million euros; BYD's production base in Bahia, Brazil has officially gone into production, over 50,000 vehicles went off the line. From whole vehicle exports to localized production, from selling products to building systems. Although this road is harder than whole vehicle exports, it is also the only road that can be passed through currently.
Anyway, the 'Guidelines for Overseas Competition Behavior and Compliance Construction in the Automotive Industry' released by the Ministry of Commerce and three other departments is the first normative document for this industry to systematically reflect on 'how to go overseas'. It also reflects that the current Chinese automotive industry has realized the reality that it cannot continue this way.
However, the document is still just a document. What can truly stop 'involution spillover' still relies on the consciousness of every overseas automaker. The story of Chinese motorcycles in Southeast Asia going from 80% to less than 1% is still before our eyes.
Chinese car exports are standing at a critical turning point connecting the past and future. The victory or defeat of long-term competition depends not on whose price is lower and who ships faster, but on the comprehensive ability of localized operations, global compliance governance, industrial chain synergy, and brand building. Refusing involution spillover is not a slogan, it is the bottom line Chinese car exports must maintain.
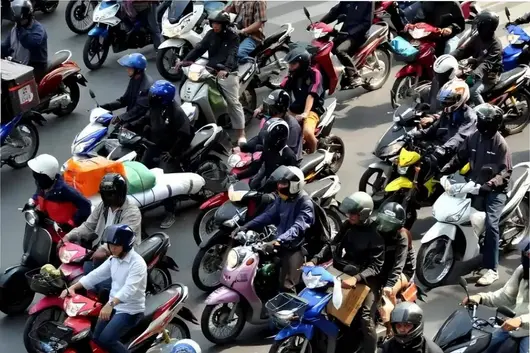

The Future of Chinese Cars is the Global Car.
Author | Niu Li
Producer | Car Traveller
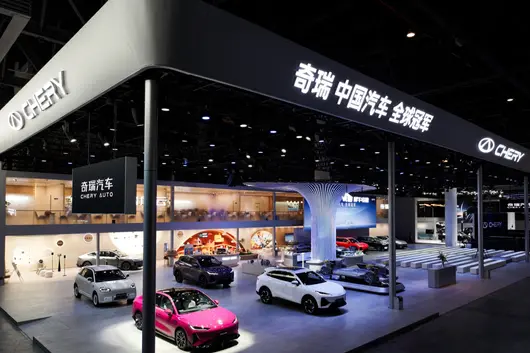
The 2026 Chengdu International Auto Show officially kicked off on August 21.
Chery and BYD were the only two automakers to occupy the entire pavilion at this year's auto show, which has become a popular topic of conversation.
On the facade of the Hall 5 occupied by Chery, the theme "Chinese Cars, Global Champions" was very prominent. At first glance, it might be unclear what it means, but when you walk into the exhibition hall and carefully finish viewing the brands, display cars, and technology exhibits brought by Chery, you will have a deeper understanding of this theme.
At this auto show, the Chery Group showcased a total of 38 models from its five brands: Chery, Exeed, Zongheng, Jetour, and iCAR.
From global models like Fengyun T7 and Arrizo 7, to the Rhino Battery and Kunpeng Power technology zones, and finally to the Ruixiang Ecosystem Space covering lifestyle, it can be said to be a panoramic presentation of Chery's more than twenty years of globalization accumulation.
When "Going Overseas" has become a collective keyword for the Chinese automotive industry, and when most automakers are still studying "how to sell cars abroad", Chery is already exploring deeper answers:
True globalization has never been about simply selling Chinese cars overseas; it is about building "Native Global Cars" that are oriented towards the global market in R&D, design, quality, and ecosystem.

From ranking first in Chinese brand passenger car exports for 23 consecutive years to joining the top ten global automakers in sales, Chery's globalization path provides a reference sample of long-termism for Chinese cars going overseas.
01
Native Global Car: Anchoring Global Standards from the First Day of R&D
"A true global car must be anchored globally from the start of R&D, not developed domestically first and then modified for export."
At the launch of this auto show, Li Xueyong, Executive Vice President of Chery Automobile Co., Ltd., explained Chery's understanding of global cars.
This sentence precisely pinpoints the core difference between Chery's globalization and the industry's common model.

For a long period in the past, Chinese automakers going overseas mostly adopted the path of "Localizing Domestic Models for Modification": completing the whole vehicle R&D targeting the Chinese market first, and then making regulation adaptation and configuration adjustments for the export market after launch.
This model has low R&D costs and a fast pace, but it naturally has the problem of "adaptation compromises"—chassis tuning, safety standards, and function design are all centered on domestic needs, making it difficult to fully meet the differentiated needs of overseas users.
And the "Native Global Car" strategy being promoted by Chery has reconstructed the R&D logic from the root.
As the first Native Global Car model of the Smart Electric Era, Fengyun T7 has thought and planned from the product definition stage from the perspective of the global market.

For example, at the regulation level, the team pre-researched safety and emission regulations in different parts of the world 2 years in advance, directly benchmarking the whole vehicle design against the 2026 Edition E-NCAP standards to avoid compliance risks later from the source;
At the user demand level, Chery surveyed more than 5,000 users globally, covering car usage scenarios in 15 typical countries, integrating body differences, driving habits, and usage preferences of different regions into the product definition in advance.
To adapt to the complex and diverse car usage environments globally, Fengyun T7 completed rigorous verification covering 7 major categories of extreme environments: 500mm off-road wading in the Southeast Asian rainy season, electronic equipment heat protection under Middle East high-temperature sun exposure, odor control in Indonesian high-humidity environments, wiper blade lifespan reinforcement in Siberian extreme cold weather, interior lighting optimization in Nordic polar nights, battery connector protection on Brazilian gravel roads, and durability noise verification on Mexican cobblestone roads.

Chery invested in 81 dedicated durability test vehicles for simultaneous road trials, with the whole vehicle cumulative test mileage exceeding 6 million kilometers, of which 1.45 million kilometers were dedicated durability actual tests, covering more than 100 extreme road condition environments such as the EU, Australia/New Zealand, Middle East, and South Africa.
It is precisely for this reason that Fengyun T7 was able to achieve a global simultaneous launch rhythm: launched first in South Africa and Thailand, landing in China and Indonesia markets in August, entering the EU in September, and covering Australia/New Zealand, UK, Malaysia and other regions successively in October. During the pre-sale phase, orders for this car exceeded 16,787 units in just 9 days, with users under 35 years old accounting for 65.2% and female users accounting for 35.7%, confirming the universal appeal of global native design to users in different markets.
Also following the logic of Native Global Cars is the Arrizo 7, making its global debut at this auto show.

As a landmark model in Chery's forward-looking development, the Arrizo series has been carrying Chery's global sedan dream since its birth in 2013. The first-generation Arrizo 7 was the first independent model in China to adopt the international common "V-shaped" forward-looking development process.
Now the all-new Arrizo 7 sets out again. From the first day of the project, it was positioned for global development and global adaptation, conducting R&D simultaneously around roads, climates, and car usage needs in more than 70 countries globally.
In design, the core language is "Momentum of Moving Water", transforming the Eastern philosophy of "The highest goodness is like water" into an aesthetic expression that global users can empathize with;
In terms of power, it offers two choices: Kunpeng Fuel and C-DM Super Power Electric Hybrid, with one car dual energy adapting to different countries' energy structures;
In terms of safety, it is designed according to global five-star standards, covering evaluation systems in multiple regions.
The return of Arrizo 7 is both the inheritance of Chery's forward-looking development genes and the extension of its Native Global Car strategy to the sedan category.
02
Oriental Design Breaking Boundaries: Chinese Cultural Expression in Global Aesthetics
If native R&D is the underlying skeleton of global cars, then design and cultural identity are the soul of global cars.
A true global car must not only meet global regulations and quality standards, but also trigger resonance among global users at the aesthetic and emotional levels. In this regard, Chery has taken a path of "Oriental Originality, Global Resonance" in design.
The Fengyun A9, which appeared side-by-side at this auto show, is a typical representative of this path.
This model, positioned as a long-range Smart Beauty Coupe, takes "Lingfeng Aesthetics" as the design core, integrating the introversion and tension of Oriental aesthetics into the whole vehicle shape, and won the 2026 German Red Dot Product Design Award with its highly original design language.

In the current industry trend where everyone follows cloning and excessively pursues exaggerated shapes, Fengyun A9 used highly confident Oriental original design to get backing from international top design authorities.
Behind this is the transformation of the role of the Chinese automotive industry: In the past, we were participants in global manufacturing, following overseas design standards; now, Chery is becoming one of the definers of global design trends, using modern expressions of Oriental aesthetics to influence global car aesthetics.
If Fengyun A9 is the upward breakthrough in high-end design, then the all-new QQ3 is the global empathy of mass culture.
In the history of the global automotive industry, small cars have never been just transportation tools, but cultural symbols carrying emotional expression among young groups—Europe has the Beetle and Mini Cooper, which transcend the product itself and become spiritual labels for young people of a generation. And in the process of Chinese cars going global, the QQ series is taking on such a role.
Even before the launch of the all-new QQ3, Chery Group Chairman Yin Tongyue stated at the launch event that he hoped QQ could become "China's Beetle, Mini Cooper".
Since its birth, the QQ series has accumulated 1.6 million users globally, and has become the first car for many young people with its affordable price and personalized shape.
After the launch of the all-new QQ3, domestic sales broke 10,000 for four consecutive months, and orders broke 10,000 in the first month after landing in Indonesia and Thailand markets, showing strong attraction across regions.
To meet users' personalized modification needs, Chery launched the QQ3 Modern Edition at this auto show. Taking retrofuturism as the concept, it fuses classic elements of a hundred years of automotive industry with the technological feel of the Smart Electric Era. Houndstooth interior, mirror chrome wheels, retro color block decals, this understanding of small car culture and empathy for young users knows no national borders.

From Fengyun A9's Oriental aesthetics winning international awards, to the QQ series becoming a cultural symbol for global young people, Chery is proving: Good design never needs to deliberately cater to one market. Standing on local culture and挖掘 human common aesthetics and emotions, it naturally wins the recognition of global users.
03
From "Going Out" to "Taking Root": Localization Philosophy of the 23-Year Export Champion
To measure an automaker's degree of globalization, it's not enough to just see how many cars were exported, but more importantly to see if it has truly integrated into the local market to become part of the local industry and society.
Chery has ranked first in Chinese brand passenger car exports for 23 consecutive years, and this relies not only on product power, but also on the localization business philosophy of "Wherever it is, for there, becoming a part of the locals".
Latest data shows that in July 2026, Chery Group exports reached 202,533 vehicles, a year-on-year increase of 70.1%, making it the first automaker in China to exceed 200,000 vehicles in a single month's export, equivalent to one Chery car being driven overseas every 16 seconds. From January to July 2026, Chery's cumulative exports reached 1,146,350 vehicles, a year-on-year increase of 71.2%, quickly breaking the million-unit level. As of the end of July, Chery's global cumulative car users have broken 20.16 million, among which overseas users exceed 6.99 million, with products sold to more than 130 countries and regions.
Behind the eye-catching sales figures is Chery's "Going Deep" globalization strategy.
Unlike many automakers' models centered on complete vehicle export, Chery has long completed the upgrade from "Product Going Overseas" to "Industry Going Overseas".
Currently, Chery's overseas employees have exceeded 20,000, with overseas factory local staff accounting for 85%, achieving full localization of talent, supply chain, and production.
In Spain, Chery rejuvenates local national car brands through joint venture factories, creating more than 1,000 local employment positions;
In South Africa, after the new factory officially started, it fully retained the original more than 690 employees and drove more than 3,000 employment opportunities up and downstream.
This deeply integrated local economic and social model makes Chery not just a "foreign brand that sells cars", but a participant and contributor to local industrial development.
It is precisely relying on this solid localization layout that Chery has continued to achieve breakthroughs in the global high-end market.
From January to June 2026, Chery's cumulative sales in Europe exceeded 174,000 vehicles, a year-on-year increase of 212%, among which new energy vehicle sales reached 86,000 vehicles, a year-on-year surge of 385%, with the new energy ratio approaching half.
In Spain, Chery's brand cumulative sales exceeded 50,000 vehicles, a year-on-year increase of more than 90% in the first half of 2026, ranking among the top three Chinese brands;
In the UK, Chery has consistently ranked second in the monthly sales total list for three consecutive months since March;
In Australia, Chery has maintained positive sales growth for 22 consecutive months, and the sales of some pure electric models are second only to Tesla Model Y;
In May 2026, Chery officially entered the Canadian market, becoming one of the first Chinese automakers to layout the North American market.
From emerging markets to Europe, America, and Australia developed markets, from complete vehicle export to local production, Chery has walked out a steady and stable globalization path in 23 years.
04
Quality and Technology Dual Support: The Confidence of Long-termism in Globalization
Of course, whether the path of globalization can be walked for a long time eventually has to return to the product and technology itself.
Global market competition, in the end, is a competition of quality and technology. Chery can stand firm in more than 130 countries, relying not on low-price strategies, but on product quality and technical strength that can withstand global market testing.
At the quality level, Chery's global quality has been repeatedly verified by authoritative institutions.
In June-August 2026, in the five core studies released by J.D. Power: New Vehicle Quality, Product Appeal, Buying Experience, After-sales Service, and Vehicle Reliability, Chery took the first place among all independent brands, becoming the only independent brand to take the "Five Grand Slam" in the year.
At the safety level, Chery has accumulated 71 models obtaining five-star safety certification in global markets such as China, Europe, Australia, and ASEAN, ranking first among Chinese brands in the number of five-star safety models.
Accumulating small steps, one can reach a thousand li.
These achievements were not blown out by marketing, but are polished and accumulated by on-site testing and verification of one car after another, and by grinding out point by point with global unified R&D and verification standards.
Chery has currently deployed 8 major R&D centers globally, building a R&D system covering the globe. Every global model must undergo extreme environment verification such as high temperature, extreme cold, plateau, and high humidity, using unified standards to guarantee that global users can obtain consistent quality experiences.
At the technology level, Chery is also continuously supplying ammunition for globalization.
The technical results exhibited at this auto show, such as Rhino Battery, Kunpeng Power, Flying Fish Digital Intelligent Chassis, etc., are a concentrated presentation of Chery's technology system.
Taking Rhino Battery as an example, breakthroughs were achieved in safety and energy density through technological innovations such as high enthalpy change separators, active defense electrolytes, and composite current collectors, and 400Wh/kg solid-state batteries have also entered the exhibition stage.

The Kunpeng Power system covers multiple technical routes of fuel, hybrid, and pure electric, and emerging technologies such as variable flux motors and axial flux dual motors continue to land. The continuous iteration of these underlying technologies provides solid support for the product power of Chery's global models.
It is precisely relying on the dual foundation of quality and technology that Chery's industry status in the global market continues to rise.
In January-June 2026, Chery Group's global sales share reached 4.1%, ranking ninth globally. In the list of the top ten global automakers in sales, Chinese automakers BYD, Geely, and Chery appeared for the first time, and Chery is the one with the highest degree of globalization and the deepest overseas layout among them.
Viewpoint:
The Future of Chinese Cars is the Global Car
Looking back from the new starting point of 20.16 million global users, Chery's more than twenty years of globalization path is exactly a microcosm of the Chinese automotive industry going overseas.
From initially earning foreign exchange through complete vehicle export, to later building factories for local operation, and now to Native Global Cars and global unified standards, Chinese cars' going overseas is moving from "Product Output" to a new stage of "Brand Output, Standard Output, Cultural Output".
And Chery has already grown into the complete appearance of a global enterprise:
8 major R&D centers covering the globe, a production and supply chain system rooted locally, a product matrix sold to more than 130 countries, and more than 20 million global users.
It is not just a Chinese automaker, but a true global automaker.
"Chinese Cars, More than Global Cars", this sentence placed on today's Chery, is no longer a slogan, but a fact that is happening.
It can be foreseen that with the continuous improvement of the overall strength of the Chinese automotive industry, and with the continuous perfection of Chery's globalization system, more native global cars like Fengyun T7 and Arrizo 7 will be driven to all corners of the world in the future, and as a pioneer on this road, Chery will also occupy a more important position in the new pattern of the global automotive industry.

August 12, Chery Fengyun T7 officially starts pre-sale, 3 versions, 109,900 yuan - 129,900 yuan. Launch event theme is interesting — "Slow work builds good cars, sorry for the wait". In the industry today where everyone is eager to launch a new car within 12 months, the word "slow" seems somewhat out of place. But this car's "slow" is exactly where it's worth discussing.

A Car That Goes Abroad First, Then Returns Home
Fengyun T7's most special identity is: it didn't first build it domestically and then plan to sell abroad; instead, the same-source model Lepas L6 has already started pre-sales in South Africa, Thailand launched on July 24, followed by Indonesia in August, EU in September, Australia, New Zealand and UK in October. Others go domestic first then export, it takes the "reverse export" path.

The logic behind this rhythm is easy to understand — a car must simultaneously meet Europe's collision regulations, Middle East's over 50 degrees high temperature, Southeast Asia's rainy season flooding, Nordic's minus 40 degrees extreme cold. R&D and verification cycle cannot be short. Fengyun T7 used 2 years planning, 3 years R&D, benchmarking the not-yet-formally-implemented 2026 version E-NCAP 5-star safety standard. 81 dedicated durability vehicles synchronized road testing, total vehicle cumulative testing over 6 million kilometers. These are not lab data, they are actual vehicles driven over high deceleration humps in Brazil, cobblestone roads in Mexico, unpaved muddy roads in South Africa.
All Series 600km Range, Entry-Level Fully Equipped
Fengyun T7's most unconventional decision is: all series standard equipped 600km CLTC range, actual test can run 667km+. No trick of low trim cutting range, three configurations batteries are all 65.05 kWh LFP Rhino Battery. Charge from 30% to 80% only takes 20 minutes, takes the time of drinking a cup of coffee.

Willing to spend heavily on safety aspect — 80% high-strength steel + 18.84% hot-formed steel, 9 horizontal 5 vertical cage body, all series 9 airbags, rear side airbags and 48L dual-chamber far-end airbags both given. Rhino Battery IP68 waterproof is 96 times the national standard. Intelligent cockpit used 4nm process 8775 chip, 72 TOPS computing power, 15.6-inch 2.5K large screen. Intelligent driving aspect 22 sensors, supports 300+ scenarios automated parking.
Chassis Tuning is the Hidden Bonus
Fengyun T7 specially hired former Maserati chassis expert team for tuning. 50.8:49.2 front-rear weight distribution, cornering without understeer, lane change without oversteer. This tuning expertise is not trained in one day, Chery has worked on chassis test rig field for 26 years. Rear-wheel drive layout plus multi-link independent suspension, rare at this price range. Space aspect wheelbase 2700mm, rear seats folded can form 1955mm pure flat large bed.

Benefits Completely Address Future Worries
What makes people feel most at ease is actually benefits — power battery thermal runaway damage due to battery reasons, directly compensate with a new car of the same model; if an accident occurs within one year of purchase due to intelligent driving system, compensation up to 5 million. Plus whole vehicle lifetime warranty (including three-electric system), basically solves future concerns completely.

109,900 yuan starting price at this level pure electric SUV not cheapest, but all series 600km range no price premium, global model quality endorsement, plus this safety config and chassis foundation, competitiveness is solid. Competitor aspect, Deepal S05 has market reputation, Changan Qiyuan Q05 more aggressive in intelligent driving. Fengyun T7 differentiation is: others first domestic then overseas, it first lets global market verify then return home — this "reverse input" logic, in 100,000-level pure electric SUV indeed rare.
Whether a car is good or not, know after driving. But at least on paper, Fengyun T7 made "slow work builds good cars" into visible and tangible product strength.
Recently, there has been an interesting phenomenon in the Chinese automotive circle: while domestic market price wars are fierce, top car companies are quietly "making big money" in overseas markets.
Geely's May performance report that was just released has already hinted at some unusual signals — Overseas export sales exceeded 85,000 units, a year-on-year increase of 184%, setting a new historical record. More importantly, this growth was not driven by low prices to move volume, but by actually "capturing ground" in the global high-end market.
In Dubai, a dealer accustomed to luxury cars couldn't help but remark: "German brands can no longer compete with Chinese brands like Zeekr." He even placed an order for two new Zeekr cars himself.
Said from the mouth of a dealer in a luxury car gathering place, these words carry weight. Behind them lies a qualitative inflection point of China's automotive going global: from "being able to sell" to "selling at a high price", and then to "people chasing to buy."
01 The "Sweet Trouble" of an "Order Surge": Logistics Becomes the New BattlefieldThere are several details in Geely's May sales data that are particularly worth pondering.
First, it is not that one single car is hot, but "blooming at multiple points". In Mexico and Indonesia, the Geely EX2 took the sales crown for B-class hatchback new energy vehicles; in Australia, the Zeekr 7X directly surpassed the long-time chart-topping Tesla Model Y; Zeekr brand delivered 34,377 units in May, with the average transaction price increasing 52.4% year-on-year, surpassing BBA.
Second, "Order Surge" has become so severe that it requires emergency mobilization of logistics resources. Geely had to launch roll-on/roll-off ships, container ships, and international railway trains, forming a capacity layout of 4 major railway ports and 6 major seaports. The China-Europe Railway Express Geely special trains operate on a regular basis, shortening time by 40 days compared to sea transport.
This is actually a very "sweet" trouble. In the past we discussed Chinese cars going overseas, worrying that no one would buy; now Geely's problem is that too many people are buying, and they cannot be transported fast enough.
This reversal of supply and demand relationships is the signal truly worth attention. When your products need to "fight for capacity" overseas, it means the brand has crossed the most difficult "trust threshold."

Many people attribute Zeekr's success overseas simply to "high specs, low prices". But if you look closely at the data, you will find things are not that simple.
In Australia, the Zeekr 7X sold more expensive than the Tesla Model Y, yet sales surpassed it. In Dubai, the words dealers used to evaluate Zeekr were "entered the next stage", rather than "high cost-performance ratio".
The essential difference behind this lies in: Zeekr uses the logic of "technology defining luxury" to challenge BBA and Tesla's "brand premium."
Full stack 900V high-voltage platform, SEA-S super electric hybrid architecture... these hard-core technologies bring experience improvements that are cross-market. Whether you are a Middle Eastern billionaire or an Australian family, faster charging speed, longer range, smarter cockpit, these values are universal.
In other words, Zeekr did not play in the game rules favored by established car companies, but directly redefined a set of rules. When German brands were still struggling with "luxury feel", Chinese brands have already turned "tech feel" into a new luxury standard.

This time Geely's overseas order surge, there is another detail easily overlooked — it is not relying on a single brand fighting alone, but "one Geely" system under multi-brand collaboration.
Geely, Lynk & Co, Zeekr maintain their own tonality, but share R&D, channels, logistics, and after-sales systems. What does this mean? It means Geely overseas is not "testing the waters", but "taking root".
For example after-sales, Geely built a "Center Warehouse — Regional Warehouse — Terminal Outlet" three-level service system, launched ultra-long warranty, and established VOC User Voice systems with global unified response. This is no longer "selling car" thinking, but "user operation" thinking.
Again for example logistics, pre-layout of own roll-on/roll-off ships, regular China-Europe Railway Express special trains... these infrastructure investments, which look like costs, but facing today's 85,000 units monthly export volume, these forward-looking layouts became the hardest competitive barriers.
True globalization is not shipping domestic cars to foreign countries to sell, but establishing complete service capabilities and brand awareness locally. This point, Geely has already walked ahead of many Chinese car companies.

In the past we always said "China is a car big country, not a car strong country", because a true strong country must have pricing power and brand discourse power in the global market.
From Geely's May overseas performance, this turning point might come faster than we imagined. When a Chinese brand car can be actively "sought for purchase" by dealers in Dubai, can defeat Tesla head-on in Australia, can create historical sales highs in Mexico, Brazil — this is already not a victory of an enterprise, but a milestone of the entire Chinese automotive industry.
Of course, challenges are still ahead. EU and US market tariff barriers, fierce counterattack of local brands, user habit adaptation brought by cultural differences... These are hurdles that Geely and all Chinese car companies must cross.
But at least one point is clear: The "high-end game" of China's automotive going global is no longer a vision, but is currently ongoing.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


