

HomeBattery

Search History
Popular Searches
Dealer Login / Sign Up


In the first half of 2026, Sunwoda's power battery delivery volume and revenue both grew significantly. Power and storage batteries have already become the company's main source of revenue, surpassing consumer batteries. However, the subsidiary Sunwoda Power, which serves as the core carrier of the power battery business, is still losing money. Coupled with exchange losses in overseas markets, Sunwoda's non-recurring net profit for the first half of the year was less than 100 million yuan. The new growth engine has just arrived but is yet to exert force.
Written by | “Caijing” Special Contributors Yang Zheng, Zhao Cheng
As a globally leading consumer battery supplier, Sunwoda (300207.SZ)'s main growth engine is shifting towards power batteries.
Recently, Sunwoda Electronic Co., Ltd. disclosed its 2026 semi-annual report. The company achieved operating revenue of 38.179 billion yuan in the first half of the year, a year-on-year increase of 41.48%, setting a new record for the same period. Net profit was 468 million yuan, a year-on-year increase of 91.1%. Net profit attributable to shareholders of the listed company was 603 million yuan, a year-on-year decrease of 29.59%. The difference between the two comes from minority interest, specifically the loss of the non-wholly-owned subsidiary Sunwoda Power.
The change in performance mainly stems from two aspects: First, power battery deliveries surged 76.37% year-on-year to 28.36GWh, driving rapid expansion of revenue scale; Second, financial expenses surged 345.33% to 882 million yuan, mainly due to increased exchange losses.
From a business structure perspective, Sunwoda, which used to be mainly focused on the consumer battery business, has shifted its core growth engine to the power and energy storage sectors. Electric vehicle (power battery) business revenue reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin improving by 8.59 percentage points to 18.36%. Energy storage system business revenue reached 1.77 billion yuan, a year-on-year increase of 76.21%. In comparison, traditional advantageous consumer battery business revenue was 14.452 billion yuan, a year-on-year increase of 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. It is evident that Sunwoda's profit growth in the first half of this year mainly came from power batteries and energy storage systems, and the main growth engine has shifted to the power battery sector.
However, the contradiction lies here. Sunwoda Power Technology, the core of the power battery business, achieved operating revenue of 15.529 billion yuan in the first half of the year, a year-on-year increase of 90.1%, but still incurred a loss of 129 million yuan calculated on a net profit attributable to the parent company basis.
This means that although Sunwoda has found new growth momentum in the face of weak growth in the traditional consumer market, its profit quality still needs improvement. The real test may not lie in how many orders are won, but in how much money can be earned from those orders.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)

Power Battery Becomes the Main Engine of Revenue Growth
Power battery business is Sunwoda's main growth pole in the first half of the year. Financial reports show that electric vehicle battery revenue in the first half of the year reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin at 18.36%, nearly doubling the 9.77% of the same period last year. In the first half of 2026, the company's electric vehicle battery delivery volume reached 28.36GWh, a year-on-year increase of 76.37%.
The rapid growth in the power battery field comes from both internal and external dynamics. First, Sunwoda's leading position in the HEV (Hybrid Electric Vehicle) battery field. In 2018, Sunwoda passed the review of the Renault-Nissan Alliance and obtained HEV battery specifications. Products were equipped on models like Sylphy and X-Trail e-POWER, and entered the hybrid supply system of many main models of SAIC Volkswagen and FAW-Volkswagen. SNE Research data shows that in the second quarter of this year, Sunwoda's HEV lithium battery installed capacity ranked first globally.
European market demand for HEV batteries continues to drive related business growth. According to official data released by the European Automobile Manufacturers Association (ACEA), the market share of HEV in new car registrations in the EU was 37.3% in the first half of this year. This proportion ranked first among all power types and increased from 34.8% in the same period of 2025. Accordingly, Sunwoda planned a 15GWh power battery base in Hungary to meet the needs of large customers like Renault and Volkswagen. This factory will become the first wholly-owned battery factory built by a Chinese second-tier manufacturer in Europe.
The domestic market also shows a development trend favorable to Sunwoda. Many vehicle enterprises are striving to promote the diversification of power battery suppliers, providing entry space for second-tier manufacturers. Zhongshang Industry Research Institute data shows that CATL's market share in the power battery market showed a downward trend overall in the first half of the year, dropping from 49% in February to 42.7% in June. CITIC Securities analysis stated that against the backdrop of continuous intensification of competition in the automotive industry chain, the power battery supply system is gradually evolving from single supply to dual supply and multi-supply, and diversified procurement will become a long-term industry trend.
In the second half of 2025, Sunwoda and Li Auto established a power battery joint venture, Shandong Li Auto Battery Co., Ltd., in Shandong with equity ratios of 50% each. Sunwoda stated in its financial report that Shandong Li Auto is managed by the Sunwoda dispatched management team. In addition, according to local media reports, in Xiaomi Auto's independent sub-brand "Xuntian" series, Sunwada became the primary supplier with a supply proportion of 60%. Hongmeng Intelligent Mobility's Luxeed brand also officially introduced Sunwada, with two models Luxeed V9 and Luxeed R7 to be equipped with its ternary battery packs. At the same time, mainstream automakers such as SAIC Motor, Geely, and Wuling maintain close cooperation with Sunwada. The Phase I products of Sunwada's Yiwu base are directly supplying Volvo and Geely.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)
Cooperation with many vehicle manufacturers effectively pulled Sunwada's power battery market performance. According to Gasgoo Automotive Research Institute data, Sunwada's power battery installed capacity reached 7.24GWh in the first half of the year, with a market share of 3.1%. Installed capacity increased by 32% year-on-year, and market share increased by 0.6 percentage points compared to the full year of 2025.
Accordingly, the release of scale effects and improvement of profitability in the power battery field were expected. Western Securities research report pointed out that Sunwada's power battery is equipped with vehicle companies such as Li Auto, Dongfeng, Geely, Renault, and Nissan, and is expected to achieve the release of shipment scale effects and drive the company's annual performance to break even. Huachuang Securities also believes that the company's power battery and energy storage business volume drive high revenue growth, and profitability has been significantly repaired.

New Energy Storage Products Land, Second Curve Appears
The incremental business of energy storage is mentioned frequently by brokerage firms along with the power battery sector. Financial reports show that Sunwada's energy storage business revenue in the first half of the year was 1.77 billion yuan, a year-on-year increase of 76.21%, with delivery volume of 14.7GWh, a year-on-year increase of 64.98%.
The highlight of new products this year is large-capacity cells and AI backup power. In May, Sunwada put into production 588Ah energy storage cells, and officially released them in August. The cell energy density reached 417Wh/L. At 25 degrees Celsius and when the battery health drops to 70%, the cycle life can reach 10,000 times, theoretically matching the 20-year operation cycle of the power station. The full life cycle of a single 200MWh power station is expected to save 10 million kWh of power loss. Before this, its 684Ah stacked cells achieved mass production of millions of units. The two products are based on winding and stacking routes, forming a capacity ladder covering different system designs.
Financial reports show that Sunwada's energy storage system revenue mainly comes from overseas markets, with over 70% of overseas customers. In the field of home energy storage and industry and commerce, it has covered core markets in Europe, the Middle East, and South Asia. Europe is the main battlefield, becoming a major industrial and commercial energy storage brand in the German-speaking region, with core channel coverage exceeding 95%. In the field of network energy, with the high-speed expansion of the global AI (Artificial Intelligence) computing power industry, Sunwada's AIDC (Artificial Intelligence Data Center) energy storage business orders increased nearly 30 times year-on-year in the first half of the year. Relying on full-stack self-developed capabilities, its AIDC lithium battery solutions have been implemented in multiple key projects at home and abroad.
CICC research report stated that data center energy storage backup power demand is expanding, and Sunwada can provide a full-stack solution, so it is optimistic that energy storage business will become the company's second growth curve along with power battery business.

(Image Source: Yang Zheng)

Quality of New Engine Needs Improvement
In the first half of the year, consumer battery revenue, as Sunwada's traditional main business, reached 14.452 billion yuan, a year-on-year increase of only 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. This is not a problem unique to Sunwada. Brokerage firm research reports show that global smartphone shipments declined year-on-year in the first half of the year. Although high-end phone sales grew, it could not change the overall pressure on the sector, and the profit space for consumer cells was squeezed.
However, for Sunwada, consumer batteries are the company's main products sold overseas. With limited growth in the consumer battery business compared to the previous year, the urgency of the power and storage sector continuing to expand its overseas layout became more obvious.
Currently, Sunwada's overseas bases are still in the investment phase. Financial reports show that Sunwada's Thailand battery production base Phase I project officially started production in the first half of the year. Currently, the company still has Thailand Phase II project, Hungary power battery production base, and Vietnam consumer cell production base under construction in overseas. The cost of the investment phase is directly reflected in the financial end. In the first half of the year, exchange loss was 538 million yuan, among which the US dollar was hedged through hedging. Tether, Indian rupee and other currency hedging tools are limited. The financial expenses surged more than 300%, largely due to this.
Therefore, Sunwada's growth prospects in the second half of the year still need to return to the domestic power and storage market. Brokerage structure analysis believes that Sunwada's power and storage product deliveries for the second half of the year are fully booked. As raw material price adjustments gradually land and production line yield rates continue to improve, future profitability is expected to improve. According to Dongwu Securities' calculation, Sunwada's annual power and storage delivery volume will reach 90GWh, of which power batteries are 55GWh and energy storage systems are 35GWh. This means that the company has about 62GWh to be delivered in the second half of the year. If the profit per Wh improves by one cent, there will be an additional 620 million yuan of profit space, and vice versa. The company's profitability curve for the second half of the year and even the full year will largely be determined by the power and storage business, especially the profit quality of the power battery sector.
Looking at power battery performance horizontally within the industry, among the few power battery listed companies that recently disclosed financial reports, Sunwada has the advantages of fast growth rate and large gross margin improvement, as well as the disadvantage of not yet achieving profitability in the power sector. Besides CATL which leads in scale and profitability, Gotion High-Tech achieved 1.386 billion yuan of net profit attributable to the parent company in the first half of the year while achieving power battery installed capacity ranking in the top three. EVE Energy's net profit attributable to the parent company in the first half of the year was 3.3 billion yuan with 45.7 billion yuan in revenue, with a net profit increase of 105.66%, and power and storage entered a stable profitability zone. In comparison, although Sunwada's power battery business achieved high revenue growth and significant gross margin improvement, it still recorded a small overall loss in the first half of the year, and the overall net profit attributable to the parent company was not commensurate with its revenue scale of over 38 billion yuan.
Growth rate not losing to peers, profit quality still catching up, is Sunwada's true position in the power battery industry. In other words, the growth engine has completed the switch, but there is still distance from the new engine being in place to exert force on growth.
Currently, the lithium battery industry bids farewell to unbridled growth, entering a new phase of capacity clearance and quality-focused competition, where short-term involution and profit divergence have become industry norms. Against this backdrop, enterprises that adhere to long-term strategies, delve deep into technological innovation, and optimize operational efficiency and quality are the ones that can navigate industry fluctuations and achieve certain growth.
Recently, REPT Energy (00666.HK) disclosed its impressive interim performance for the first half of the year. Core indicators such as revenue, net profit, shipment volume, and cash flow all surged, with net profit even surpassing the level of the full year 2025. This high-scoring financial report that defies the trend upward is not supported by short-term industry dividends, but is the result of the company's deep dive into the track, adherence to long-termism, and continuous optimization of the operational system, fully demonstrating the enterprise's hard competitiveness and industry champion background in crossing the cycle.
The REPT Energy 2026 mid-year performance announcement shows that during the reporting period, the company achieved revenue of RMB 14.916 billion, a year-on-year increase of 57.2%; and achieved net profit of RMB 778 million, exceeding the net profit level of the full year 2025.
The company stated that the growth in operating performance mainly benefited from the continuous increase in power and energy storage battery shipments. In the first half of 2026, the company sold a total of 42.7 GWh of lithium battery products, a year-on-year increase of 31.8%. Among them, power battery shipments reached 15.5 GWh, a year-on-year increase of 14.8%, and power battery product revenue increased by 29.8% year-on-year; energy storage battery shipments reached 27.2 GWh, a year-on-year increase of 43.9%, and energy storage battery product revenue increased by 81.5% year-on-year. With the expansion of sales scale and improvement of capacity utilization, the effect of economies of scale is further highlighted.
In the first half of the year, the company's gross profit reached RMB 1.98 billion, a year-on-year increase of 138.8%; the net cash flow from operating activities reached RMB 3.46 billion, a significant increase compared to the same period last year, with profitability and operational quality improving simultaneously.
This impressive financial report is not an occasional result brought by short-term industry dividends, but the phased fruit borne by the long-termism management path after the company promoted "Strategic Focus, System Reshaping" in 2025. REPT Energy, through organizational integration and upgrade of business strategies, has completed the continuous optimization of business structure, walked out a path of resilient growth crossing the cycle, and interpreted the multi-dimensional "champion" core.
A Marathon Champion of Track Deep Dive: From Single-Point Leadership in Niche Scenarios to All-Scenario AdvancementIt is not difficult to see that the energy storage sector is becoming an important engine for REPT Energy's performance growth.
According to SPIR Research Institute data, REPT Energy's residential energy storage cell shipments remained in the first tier of the global top tier in the first half of 2026, ranking Top 1 in the competitiveness TOP list of global residential energy storage cell enterprises in H1 2026; commercial and industrial energy storage cell shipments also ranked among the global top tier, being rated as BloombergNEF Tier 1 energy storage supplier continuously for 11 quarters. At the same time, REPT Energy is not confined to existing achievements in niche fields, but is continuously pioneering innovation and advancing towards broader market space.

Note: SPIR Research Institute strives for objective and complete data and list information. If there is a deviation from official enterprise data, the official release by the manufacturer shall prevail. This content only represents SPIR research views, does not constitute commercial endorsement or investment basis, and SPIR reserves the right of final interpretation and explanation.
Facing the AI computing power era AIDC full new energy demand, REPT Energy has advanced layout of Powtrix®6.9MWh energy storage system equipped with Wendin®648Ah cells. The product cycle life breaks through 10,000 times, and the system round-trip efficiency can reach 96%, effectively reducing the O&M costs of computing power projects; meanwhile, it launches Wendin®85Ah high-power lithium iron phosphate energy storage cells customized for AI data center pulse load scenarios. This product supports 10C continuous discharge, pulse cycle life exceeds 60,000 times, working temperature range covers 40°C to 65°C, and can calmly cope with instantaneous impact of computing power load, ensuring the stable operation of computing power facilities; in addition, it releases Wendin®320Ah sodium-ion battery, owning ultra-wide temperature range and high safety characteristics, adapting to power grid, commercial and industrial, extreme scenario energy storage needs, transforming the continuously accumulated technological R&D strength into fast response capability facing new tracks.

Performance in the market is particularly noteworthy. Entering 2026, REPT Energy's overseas market expansion continues to accelerate, with overseas orders landing at multiple points. In March 2026 at the Italian International Renewable Energy Expo, REPT Energy signed a future two-year combined 8.3 GWh energy storage supply agreement with 7 European partners; in June of the same year, at the Munich European Smart Energy Expo, the company reached GW-level framework cooperation with multiple European partners again, covering Germany, the Netherlands, Belgium, Austria, and multiple Eastern European countries, and released the Global Delivery Assurance System on site, outputting the "80% global unified standards + 20% local flexible adaptation" export delivery model. At the same time, it reached 3 GWh supply cooperation with Energy Vault, covering the US, Australia, and European markets; joined hands with Hanwa to layout the Japanese market, delivering over 1 GWh of energy storage systems in two years.
Currently, cooperation results have been realized. In Nitta City, Tochigi Prefecture, Japan, a 1.99MW/8.35MWh independent grid-side energy storage project has completed grid connection and operation, providing local power grid frequency regulation, power quality optimization, and BCP emergency backup power. In addition, the Indonesia 8 GWh overseas manufacturing base has started production, achieving local delivery, the proportion of overseas business continues to rise, and the global layout is gradually deepened.

In the power sector, REPT Energy's differentiated advantages gradually stand out.
During the reporting period, REPT Energy's power battery installation volume ranked sixth in the country, and monthly installation volume in June entered the global top ten. According to the latest industry statistics data, in the first half of 2026, REPT Energy's new energy heavy-duty truck power battery cumulative installation volume reached 3.33 GWh, a year-on-year increase of 188.0%, far exceeding the 90.8% industry average level.
REPT Energy continues to polish Chenxing S Series, Chenxing D800 Pro scenario-based customized products, digging deep into commercial vehicles, new energy heavy trucks, mining trucks and other vertical tracks. Among them, Chenxing D800 Pro achieves system weight reduction of 700kg on the premise of large capacity, supports 1.3MW high-power fast charging, calculated to help heavy truck users increase about 160,000 yuan in operating income in 5 years; as the exclusive power supplier, the company provides battery solutions for Huaneng Yimin Open-Pit Mine 100 90-ton unmanned electric mining trucks, achieving stable operation at -40°C.
In the passenger car sector, facing plug-in hybrid, range-extended, and pure electric passenger car markets, Wendin® Hybrid Charging 4C Ultra-fast Charging Cell and supporting systems are launched, supporting average 4C, peak 6C fast charging. 10%80% energy replenishment can be completed in 10 minutes, working temperature range covers 40°C to 60°C, cycle life exceeds 4,500 times, system volume utilization reaches 70%, possessing zero thermal runaway safety characteristics, and has entered the supply chain of multiple mainstream automakers, adapting to urban commute, long-distance travel, and other diverse home travel scenarios; facing next-generation passenger cars, Wendin® Solid-Liquid Mixed Manganese Battery is launched, balancing high safety, low cost, and wide temperature performance, achieving 800 km range under whole vehicle conditions.

Not only that, REPT Energy further extends scenario-based power capabilities outward, laying out construction machinery, electric vessels, low-altitude aircraft (eVTOL) and other multi-innovative power fields. Facing forklifts, loaders, aerial work platforms and other construction machinery, high protection, long cycle special battery solutions are developed, adapting to high-frequency heavy load, bumpy and harsh operating environments at construction sites; in ship power, marine battery systems passing China Classification Society (CCS) certification are launched. Products have landed on Wenzhou Oujiang Asian Games Sightseeing Boat, Fujian Ningde Port 5,400 horsepower port tugboat, Beijing-Hangzhou Grand Canal 2,000-ton class cargo ship and other projects, meeting requirements for inland and coastal shipping salt spray, high humidity complex environments. In the low-altitude economy track aspect, relying on Wendin® Solid-Liquid Mixed High-Nickel battery technology, eVTOL aviation-grade cells are developed. Energy density can reach 375Wh/kg, supporting 15C peak discharge, working temperature range covers 40°C to 70°C, and strategic cooperation is reached with Uflytech, providing high-reliability power solutions for electric vertical takeoff and landing aircraft. Multi-dimensional scenario-based technology accumulation creates a differentiated growth curve.

Facing the industry's low-price involution and the common situation of swapping profit for scale, REPT Energy adheres to commercial underlying logic, abandoning disorderly vicious competition. Through pre-screening customers and risk control, building a raw material price linkage mechanism, it actively abandons low gross margin and high-risk orders.
This strategy implementation results are significant. Against the backdrop of the industry's overall capacity utilization rate declining, the company maintains high capacity utilization rate, order structure continues to tilt towards high-value overseas energy storage and core power customers, achieving two-way parallel of scale expansion and profit growth. In the first half of 2026, net profit surpassed 2025 full year, verifying the development concept that "long-term rational management is far more vital than short-term scale expansion".

Beyond commercial growth, REPT Energy synchronously deepens ESG and sustainable development construction, practicing Reliable, Environmental, Pioneering, Talented corporate concepts. Wenzhou, Jiashan, Liuzhou bases have been awarded National Green Factories. All operating bases have obtained ISO14001 environmental management system certification, carbon emission intensity per unit output decreased by 39.53% year-on-year. The company jointly pushes battery passport pilot with TÜV Rheinland, Circulor, completed pilot verification with Powtrix®2.0 energy storage system, achieving full lifecycle data traceability such as carbon footprint, raw material tracing, and building out overseas compliance capabilities.
As a member of the UN Global Compact, REPT Energy first rating won CDP Climate B Grade, Wind ESG A Grade, received multiple authoritative certifications for sustainable development, building solid confidence for enterprises to withstand industry fluctuations.
People-Oriented Growth Champion: Making Human Creativity the Core Value"Without people's sustainability, there is no corporate sustainability." REPT Energy believes that technological progress ultimately relies on people. AI can assist efficiency improvement, but the enterprise's endless innovation vitality comes from the creativity and continuous investment of every employee.
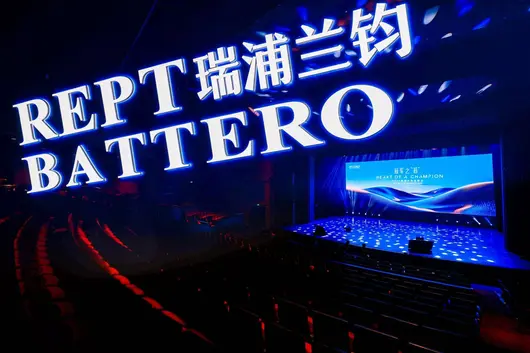
In April 2026, the company officially released the corporate culture system, establishing "Healthier, Happier, Wealthier" core value pursuit, incorporating employee growth and sense of gain into the enterprise's long-term development goals, advocating building a cultural ecology of "Shared Destiny, Symbiotic Value, Same Frequency Development". At the August 8 "Champion's Heart · Dream Time" brand day event, REPT Energy joined hands with Dream Ambassador Liu Hao, with the story of the struggle to chase musical dreams, echoing the team spirit of R&D breakthrough, operational efficiency improvement, and production delivery guarantee, achieving resonance between enterprise core and individual dream spirit.

Overall, the impressive performance of the first half of 2026 is the concentrated realization of REPT Energy's strategic determination, technical strength, operational capability and corporate culture. In the current context of deep reshuffling of the lithium battery industry and high-quality development becoming the main melody, the company relies on full-scenario track layout, rational and steady operating strategy, continuous iterative technological innovation, and people-oriented development concept to build a deep enterprise barrier.
Based on the present and looking far into the future, with the continued landing of energy storage global layout, the continuous strengthening of power battery differentiated advantages, and emerging tracks gradually scaling up, REPT Energy's long-term value is expected to continue to be released, will continue to lead the industry with a steady growth posture, and write a new model for the long-term development of lithium battery enterprises.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


