

HomePower

Search History
Popular Searches
Dealer Login / Sign Up
In the last quarter of fiscal 2026, Infineon's automotive revenue was €2.131 billion, €394 million more than power systems. In the line for segment profit, the order changed. Automotive earned €469 million, power systems earned €523 million.
As of the end of September 2026, Infineon's annual revenue was €16.353 billion, up approximately 12% year-on-year. Operating profit was €2.214 billion, up 46%, and net profit was €1.512 billion, up 49%. Revenue in the last three months reached a record €4.706 billion, €534 million more than the previous quarter. Gross profit increased by €264 million in the same period, while R&D expenses remained roughly flat compared to the previous quarter. By the end of the fiscal year, Infineon was able to support more sales with similar quarterly R&D spending. Annual R&D expenses still reached €2.583 billion, exceeding 15% of revenue.

To see where these profits came from, one needs to turn to the second half of the financial report. Infineon adjusted its organizational structure in July. According to restated data, automotive annual revenue was €7.765 billion, accounting for nearly half of the group, and remains the business ranked first in both revenue and segment profit. Power system revenue was €5.434 billion, of which €1.295 billion was the increase over the previous year, accounting for about 77% of the group's annual revenue increment. Profits were more concentrated. Power system segment profit increased by €653 million, while the group's total segment profit increased by only €663 million. Edge system revenue grew 2% in the same period, segment profit declined 8%, and the three departments had quite different years.
The contribution of data centers can be calculated more finely. Infineon's investor materials for the same period gave an annual data center power supply revenue of about €2.2 billion, of which AI data centers contributed about €1.7 billion, and traditional data centers about €0.5 billion. The expectation for fiscal 2027 is close to €4 billion. Based on this calculation, the sales increase needed for data center power supply alone in the new fiscal year is equivalent to the €1.691 billion increase from all Infineon businesses combined in the past year. Power systems also engage in business such as industry and power grids. The segment profit increment involves multiple product categories. The financial report does not further break down how much the data center power supply earned separately.

The automotive business grew 5% this year, with the annual segment profit margin dropping slightly from 20.4% to 20.0%. Recovery is mainly reflected at the end of the fiscal year, where the Q4 profit margin returned to 22.0% from 18.1% in the previous quarter. Infineon's revenue growth expectation for the next fiscal year is in the middle teens.Estimating with 15%, this is equivalent to adding about €1.16 billion on top of the €7.765 billion basis. To achieve such an increment, besides waiting for existing models to increase production, one must strive for components that were previously supplied by others on each car.
The $2.5 billion acquisition of Marvell's automotive Ethernet business acquired exactly such a position. Originally scattered control functions across the vehicle body are gradually being consolidated into zone controllers and central computers. Control boxes can be reduced, but the data that needs to be transmitted between cameras, sensors, and actuators is increasing. Infineon's original microcontrollers are responsible for executing commands, while acquired switch chips, transceivers, and bridges are responsible for connecting the in-vehicle network. In the past, if a new car selected Infineon's control chips, the network interface might still be supplied by another vendor. Now, the two types of products can be delivered together to the automotive company's design table.
Infineon estimates in investor materials that on a software-defined car adopting a layered electronics and electrical architecture, the potential bill of materials value of its own products on devices such as computing, Ethernet, analog, and storage is approximately $500.The word "potential" is very important. The number of components drawn in the reference solution versus the number of components ultimately kept in the procurement contract is separated by platform selection, configurations of vehicles at different price points, and actual sales volume. Whether the $2.5 billion acquisition was worthwhile ultimately depends on how many automotive projects also adopt the supporting network chips when using Infineon microcontrollers.

There are similar opportunities in the electric drive system, though car manufacturers calculate a different equation. When Rivian selected traction inverter power modules for the R2 platform, both silicon and silicon carbide entered the supply plan, coming from Infineon's same HybridPACKDriveG2 product family, the same module platform, with different voltage levels.
The list also includes AURIX microcontrollers and power management chips. The module is responsible for converting the battery's direct current to the alternating current required by the drive motor. The control chip decides how to drive the module, and the power management chip supplies power to the control circuit. Even if different configurations select different power modules, the supporting control and power devices still have the opportunity to remain on the same platform.
The selection of "silicon and silicon carbide simultaneously" was a cost compromise in 2023, but now it is already a standard approach. Silicon carbide is long ago no longer exclusive to high-spec: 6-inch conductive substrates fell from the 10,000 yuan level in 2022 to below 2,000 yuan in 2025; the average price of 6-inch substrates from SINOCERA fell 64.5% over two years; the average price of hybrid silicon carbide modules also decreased slightly. The price war bottomed out in 2025, and in 2026 6-inch substrates rebounded significantly, 8-inch substrates stopped falling and stabilized—the premise of "wait until silicon carbide is cheaper before getting on the car" itself is no longer valid.
Car manufacturers currently calculate not "whether to use silicon carbide", but "where to use it and how much": The main drive of 800V platforms almost defaults to silicon carbide; in dual-motor vehicles, the drive axis mainly relied on for daily driving uses all-carbon or hybrid-carbon modules to reduce conversion loss, while the other axis mainly supplements peak power during acceleration using lower-cost silicon-based IGBTs, which is equally valid from an engineering perspective. The usage time and working load of the two axes differ; installing the same high-efficiency device in different positions yields different range gains. The hybrid-carbon module is right in the middle – SiC chips account for about 40% of material costs. By making concessions on efficiency and cost, solutions that were originally valid only for vehicles above 300,000 yuan are now affordable for volume-selling vehicles at the 200,000 yuan level.
For Infineon, the true meaning of this calculation is not betting on silicon carbide penetration rate, but "no matter how the car company finally chooses, the components come from the same family". All-carbon silicon, hybrid-carbon, and pure silicon three solutions can all be covered by HybridPACKDriveG2. AURIX and power management chips follow up. Once the platform is set, subsequent model configuration changes make it difficult to switch suppliers. The cost is that silicon carbide price reductions also press down on unit prices and gross margins – the automotive segment profit margin dropped slightly from 20.4% to 20.0%, and one reason lies here. Own wafer foundry, 8-inch substrate supply, and 12-inch process validation are the trump cards used to keep costs in check.
02. 12-Inch is the Next Generation, 8-Inch is This GenerationOn October 15, 2026, Infineon signed a multi-year silicon carbide substrate supply agreement with Wolfspeed, advancing the existing cooperation from 150mm to 200mm, which is from 6-inch to 8-inch.Less than a month later, on November 9, Infineon also announced that it manufactured working power devices using 300mm, that is, 12-inch silicon carbide wafers in Villach, Austria.The two news items were 25 days apart. On one side, they were validating next-generation manufacturing processes; on the other side, they were preparing materials for commercial production at bases such as Kulim, Malaysia.
The diameter increased from 200mm to 300mm, and the wafer area expanded to 2.25 times the original. According to Infineon's estimate, the number of chips that can be arranged on one wafer is approximately 2.3 times the original. What truly determines automotive chip pricing is, after a batch of wafers are processed, how many chips meet voltage, resistance, and other specifications, and how many can be stably produced in the next batch at similar costs. The factory can produce functional devices on the first large wafer, but still needs batch after batch of production data to calculate the price applicable for long-term contracts.

A hypothetical calculation shows the difference. If the total cost of processing one large wafer is twice the original, and the number of qualified chips reaches 2.3 times the original, the front-end manufacturing cost per chip decreases by approximately 13%. If the initial yield is relatively low and qualified chips only increase to 1.8 times the original, the cost per chip would instead rise by about 11%. This set of numbers is just an example; Infineon has not disclosed the actual cost per chip for 12-inch silicon carbide. For car companies requiring stable multi-year supply, yield records of mass production processes, certification progress, and substrate supply capabilities all have tangible procurement value.
Additionally, Infineon validated the cold cleaving slicing process on 300mm silicon carbide ingots.Traditional wire saw cutting loses some material in the saw kerf. Cold cleaving aims to reduce loss, shorten processing time, and allow extracting a few more wafers from the same ingot. Expanding wafer diameter strives to make more chips per wafer. Improving the slicing process strives to produce more wafers per ingot.
03. Factory Building Completed, When Will the Next Equipment Be Moved InInfineon's continuing operations brought €4.137 billion in operating cash flow in fiscal 2026, €959 million more than the previous year. The change in free cash flow was larger, shifting from negative €1.051 billion to positive €993 million, improving €2.044 billion in one year. Between these two figures lies the impact of acquisitions on cash. According to Infineon's calculation standards, free cash flow includes cash inflows and outflows from purchasing and selling businesses. Net spending on major M&A this fiscal year decreased by €1.633 billion compared to the previous year, accounting for about 80% of the free cash flow improvement. Last fiscal year, a large sum of cash was spent to purchase the automotive Ethernet business; the returns from the product portfolio will only be visible after automotive projects gradually reach mass production.
Excluding the impact of major M&A and net investment in large frontend plants, adjusted free cash flow was €1.925 billion, up approximately 7% year-on-year, with the proportion of revenue dropping from 12.3% to 11.8%. By the end of September, net debt was €4.713 billion, essentially flat compared to a year ago. Next, Infineon needs to allocate €3 billion to €3.5 billion in investment for fiscal 2027, while full-year depreciation and amortization are expected to rise from €1.896 billion to about €2.2 billion. The timing of new equipment entering the factory and being put into use now directly affects cash expenditures and profits.
Several factories are at different stages. Dresden SmartPowerFab, with a total investment scale of €5 billion, was already commissioned in July 2026. Next, it needs to configure equipment for the fourth production plant and increase output. Kulim continues to expand silicon carbide capacity, with 8-inch substrates already having multi-year supply arrangements. Villach, besides validating 12-inch silicon carbide, also needs to advance 300mm gallium nitride production within existing clean rooms, planning to cumulatively invest about €1.1 billion by 2034, starting production no later than the end of 2027. Writing these projects broadly as "capacity expansion" easily causes one to miss the time difference. Factory unveilings, equipment commissions, process validations, and customer bulk pickups each have their own dates.

Infineon set the fiscal 2027 revenue target at about €20 billion. Compared to the just concluded fiscal year, it needs to sell an additional €3.65 billion. If data center power supply increases from €2.2 billion to close to €4 billion, it can roughly contribute half of the increment; automotive is an important source for the remaining increment. Equipment entering the factory early gives the capacity to take orders when customers increase production, though it may also bear idle costs for a few quarters first. Equipment entering the factory late means spending less cash in the short term, but once the vehicle model validation and mass production window is missed, making up capacity might not be in time.

Automotive remains Infineon's basic foundation, determining the company's downside; power systems are the profit variable of this year. The €653 million increment almost supported the growth of €663 million in the group's total segment profit. However, the €3.65 billion for fiscal 2027 will not automatically be realized: Data center power supply going from €2.2 billion to €4 billion is the half that can be clearly calculated on the books; the €1.16 billion growth for automotive, however, remains questionable.
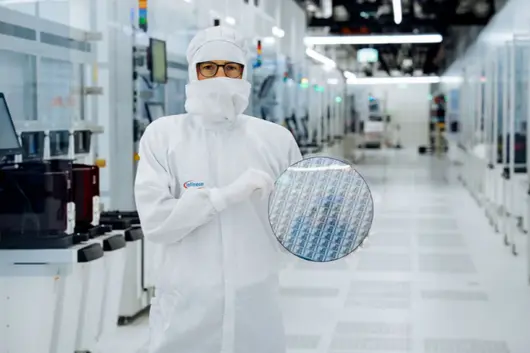
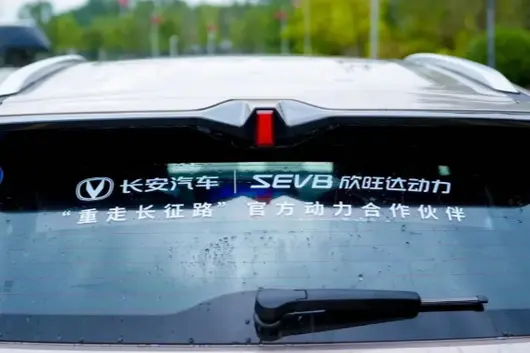
In October 1936, the three main forces of the Red Army converged, marking the successful conclusion of the Long March. 90 years later, in the "Re-walking the Long March" event hosted by People's Daily New Media, Changan CS55 Blue Whale Super Engine Hybrid and Eado Blue Whale Super Engine Hybrid, equipped with Sunwoda Power battery, set off with the team. They traveled from Jiangxi through Guangxi, Guizhou, Yunnan, Sichuan, Ningxia, Gansu, Shaanxi, 8 provinces/regions, covering nearly 8,000 kilometers. The wheels retraced the path of our ancestors, but this time there was another silent yet critical "companion" in the fleet — the battery. 8,000 kilometers, what does it mean for a power battery equipped in a new energy vehicle? It is continuous high-altitude climbing, frequent long downhill sections, high temperatures and sudden rain, temperature control and range tests under severe altitude fluctuations, all of which must be answered under complex operating conditions. The journey ended, the fleet completed the crossing, the battery performed steadily throughout. This is almost the most real, most severe "road test" a power battery could encounter, and the one submitting the answer sheet is Sunwoda Power, one of China's four "Global Tier 1 Power Battery Manufacturers". For history, this is a tribute-style revisit; for the industry, this is more like a field inspection carried out in real road conditions.

Use long-distance treks to verify laboratory parameters
The Red Army measured this road with their feet, while today people use driving "Re-walking the Long March" to remember the path taken. Although the route changed slightly, the harshness of the geographical environment has not changed: winding roads on the Yunnan-Guizhou Plateau, high altitudes in western Sichuan, gullies of the Liupan Mountain and Loess Plateau, almost concentrating the working conditions most "feared" by electric vehicles on the same road. Altitude difference, day-night temperature differences, and continuous slopes, harsh conditions that are difficult to assemble in a single test, are completely connected on this Long March road. What is even more rare is that running on this road is not a laboratory prototype, but mass-produced products equipped in batches. Precisely for this reason, the full-process stability of Sunwoda Power battery carries more weight. In the nearly 8,000-kilometer long-distance trek, battery charging and discharging, temperature control, consistency, etc., all withstood the test. For batteries, the hardest part is not a certain extreme moment, but making every ordinary moment on the road reliable. Having the courage to verify laboratory data with a long-distance trek full of extreme operating conditions is itself the foundation of the enterprise for its products.
Behind stability lies invisible "hard skills"
The two models, Changan CS55 Blue Whale Super Engine Hybrid and Eado Blue Whale Super Engine Hybrid, which "Re-walking the Long March" with the team this time, are both equipped with Sunwoda Power battery. This enterprise, integrating cells, modules, BMS and PACK production, sales, and R&D, has technical tags revolving around four words for a long time: Super Fast Charging, Super Safety, Super Durability, Super Anti-freezing. Abstract tags, when put on "Re-walking the Long March", get specific footnotes: Can it start smoothly under low temperatures, is temperature control reliable during continuous climbing, is performance the same as new after repeated charge-discharge. It is understood that Sunwoda Power HEV batteries can achieve -30°C super-low temperature cold start, 10 years 300,000 kilometers life, can also achieve 70C pulse discharge, super 3 times national standard bottom protection, cumulative delivery has broken through 1 million units, relying on Postdoctoral Research Workstation, Guangdong Province Fast Charging Power Battery Key Laboratory and other platforms for continuous accumulation. While HEV and pure electric tracks are laid out in parallel, the enterprise has also reserved next-generation technologies such as solid-state batteries and sodium-ion batteries. Technical leadership has never been just about constantly refreshing parameters on the stage, but more about throwing parameters into real complex road conditions to see if they "tell the truth".
The "New Long March" of power batteries relies on down-to-earth work
Pulling the eyes away from this road, Sunwoda's growth trajectory itself is like a "Long March": from 1997 starting with consumer batteries, to 2014 laying out power batteries; from supplying Renault-Nissan fixed points, to entering supply chains of mainstream car companies such as Li Auto, Chery, GAC, SAIC, to HEV hybrid batteries ranking first in Chinese installations for 5 consecutive years, and topping global installation volume in Q2 2026. Its production bases were built from Huizhou, Nanjing in China all the way to Hungary, Morocco, Thailand, and marketing agencies were established in North America, Europe, Asia, sending Chinese batteries to global car companies' production lines. From power batteries to energy storage systems, Sunwoda Power's business map is also continuously expanding. Every step is not easy, but every step counts. "Fear no hardships, down-to-earth, forge ahead", these 12 words in the context of new energy vehicle industry are exactly the daily life of battery manufacturers: not chasing wind tunnels, not shouting slogans, making the reliability of a battery ultimate, letting new energy vehicles run further and more stably. 90 years later "Re-walking the Long March", the significance is far more than "walking it again". When the fleet equipped with Sunwoda Power battery drives nearly 8,000 kilometers, it completes both a tribute to history and an answer sheet facing the future. The confidence of China's new energy vehicle industry is accumulated by countless down-to-earth links. This road, back then, was opened by the will of ancestors; today, it is paved step by step by the industry using technology. The road ahead is still long, but every step counts. This is also the vivid landing of the Long March spirit in the new energy vehicle industry.
【CNMO Tech News】 On July 6, CNMO Tech learned from TianyanCha App that Sunwoda Power Technology Co., Ltd. (hereinafter referred to as "Sunwoda Power") registered capital increased from approximately 13.2 billion to approximately 14.09 billion yuan. The completion of this industrial and commercial change marks that the company's previously disclosed C-round capital increase and share expansion plan has officially landed.

Sunwoda
According to a previous announcement by Sunwoda (300207), Sunwoda Power introduced 13 investors, including Gongrong Jintou No. 2, Yuanzhi Gongrong, Agricultural Bank of China Investment, China Post Investment, Uwin Laser, and Winmate Technology, through capital increase and share expansion. The total investment amount was approximately 1.68 billion yuan, subscribing to new registered capital of approximately 887 million yuan, corresponding to a combined 6.3% shareholding after the capital increase. This round of investors includes financial capital from state-owned major banks, multi-level local state-owned assets from provinces and cities, listed leaders of the lithium battery industry chain, and professional financial institutions, forming a diversified shareholder structure. After the capital increase, the shareholding ratio of Sunwoda Hui Zhou New Energy Co., Ltd. decreased from 29% to 27.18%. Sunwoda still maintains control over the operation and management activities of Sunwoda Power, and Sunwoda Power remains a subsidiary within the scope of consolidated financial statements.

Sunwoda Power
It is worth noting that the total equity value of Sunwoda Power before this round of capital increase and share expansion was determined to be 25 billion yuan, showing a gap compared to the previous round valuation of approximately 36.4 billion yuan. According to the announcement, the decline in valuation was mainly affected by the capital market situation and the operating situation of the subsidiary. In recent years, Sunwoda Power has been in a strategic investment period, with large-scale capacity ramp-up and R&D investment, continuously operating at a loss. In fiscal year 2025, Sunwoda Power realized operating revenue of approximately 20.093 billion yuan, with a net profit loss of approximately 3.169 billion yuan; in Q1 2026, operating revenue was approximately 6.125 billion yuan, net profit was approximately 13.0452 million yuan, achieving a quarterly turnaround from loss to profit.

Sunwoda Battery
It is reported that Sunwoda Power is the core platform for Sunwoda's electric vehicle business. In the HEV hybrid battery field, Sunwoda has achieved the number one shipment volume in China for five consecutive years, topping the global ranking in the first quarter of 2026, with cumulative global deliveries exceeding 3 million battery packs. The company has deeply cooperated with international brands such as the Renault-Nissan Alliance and Volkswagen. In terms of global layout, Sunwoda has established production bases in countries such as Vietnam, Thailand, India, Morocco, and Hungary.
Leading enterprise in the global power sports industry, CFMOTO, recently held the CFMOTO EXPERIENCE 2026 event (CFMOTO EXPERIENCE 2026) at its China headquarters, successfully receiving international media representatives from more than 29 countries and regions, and with "Global Layout, Intelligent Innovation, Ride the Future" (LIVE THE TECH・RIDE THE FUTURE) as the theme, comprehensively demonstrated to them the brand strategy, technology R&D, design, production, race operation and other diverse capabilities driving rapid enterprise development and global layout.

Themed Poster Welcomes Global Media
CFMOTO is based in China, and in recent years has been advancing on multiple fronts for the global market and developing rapidly. Its business has covered more than 100 countries and regions worldwide, and through continuous technology investment, manufacturing upgrades and motorsports operation, it has cultivated deeply, constantly expanding its business footprint and market influence around the world. The company currently relies on more than 9,000 dealers to deeply serve global riding enthusiasts in different regions. The product matrix covers motorcycles, all-terrain vehicles and electric mobility solutions, etc., with differentiated and high-quality product services to deeply adapt to different market needs and diverse riding culture demands.
Lai Minjie, Chairman and CEO of CFMOTO, stated during the reception of the visiting delegation: "We hope this visit will allow friends to experience CFMOTO firsthand. By communicating with our team and visiting relevant enterprise facilities and investments, you can experience and gain a deep understanding of our enterprise's characteristics and brand commitment."

CFMOTO Chairman and CEO Lai Minjie Delivers Welcome Speech
Ferdinand Klauser, Chief Brand Officer of CFMOTO, stated: "Our vision is very clear: to strive to build a high-end global power sports brand. Of course, for CFMOTO, globalization does not only refer to selling products to all parts of the world, but is also reflected in the enterprise's in-depth operational models in global markets. Therefore, we also hope to use this event to allow everyone to understand the enterprise's comprehensive strength and development commitment more comprehensively, in-depth, and vividly through main media friends in global markets."

CFMOTO Chief Brand Officer Ferdinand Klauser Speech
To better respond to global market demand, shorten delivery cycles and improve supply chain resilience, CFMOTO has laid out 5 major modern manufacturing bases in Hangzhou, Jiaxing, Chongqing in China, as well as Thailand and Mexico, forming a global production network with multi-base collaboration, with a total planned annual capacity of over 4 million units. Different bases implement CFMOTO's unified manufacturing standards and unified quality control system.
At this event, CFMOTO introduced the newly completed CFMOTO Future Factory (CFMOTO NexFactory) in Jiaxing. This is a two-wheeled vehicle integrated production base serving the global market, and also the core carrier of the group's electrification and intelligence strategy, with a design annual capacity of 3 million units. The factory is equipped with automated, flexible modular production lines and intelligent assembly, testing and smart logistics systems. Both fuel and electric vehicle models can be fully self-made across the chain, and core processes are completely independent. Relying on the independent R&D capabilities of complete vehicles and core components, and linking Thailand and Mexico bases to form a global collaborative layout, relying on flexible production, digital tracing and continuous optimization systems, it delivers more reliable, green and intelligent Chinese intelligent two-wheeled products to the global market quickly. At the same time, besides the production network, the company has also established five core R&D centers and four design centers globally, constantly refining and improving product technology leadership and competitiveness with globally leading innovation capabilities and efficient collaborative capabilities.
During this event, international media representatives visited the technology R&D and core design institutions of CFMOTO located at the Hangzhou headquarters, to closely understand CFMOTO's complete vehicle development, simulation testing, software engineering, connected technology and product design processes and strength. At the same time, CFMOTO Industrial Design Institute (CFID) also seized this opportunity to open to the outside world for the first time, giving the media the opportunity to deeply understand and observe how the enterprise coordinates leading design resources in China, Europe and North America. During the CFID opening, CFMOTO used its leading 550CL-C model and GOES 700 concept car to very specifically and vividly demonstrate its unique "Form Follows the Wind (Form Follows the Wind)" design concept. At the same time, CFMOTO also exhibited the V4 SR-R prototype that just created a top speed of 315.82 km/h in China this year to international media for the first time, allowing everyone the opportunity to appreciate the results of China's independent technology innovation capability implementation.
In addition, motorcycle racing is also a core sector of CFMOTO's global technology and brand strategy. During the event, international media also conducted in-depth discussions with guests on topics in this field, and had the opportunity to communicate face-to-face with CFMOTO Global Brand Ambassador, Spanish legendary Enduro off-road rider and FIM Enduro World Champion, 2026 Red Bull Romania Enduro Ultimate Group Champion Mario Román (Mario Román).
For CFMOTO, racing is the strictest test field to verify technology and performance. The experience accumulated on the track is directly used for mass-produced vehicle development. Racing also consolidates brand reputation and deepens the bond between CFMOTO and riders. By cooperating with the Aspar team to compete in Moto2 and Moto3, CFMOTO made history in 2024 and swept the Moto3 rider, team and manufacturer three annual championships. This winning streak continued to 2026. CFMOTO Aspar team rider Máximo Quiles (Máximo Quiles) won the Moto3 World Championship this month, continuing the brand's excellent results in international competitions. CFMOTO's track strength is not limited to the MotoGP paddock. 675SR-R was selected for the 2027 FIM Women's Road Racing World Championship (WorldWCR) official racing, which is the first time a Chinese motorcycle manufacturer has become the designated supplier for a unified category event at the FIM World Championship level.

Yiche News Recently, CFMOTO Power (CFMOTO) launched the "2026 Decoding CFMOTO: Global Layout, Intelligent Creation and Driving Innovation" themed event (CFMOTO EXPERIENCE 2026) at its Hangzhou headquarters. International media from 29 countries and regions around the world gathered onsite to visit this leading Chinese power sports enterprise up close and comprehensively understand CFMOTO's global brand strategy, technology R&D, industrial design, intelligent manufacturing, and comprehensive strength in event operations.
CFMOTO Power's business now covers more than 100 countries and regions, relying on over 9,000 dealers to serve global riding enthusiasts. The product matrix includes motorcycles, ATVs, and electric mobility solutions, catering to the consumption needs of different regional markets and diverse riding cultures. The theme of this event is "LIVE THE TECH・RIDE THE FUTURE", fully demonstrating the confidence of Chinese motorcycle brands going global to overseas media.

CFMOTO Chairman and CEO Lai Minjie
At the event, CFMOTO Chairman and CEO Lai Minjie told the visiting media that he hoped that through site visits and face-to-face exchanges, global media could personally feel the corporate accumulation and brand commitment of CFMOTO Power.

CFMOTO Chief Brand Officer Ferdinand Klauser (Ferdinand Klauser)
CFMOTO Chief Brand Officer Ferdinand Klauser (Ferdinand Klauser) mentioned during the event that CFMOTO's goal is to build a high-end global power sports brand. Globalization does not equal simple product exports, but rather achieving in-depth localized operations. This event also hopes to use global media to convey CFMOTO's technical strength and development philosophy to users around the world.
To adapt to the global market, shorten delivery cycles, and strengthen supply chain risk resistance, CFMOTO has established five modern manufacturing bases across Hangzhou, Jiaxing, Chongqing in China, as well as Thailand and Mexico. The overall planned annual capacity breaks through 4 million units, and all bases implement unified manufacturing standards and quality control systems.

This event 重点 introduced the newly completed Jiaxing CFMOTO Future Factory (CFMOTO NexFactory), an integrated two-wheeled vehicle production base for the global market and the core carrier of the group's electrification and intelligence strategy, with a designed annual capacity of 3 million units. The factory is equipped with flexible modular production lines, intelligent assembly and testing, and a smart logistics system. Both fuel and electric vehicle models can be fully self-manufactured through the entire chain, with core processes independently controlled. The Jiaxing base links up with overseas factories in Thailand and Mexico, relying on digital traceability and a flexible production system to output high-quality and intelligent Chinese smart two-wheeled products to the world. On the R&D end, CFMOTO has layouted five global R&D centers and four design centers, continuously solidifying product technology competitiveness.
The media group also visited the R&D and design institutions at the Hangzhou headquarters on site, completely observing the full set of vehicle development processes including whole vehicle development, simulation testing, software engineering, and vehicle-Internet connectivity. CFMOTO Industrial Design Institute CFID was also publicly disclosed for the first time, integrating design resources from China, Europe, and North America. The "Form Follows the Wind" design concept was interpreted on-site using the 550CL‑C and GOES 700 concept cars; the V4 SR‑R prototype car, with a domestically tested maximum speed of 315.82km/h, was also exhibited to international media for the first time, intuitively demonstrating the top self-developed technology achievements of domestic motorcycles.
The track is also an important link in CFMOTO's global strategy. Racing cars are regarded as a strict technical test field, and technical experience accumulated on the track feeds back into civilian mass production models, further narrowing the distance between the brand and global riders. During the event, media exchanged with FIM Hard Enduro World Champion and CFMOTO Global Brand Ambassador Mario Román (Mario Román).
In the international motorcycle racing arena, CFMOTO has achieved remarkable results in recent years: in 2024, in partnership with the Aspar team, they swept the Moto3 Rider, Team, and Manufacturer Annual Championships; in the 2026 season, rider Maximino Quiles again won the Moto3 World Championship, continuing the winning streak. Not only that, the 675SR‑R will become the official racing car for the 2027 FIM Women's Road Racing World Championship (WorldWCR), and CFMOTO has also become the first domestic official supplier for FIM World Championship level unified group events, marking a new breakthrough for Chinese motorcycle brands in the international racing arena.
Finally Looking to the future, CFMOTO Power will continue to rely on the global manufacturing, R&D, and design network, continuously deepen technological innovation, and at the same time use racing as a nexus to continue expanding the influence of Chinese power sports brands in the global market, bringing more high-quality products to global riding enthusiasts.

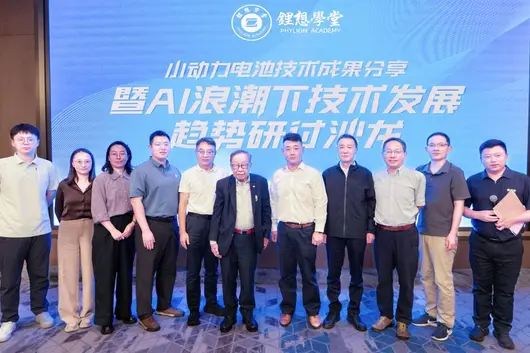
September 17, Chongqing. On the eve of the opening of the 24th China International Motorcycle Expo, Xingheng Power organized a gathering—a Seminar on Small Power Lithium Battery Technology Achievement Sharing and Technology Development Trends under the AI Wave. Academicians, experts from the Chinese Academy of Engineering, Fudan University, Sichuan University, Chongqing University, NUS Suzhou Research Institute, along with industry representatives, gathered together.
At first glance, it is a technical seminar; upon closer inspection, this is a collective disclosure of Chinese small power lithium batteries transitioning from “manufacturing-driven” to “intelligence-driven.”

Small Power, How Big of a Deed is It?
Two-wheelers are the most efficient short-distance travel mode. This is not sentiment, it is a necessity. The growth rates of domestic sales and exports of Chinese electric motorcycles continue to rise. Southeast Asia, Africa, Latin America, the demand certainty of these markets is extremely strong. Compared to fuel motorcycles, the Chinese electric two-wheeler industry has greater advantages in global expansion services—standardized service systems, mature supply chains, extreme cost-effectiveness, these are all core strengths.
And lithium batteries are the core supporting all this competitiveness.
Xingheng Power Chairman Feng Xiao said a sentence: “Small Power, Big Deeds.” This statement holds true. Xingheng’s lithium batteries have already entered Southeast Asia, Africa, and Latin America first, bringing high cost-performance Chinese lithium battery products to the “Belt and Road”沿线. This is not simple product export, it is a deep integration of “Chinese technology, local flavor” and “Chinese genes, local carriers”—To local, in local, for local.

Battery + AI, Not a Gimmick, But a Dimensional Upgrade
At the seminar, the density of technology sharing was very high, but the main thread was clear: battery technology itself is evolving, and AI is accelerating this process.
Xingheng CTO Wang Zhengwei presented the idea of “Source Improvement + System Enhancement”, the Manganese-based battery technology iteration path is clear—greater capacity, stronger power, lower cost, faster charging, higher intelligence and standardization. This is collaborative innovation from material genes to system levels.
Sichuan University Associate Professor Wang Caihong brought an interesting direction: embedding temperature-responsive materials into the battery system, letting the battery identify early overheating and respond actively. Battery safety changes from “external passive monitoring” to “intrinsic active response”, this is a paradigm-level leap.
How does AI land? Dr. He Peng from NUS Suzhou Research Institute showed how AI promotes material R&D from “experience-based trial and error” to “data-driven”. Fudan University Dr. Xu Zhengchuan proposed that AI is moving from content generation tools to agents for scientific discovery and engineering decision-making, future material screening and process optimization will greatly shorten the industrialization cycle.

Academicians’ Direction: Technology Ultimately Points to Humans
Chinese Academy of Engineering Academician Chen Qingquan’s sharing set the tone for this seminar. He said we are at the intersection node of the 3rd and 4th Industrial Revolutions, the Energy Revolution moves towards new energy, the Transportation Revolution moves towards electrification and intelligence, AI is the core engine. But he emphasized a key phrase: technology ultimately points to humans. Regardless of how materials and AI evolve, finally it must make batteries safer, more reliable, and economic.
He also mentioned “Three Aspects”: Look Forward, Look Backward, Look Downward. Forward-looking vision insights trends, historical experience avoids detours, practical implementation tests value. Dialectical innovative thinking coordinates development and security, present and long-term.

An Industry New Ecosystem is Taking Shape
The value of this seminar lies not in a single-point technology breakthrough, but in that it presents a trend: a new industry ecosystem of collaboration co-creation among universities, research institutions, and enterprises is accelerating formation.
Xingheng stated clearly: persist in the small power main channel, client needs-oriented, transform technical innovation into better products, this cannot be separated from the collaboration of industry, academia, and research. Industry collaboration, model innovation, co-promote new standards—let Chinese lithium batteries serve global users.

When battery technology innovation and AI paradigm changes collide in the same arena, the small power lithium battery industry is standing on a new starting point. Chinese lithium battery enterprises have already formed global leading advantages in technology accumulation and application scale. The next step is to transform this advantage into global market standards and service capabilities.
Small Power, Big Deeds. This is not a slogan, but a fact that is happening.


In the first half of 2026, Sunwoda's power battery delivery volume and revenue both grew significantly. Power and storage batteries have already become the company's main source of revenue, surpassing consumer batteries. However, the subsidiary Sunwoda Power, which serves as the core carrier of the power battery business, is still losing money. Coupled with exchange losses in overseas markets, Sunwoda's non-recurring net profit for the first half of the year was less than 100 million yuan. The new growth engine has just arrived but is yet to exert force.
Written by | “Caijing” Special Contributors Yang Zheng, Zhao Cheng
As a globally leading consumer battery supplier, Sunwoda (300207.SZ)'s main growth engine is shifting towards power batteries.
Recently, Sunwoda Electronic Co., Ltd. disclosed its 2026 semi-annual report. The company achieved operating revenue of 38.179 billion yuan in the first half of the year, a year-on-year increase of 41.48%, setting a new record for the same period. Net profit was 468 million yuan, a year-on-year increase of 91.1%. Net profit attributable to shareholders of the listed company was 603 million yuan, a year-on-year decrease of 29.59%. The difference between the two comes from minority interest, specifically the loss of the non-wholly-owned subsidiary Sunwoda Power.
The change in performance mainly stems from two aspects: First, power battery deliveries surged 76.37% year-on-year to 28.36GWh, driving rapid expansion of revenue scale; Second, financial expenses surged 345.33% to 882 million yuan, mainly due to increased exchange losses.
From a business structure perspective, Sunwoda, which used to be mainly focused on the consumer battery business, has shifted its core growth engine to the power and energy storage sectors. Electric vehicle (power battery) business revenue reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin improving by 8.59 percentage points to 18.36%. Energy storage system business revenue reached 1.77 billion yuan, a year-on-year increase of 76.21%. In comparison, traditional advantageous consumer battery business revenue was 14.452 billion yuan, a year-on-year increase of 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. It is evident that Sunwoda's profit growth in the first half of this year mainly came from power batteries and energy storage systems, and the main growth engine has shifted to the power battery sector.
However, the contradiction lies here. Sunwoda Power Technology, the core of the power battery business, achieved operating revenue of 15.529 billion yuan in the first half of the year, a year-on-year increase of 90.1%, but still incurred a loss of 129 million yuan calculated on a net profit attributable to the parent company basis.
This means that although Sunwoda has found new growth momentum in the face of weak growth in the traditional consumer market, its profit quality still needs improvement. The real test may not lie in how many orders are won, but in how much money can be earned from those orders.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)

Power Battery Becomes the Main Engine of Revenue Growth
Power battery business is Sunwoda's main growth pole in the first half of the year. Financial reports show that electric vehicle battery revenue in the first half of the year reached 14.134 billion yuan, a year-on-year increase of 85.87%, with gross margin at 18.36%, nearly doubling the 9.77% of the same period last year. In the first half of 2026, the company's electric vehicle battery delivery volume reached 28.36GWh, a year-on-year increase of 76.37%.
The rapid growth in the power battery field comes from both internal and external dynamics. First, Sunwoda's leading position in the HEV (Hybrid Electric Vehicle) battery field. In 2018, Sunwoda passed the review of the Renault-Nissan Alliance and obtained HEV battery specifications. Products were equipped on models like Sylphy and X-Trail e-POWER, and entered the hybrid supply system of many main models of SAIC Volkswagen and FAW-Volkswagen. SNE Research data shows that in the second quarter of this year, Sunwoda's HEV lithium battery installed capacity ranked first globally.
European market demand for HEV batteries continues to drive related business growth. According to official data released by the European Automobile Manufacturers Association (ACEA), the market share of HEV in new car registrations in the EU was 37.3% in the first half of this year. This proportion ranked first among all power types and increased from 34.8% in the same period of 2025. Accordingly, Sunwoda planned a 15GWh power battery base in Hungary to meet the needs of large customers like Renault and Volkswagen. This factory will become the first wholly-owned battery factory built by a Chinese second-tier manufacturer in Europe.
The domestic market also shows a development trend favorable to Sunwoda. Many vehicle enterprises are striving to promote the diversification of power battery suppliers, providing entry space for second-tier manufacturers. Zhongshang Industry Research Institute data shows that CATL's market share in the power battery market showed a downward trend overall in the first half of the year, dropping from 49% in February to 42.7% in June. CITIC Securities analysis stated that against the backdrop of continuous intensification of competition in the automotive industry chain, the power battery supply system is gradually evolving from single supply to dual supply and multi-supply, and diversified procurement will become a long-term industry trend.
In the second half of 2025, Sunwoda and Li Auto established a power battery joint venture, Shandong Li Auto Battery Co., Ltd., in Shandong with equity ratios of 50% each. Sunwoda stated in its financial report that Shandong Li Auto is managed by the Sunwoda dispatched management team. In addition, according to local media reports, in Xiaomi Auto's independent sub-brand "Xuntian" series, Sunwada became the primary supplier with a supply proportion of 60%. Hongmeng Intelligent Mobility's Luxeed brand also officially introduced Sunwada, with two models Luxeed V9 and Luxeed R7 to be equipped with its ternary battery packs. At the same time, mainstream automakers such as SAIC Motor, Geely, and Wuling maintain close cooperation with Sunwada. The Phase I products of Sunwada's Yiwu base are directly supplying Volvo and Geely.

(Chart: Yang Zheng | Data Source: Corporate Financial Report)
Cooperation with many vehicle manufacturers effectively pulled Sunwada's power battery market performance. According to Gasgoo Automotive Research Institute data, Sunwada's power battery installed capacity reached 7.24GWh in the first half of the year, with a market share of 3.1%. Installed capacity increased by 32% year-on-year, and market share increased by 0.6 percentage points compared to the full year of 2025.
Accordingly, the release of scale effects and improvement of profitability in the power battery field were expected. Western Securities research report pointed out that Sunwada's power battery is equipped with vehicle companies such as Li Auto, Dongfeng, Geely, Renault, and Nissan, and is expected to achieve the release of shipment scale effects and drive the company's annual performance to break even. Huachuang Securities also believes that the company's power battery and energy storage business volume drive high revenue growth, and profitability has been significantly repaired.

New Energy Storage Products Land, Second Curve Appears
The incremental business of energy storage is mentioned frequently by brokerage firms along with the power battery sector. Financial reports show that Sunwada's energy storage business revenue in the first half of the year was 1.77 billion yuan, a year-on-year increase of 76.21%, with delivery volume of 14.7GWh, a year-on-year increase of 64.98%.
The highlight of new products this year is large-capacity cells and AI backup power. In May, Sunwada put into production 588Ah energy storage cells, and officially released them in August. The cell energy density reached 417Wh/L. At 25 degrees Celsius and when the battery health drops to 70%, the cycle life can reach 10,000 times, theoretically matching the 20-year operation cycle of the power station. The full life cycle of a single 200MWh power station is expected to save 10 million kWh of power loss. Before this, its 684Ah stacked cells achieved mass production of millions of units. The two products are based on winding and stacking routes, forming a capacity ladder covering different system designs.
Financial reports show that Sunwada's energy storage system revenue mainly comes from overseas markets, with over 70% of overseas customers. In the field of home energy storage and industry and commerce, it has covered core markets in Europe, the Middle East, and South Asia. Europe is the main battlefield, becoming a major industrial and commercial energy storage brand in the German-speaking region, with core channel coverage exceeding 95%. In the field of network energy, with the high-speed expansion of the global AI (Artificial Intelligence) computing power industry, Sunwada's AIDC (Artificial Intelligence Data Center) energy storage business orders increased nearly 30 times year-on-year in the first half of the year. Relying on full-stack self-developed capabilities, its AIDC lithium battery solutions have been implemented in multiple key projects at home and abroad.
CICC research report stated that data center energy storage backup power demand is expanding, and Sunwada can provide a full-stack solution, so it is optimistic that energy storage business will become the company's second growth curve along with power battery business.

(Image Source: Yang Zheng)

Quality of New Engine Needs Improvement
In the first half of the year, consumer battery revenue, as Sunwada's traditional main business, reached 14.452 billion yuan, a year-on-year increase of only 4.04%, with gross margin declining by 4.95 percentage points to 14.68%. This is not a problem unique to Sunwada. Brokerage firm research reports show that global smartphone shipments declined year-on-year in the first half of the year. Although high-end phone sales grew, it could not change the overall pressure on the sector, and the profit space for consumer cells was squeezed.
However, for Sunwada, consumer batteries are the company's main products sold overseas. With limited growth in the consumer battery business compared to the previous year, the urgency of the power and storage sector continuing to expand its overseas layout became more obvious.
Currently, Sunwada's overseas bases are still in the investment phase. Financial reports show that Sunwada's Thailand battery production base Phase I project officially started production in the first half of the year. Currently, the company still has Thailand Phase II project, Hungary power battery production base, and Vietnam consumer cell production base under construction in overseas. The cost of the investment phase is directly reflected in the financial end. In the first half of the year, exchange loss was 538 million yuan, among which the US dollar was hedged through hedging. Tether, Indian rupee and other currency hedging tools are limited. The financial expenses surged more than 300%, largely due to this.
Therefore, Sunwada's growth prospects in the second half of the year still need to return to the domestic power and storage market. Brokerage structure analysis believes that Sunwada's power and storage product deliveries for the second half of the year are fully booked. As raw material price adjustments gradually land and production line yield rates continue to improve, future profitability is expected to improve. According to Dongwu Securities' calculation, Sunwada's annual power and storage delivery volume will reach 90GWh, of which power batteries are 55GWh and energy storage systems are 35GWh. This means that the company has about 62GWh to be delivered in the second half of the year. If the profit per Wh improves by one cent, there will be an additional 620 million yuan of profit space, and vice versa. The company's profitability curve for the second half of the year and even the full year will largely be determined by the power and storage business, especially the profit quality of the power battery sector.
Looking at power battery performance horizontally within the industry, among the few power battery listed companies that recently disclosed financial reports, Sunwada has the advantages of fast growth rate and large gross margin improvement, as well as the disadvantage of not yet achieving profitability in the power sector. Besides CATL which leads in scale and profitability, Gotion High-Tech achieved 1.386 billion yuan of net profit attributable to the parent company in the first half of the year while achieving power battery installed capacity ranking in the top three. EVE Energy's net profit attributable to the parent company in the first half of the year was 3.3 billion yuan with 45.7 billion yuan in revenue, with a net profit increase of 105.66%, and power and storage entered a stable profitability zone. In comparison, although Sunwada's power battery business achieved high revenue growth and significant gross margin improvement, it still recorded a small overall loss in the first half of the year, and the overall net profit attributable to the parent company was not commensurate with its revenue scale of over 38 billion yuan.
Growth rate not losing to peers, profit quality still catching up, is Sunwada's true position in the power battery industry. In other words, the growth engine has completed the switch, but there is still distance from the new engine being in place to exert force on growth.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


