

HomeToyota Corolla AE86

Search History
Popular Searches
Dealer Login / Sign Up

Momenta's listing is not only a critical moment for itself, but also a public defense for the entire autonomous driving and Physical AI industry.
Author | Intelligent Driving Network Ling Jiang Yu Lai
Editor | Langlang Mountain and Zhiming Mountain
After He Xiaopeng declared GX the first Physical AI car, and Li Xiang called the new L9 an Embodied AI flagship, Volkswagen suddenly realized that smart cars and autonomous driving are no longer the hot celebrities that make people excited and flocking in the capital market.
Yesterday was a sweetie, today is an old wife.
Momenta instantly abandoned the outdated concept of autonomous driving and, as the first Physical AI stock, encountered a surge in subscription in the capital market.

On July 8, Momenta officially listed on the HKEX, opening at 301 HKD, higher than the offer price of 295.6 HKD/share. The intraday high touched 314.80 HKD, with market cap breaking 70 billion HKD at one point, and fell back to around 299 HKD at the end of trading.

Due to the public offering of Momenta receiving 414 times excess subscription, its Green Shoe option will likely be fully exercised. This means it will issue about 22.93 million shares, with total raised funds reaching about 6.8 billion HKD, exceeding its initial estimate of 5.89 billion HKD by nearly 1 billion HKD.
One point the Momenta team is proud of is that it has received high favor from international capital. The international offering part received institutional orders exceeding 100 billion HKD, covering sovereign funds and long-term funds from 15 countries and regions.
Including Singapore Government Investment Corporation (GIC), Fidelity International, BlackRock Group, Franklin Templeton, Abu Dhabi Investment Authority (ADIA), Canada Pension Plan Investment Board (CPPIB), Temasek, Wellington, Schroders, and other global top institutions.
Before listing, the 14 cornerstone investors introduced by Momenta had a lineup that can be called luxurious, with subscription amounting to about 3 billion HKD, exceeding half of its total fundraising.
Such craziness, is this the craze triggered by the first Physical AI stock?
Obviously, it is not that simple.
01.
Cooling Intelligent Driving and Heating 'Physical AI'
A particularly dramatic aspect is that on July 8, five companies rang the bell at HKEX simultaneously, one of which was an autonomous driving company Yikong Smart Driving with a positioning close to Momenta, both are enterprises invested by NIO Capital.
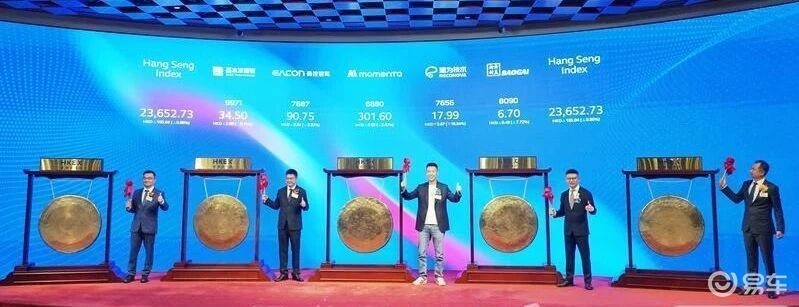
The two enterprises played different scripts during the IPO stage and the first day of listing.
Yikong Smart Driving faces mining area autonomous driving. Compared to Momenta, the scale is very small. Compared to Momenta's fixed price model, its offering interval was set at 81.16 to 87.92 HKD, but it ultimately also realized pricing at the upper limit.
Compared to Momenta's huge popularity, in the pre-market trading the night before listing, its average transaction price was 87.07 HKD. Not only was it lower than the offer price, but intraday it once fell nearly 20%, and the closing gain was only 4%, with volatility close to 25%, showing clear divergence between bulls and bears.
But after officially listing on July 8, compared to Momenta opening high but falling in the afternoon, where it once fell below the offer price, Yikong Smart Driving ultimately recorded a 9.99% increase over the offer price, with total market cap reaching 14.299 billion HKD.

Without the support of the Physical AI concept, both Yikong Smart Driving and Momenta failed to achieve profitability. Both are still deeply trapped in losses, with no clear profitability schedule yet. The capital market's enthusiasm and bearishness for the two companies both focus on the future.
Is the concept of autonomous driving really outdated?
In terms of financing amount, Momenta, holding the most mass production clients, did not exceed Pony.ai's 7.7 billion HKD financing when it IPOed on HKEX last year, but it was higher than Horizon Robotics which is布局ing both chips and algorithms.

But under the flood of AI, the stock prices of these listed intelligent driving companies have mostly halved compared to the offer price.
The decline in the heat of the intelligent driving concept in the capital market is also a fact.
But undeniably, what makes Momenta's future more tangible, and what has more imagination space is still its position established in the passenger vehicle market.
02.
The Terrifying 70% Gross Margin
The 71.6% gross margin announced in the prospectus released by Momenta before listing once triggered a dispute between car companies and Momenta.
In the automotive industry, it is generally believed that Huawei Qiankun is too expensive, so they turn to embrace Intelligent Driving companies known for cost-effectiveness like Zhuoyu and Momenta. They didn't expect their gross margins to actually exceed 50%!
In comparison, the most successful traditional car company now, BYD with Dilyan protection, has a gross margin of only 18.81%, Xiaomi Auto is 20.1%, the most successful in Harmony Intelligent Mobility is Seres with a gross margin of 26.24%. The gross margins of Chinese automotive companies are generally below 15%, some even hovering in single digits. In the industry chain end, CATL, once considered a thorn in the eye, also saw its gross margin at just 24.82% in the first quarter this year.
The logic behind this is actually not complex. Comparing the gross margins of manufacturing with software companies is comparing apples and oranges.
Horizon Robotics, in the same track as Momenta, had a 64.5% gross margin in 2025 (comprehensive gross margin of chips + intelligent driving solutions), WeRide's gross margin is also close to 30%, and Pony.ai is only 15.7%, which is related to its high production operations for Robotaxi and R&D investment.
And Momenta's ultra-high gross margin lies in its about to cross the break-even point.
Momenta's revenue increased from 743 million yuan in 2023 to 2.413 billion yuan in 2025. Gross margin was also gradually improved from 17.5% to 71.6%. R&D investment in 2025 was 1.87 billion yuan, accounting for 77.5% of revenue.
Financial Indicators (Thousand RMB)
2023
2024
2025
Operating Revenue
742,745
1,324,688
2,412,523
Gross Margin
17.5%
49.0%
71.6%
R&D Expenses
(1,281,138)
(1,508,270)
(1,868,906)
Net Loss on Books
(2,570,342)
(3,205,730)
(3,457,912)
Change in Fair Value of Preferred Shares
(1,190,108)
(1,967,501)
(2,842,919)
Adjusted Net Loss (Non-IFRS)
(1,093,037)
(959,204)
(302,804)
Although net losses are still expanding, from 570 million, 3.21 billion to 3.46 billion, but if share-based payments and other factors are excluded, the adjusted loss has narrowed from 1.09 billion yuan in 2023 to 300 million yuan in 2025. By the end of 2025, the company's cash reserves exceeded 10 billion yuan.
The signals transmitted by these numbers are very clear:
Momenta has not yet profited, but it is no longer a pure R&D company living solely on financing. It is a company with fast revenue growth, fast improvement in gross margin, and a business model that has been understood by the market.
On the eve of listing, Momenta announced that its mass production delivery scale broke through 1 million units, successfully delivered more than 100 models, with cumulative designated models exceeding 210 models. Among the top 10 global car companies, 9 have cooperated with it.

In the intelligent driving market, especially high-end intelligent driving, the only enterprise truly comparable to Momenta in scale is Huawei Qiankun.

Regarding high gross margin, Momenta's own explanation is that its revenue composition is roughly divided into two parts:
Technical development services, which means customizing intelligent driving solutions adapted to car manufacturers;
Software licensing, which means collecting intelligent driving system usage fees based on sales volume after model mass production.
The former is related to the number of cooperation models with Momenta, while the latter is linked to model sales volume.
In 2025, Momenta's technical development service revenue was 1.45 billion yuan, and software licensing revenue was 970 million yuan. In 2023, its technical service development revenue share exceeded 90%. Just two years later, its software licensing revenue share has already reached 40.1%.

Software licensing revenue is a business model where marginal cost approaches zero, requiring not too much labor cost, akin to 'lying down to collect money', which significantly raises Momenta's gross margin.
Momenta's gross margin has quadrupled in the past three years. The 71.6% gross margin in 2025 has reached the level of software company SaaS companies. This is exactly the technical compound interest that intelligent driving companies dream of: after a system matures, it can be rapidly replicated in the market.
Momenta CEO Cao Xudong stated: 'Autonomous driving has very strong scale effects and first-mover advantages. Its effect is stronger than the chip industry. Autonomous driving is software, and marginal cost is zero, so its scale effect is stronger.'
However, this model is not unique to Momenta. Inthe increasingly competitive intelligent driving supplier market today, many intelligent driving companies have combined technical development models and software licensing models to provide or develop their intelligent driving solutions for OEMs at zero cost.
Providing solutions to OEMs at below their own cost has been going on for years.
In comparison, Momenta has to some extent established its own moat. This moat is the dual connection of capital and technology established with many car manufacturers.
In the cooperation between Momenta and 24 global vehicle manufacturers, it covers nine of the top 10 global vehicle groups (such as Mercedes-Benz, Toyota, BMW China, etc.) and all of China's top 10 vehicle manufacturers.
Among these users, 7 car manufacturers with global influence, including SAIC, GM, Mercedes-Benz, Toyota, BYD, Hyundai, Chery, etc., are all investors of Momenta.
Mercedes-Benz and BYD even became cornerstone investors in Momenta's IPO.
In the industry chain end, it covers Bosch, Desay SV, Luxshare. Mobility platforms include Uber, Grab, Stone Venture, etc. Tech giants include Tencent, Alibaba Cloud, Ant Group, JD, etc.
IM Motors has achieved two-way shareholding with Momenta. SAIC Motor is Momenta's largest institutional shareholder, and Momenta also holds shares in IM Motors.
A case often cited by Momenta is that from Mercedes-Benz investing in Momenta in 2017 to mass production at the end of 2025, it took exactly 8 years. But once breakthrough is achieved, it is almost one step to the goal: Momenta obtained all of Mercedes-Benz's electric car and oil car business in 2024.
Momenta is replicating CATL and car companies achieving two-way deep binding in various ways in the intelligent driving field, letting car manufacturers participate in its profit growth.
However, OEMs have always been powerful. BYD not only invested in Momenta but also deeply invested in Zhuoyu. Moreover, at the sensitive moment of Momenta's IPO, Wang Chuanfu and Horizon Robotics founder Yu Kai being classmates triggered speculation from the outside world.
Car manufacturers represented by BYD and Chery, on one hand, have cooperated with almost all intelligent driving suppliers. On the other hand, they are still investing huge funds in self-research.
70% gross margin is indeed an irresistible temptation. After the technical route converges, all teams seem to see that the endgame of intelligent driving is not far away.
'Horizon, Zhuoyu, Huawei, and Baidu' are not only dividing spheres of influence around global OEMs, but also turning around to guard against OEM self-research substitution.
This scene has already played out once in the intelligent driving chip field. This year, self-developed chips from NIO, Xpeng, and Li Auto have been mass-produced and installed on vehicles. As a local star company in this market, Horizon Robotics' stock experienced a halving-style plunge.
'Physical AI' is such a new narrative told to both OEMs and the capital market.
From 'Autonomous Driving Solution Supplier' to 'Physical AI Foundation Model Constructor', this is not a choice of Momenta alone, but a common choice of almost all intelligent driving suppliers.
03.
'Physical AI' Hides the Ambition of a Platform Company
Essentially, autonomous driving is physical AI, and physical AI is the intelligent driving of all things. There is no difference between the two.
It is just that Physical AI opens up the imagination space for capital. It accurately describes a clear vision for an intelligent driving company to move from a one-dimensional supplier relying on OEMs to a higher-dimensional AI platform company.
Physical AI, a concept popularized by Jensen Huang, is relative to Digital AI. In the red sea competition of Digital AI, intelligent driving companies become the pioneers of Physical AI. For some top players, they also have data and scale advantages.
Momenta is undoubtedly an outstanding player in both fields. Momenta stated that it has run through data and business scaling through 1 million mass-produced vehicles.
And the time for Momenta to confidently build the world foundation model has matured. It is NVIDIA's launched world model that is evolving from a simulation tool for intelligent driving companies to a main model that generates data for training or testing, becoming a foundation model that can be applied to 'End-to-End Foundation Model Pre-training' to understand physical laws of the world. By compressing the laws of the physical world into the model, World Model acquires common sense of the physical world.
Momenta's launched R7 World Model claims to achieve a 10 to 100-fold generational leap in the overall system performance and upper limits.
World Models can empower four major business forms of passenger cars, Robotaxi, Robovan, and Robotruck with the same underlying system architecture, and are expected to extend to fields such as Embodied AI.
Momenta's vision for Physical AI is All-in-One Platform, achieving technology cross-scenario implementation, becoming an AI platform company.
This minimalist architecture will thoroughly end the past pattern of isolated development in various scenarios. The cross-scenario reuse of core underlying technologies greatly amortizes R&D costs for parallel multiple business lines and improves the overall iteration efficiency of the system.
Momenta describes it as: 'One Model, Multi-dimensional Coexistence', which can greatly dilute R&D costs, and expand with business boundary expansion, exponentially amplifying first-mover advantages, forming an 'Winner Takes All' industry endgame.
Its gross margin will even exceed 70%.
Cao Xudong believes: 'Any artificial intelligence application, once approaching human levels, will far exceed human levels in a very short period of time.'
This means that it may take ten or twenty years to climb ahead, but surpassing humans may happen within one or two years. Currently, almost all intelligent driving companies have announced transformation towards Physical AI, and its urgency lies in this.
Currently, whether adhering to the World Model route or the similarly hot VLA model intelligent driving companies have basically打通ed L2 to L4.
Momenta adheres to the years-long 'One Flywheel, Two Legs' strategy. Based on unified algorithms and sensor architectures, it has achieved the connection between L2++ data flow and L4 technology flow. Its technology can be reused in passenger cars and Robotaxi.
However, today, this increasingly approaching 'Android' intelligent driving platform's biggest market is still in the passenger vehicle market.
In the CIC Consulting data cited by Momenta itself:
By 2030, the global Robo market scale (Robotaxi, Robovan, Robotruck) will reach 199.8 billion USD, among which Robotaxi global and China market scale will grow to about 81.8 billion USD and 38.1 billion USD respectively. China Robotaxi penetration rate is expected to reach 11.9%, higher than the global 5.7%. Robovan global and China market scale will reach about 85 billion USD and 53.5 billion USD respectively, market penetration rate will reach 6.9% and 14.0%. Robotruck global and China market scale will reach about 33 billion USD and 16.5 billion USD respectively, market penetration rate will reach 0.6% and 1.2%.

But the mass production assisted driving market scale by 2030, global market scale will reach 305.9 billion USD, still far exceeding the Robo market:
In 2025, global and China L2-level - Highway NOA / L2-level - City NOA assisted driving and higher-level intelligent driving market scale reached about 20.4 billion USD and 13 billion USD respectively. It is expected to expand to 305.9 billion USD and 166.6 billion USD by 2030, with compound annual growth rates of 71.9% and 66.5% respectively.

And the Robotaxi market faces huge uncertainty due to city access policies, different regulatory regulations in various places, and operating costs.
Momenta's IPO fundraising this time will invest about 20% in Robotaxi commercialization and scaling. On one hand, L4 has huge imagination space, but it is also the most uncertain part. When Robotaxi will truly contribute clear revenue still has no clear schedule.
Meanwhile, in the passenger vehicle market, although Momenta has obvious advantages, it has not killed the game.
In the traditional so-called Horizon, Huawei Qiankun Intelligent Driving, Zhuoyu, there are still WeRide, Pony.ai. Also preparing for IPO are Qingzhou Smart Driving, DeepRoute.ai.
Skyway Technology, Baidu Apollo, etc. have also established certain advantages in the L4 market.
04.
Intelligent Driving Market Has Not Formed Winner Takes All
An intelligent driving platform similar to Android will eventually appear, but ultimately who wins remains, and no company has established an absolute advantage.
This makes the sustainability of Momenta's high gross margins also uncertain.
First, the continuous decline of single car software licensing unit price has become an industry trend. With more players entering the track and acceleration of penetration in low-end models, city NOA software licensing fees have dropped from several thousand yuan in the early days to the level of thousands, with some lightweight solutions having even lower unit prices.
To seize the mid-to-low-end model market, Momenta actively sinks pricing. While expanding on a large scale, it will inevitably face the pressure of shrinkage in single model profit.
Second, customer concentration is extremely high, bargaining power is fragile. In the past three years, the top five customers contributed 62.6% to 86.7% of revenue. In 2025, the revenue share of the largest customer (presumably BYD) reached 21.6%. If a core customer has sales lower than expected or turns to self-research/competitors, licensing fee revenue will suddenly stop. BYD as Momenta's largest customer, annual installation is about 300,000 vehicles. Its strategic choice will directly affect Momenta's revenue stability.
Third, the rebellion of self-research by car manufacturers is accelerating. Practices by top car manufacturers such as Geely, BYD, and NIO show that only by breaking external binding with independent technology can pricing rights be reclaimed.
Geely insists on self-research of Three Electric Systems, Intelligent Driving, Cockpit. Zeekr 9X is equipped with self-developed Qianli Haohan G-ASD Intelligent Driving System, gross margin stabilized above 20%. NIO announced full fleet replacement with self-developed Shenji NX9031 chip, single car cost directly reduced by 10,000 yuan.
It can be said that for Momenta, 71.6% gross margin is both a moat and a gunpowder keg.
Cao Xudong predicts 'Long-term third-party supply will be the market mainstream', but ultimately forming a 2-3 'Winner Takes All' industry endgame is obviously not what OEMs hope to see.
Momenta has the opportunity to be the one among Chinese intelligent driving companies that is first regarded by the market as a platform-type AI enterprise. But if it fails to achieve monopoly advantage in time, it may also be quickly pulled back to the traditional autonomous driving valuation framework of 'High R&D, Heavy Investment, Unprofitable'.
From this angle, Momenta's listing is not only a critical moment for itself, but also a public defense for the entire autonomous driving and Physical AI industry.
Written at the end
After Embodied AI, Physical AI concepts enter public discourse, autonomous driving seems to have lost its charm. An intuitive manifestation is the influx of a large number of autonomous driving talents into Embodied AI startups. Musk dismantling Model S/X production lines to produce robots is a crude and jaw-dropping move.
So, can putting a Physical AI crown on autonomous driving attract the capital frenzy triggered by Digital AI?
Anthropic, founded only five years ago, realized a 965 billion USD stunning valuation of course did not repeat on Momenta.
What can be explained is that the Physical AI concept has a certain deception. It is not completely isolated and relative to Digital AI. For OpenAI, Gemini these digital large models, they can also enter any business track focused by Physical AI.
On May 16 this year, Zhuoyu Technology CEO Shen Shaojie issued a warning to his peers:
'I am very worried about those doing large models entering intelligent driving, which would be a dimensional strike against us. What I am really afraid of is that digital AI large model companies reverse and wipe us out.'
'Except for Tesla, no intelligent driving company has truly implemented Scaling Law (model quality changes as computing power / data / parameters expand); but OpenAI, ByteDance have already run through Scaling Law.'
And large model companies represented by OpenAI follow 'Multimodal + World Model + Autoregressive Reasoning', which naturally suits 'Visual Prediction + Physical Reasoning + Long-horizon Decision Making', which is exactly the technical core of intelligent driving systems.
Large Modelsdon't need to learn to drive from scratch, just fine-tuning, to quickly reach even exceed L2+/L4 capabilities.
In other words, although the company positioning most similar to Momenta is Huawei Infront and Horizon, the long-term competitors for these intelligent driving companies are neither each other nor OEM self-research, but may come from barbarians outside.
喺馬來西亞嘅 SUV 市場,好多買家喺揾車嘅時候都會拿 Proton X70 同 Chery Tiggo 8 嚟做比較。呢兩款車喺價位同定位上都好接近,今日我哋就從多個方面做一個詳細嘅對比,幫你節省做功課嘅時間。
Proton X70 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,300,總共有 3 個版本,包括 1.5L Standard 2WD(RM 106,800)、1.5L Executive 2WD(RM 115,800)、1.5L Premium 2WD(RM 122,300) 等。
Chery Tiggo 8 喺馬來西亞嘅 OTR 售價係 RM 129,750 - 129,750,總共有 1 個版本,包括 2026 1.6T Standard(RM 129,750) 等。
由價錢睇,Proton X70 嘅起步價真係比 Chery Tiggo 8 平咗 RM 22,950。如果你預算有限,Proton 嘅入門版已經足夠應付日常需求。但都要留意,平咗嘅幾千蚊,喺配備上可能会有取捨,具體要看你嘅需求。

Proton X70 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
Chery Tiggo 8 嘅安全評級係 TBD,主動安全系統包括 Basic。
安全配備方面,兩款車都攞到唔錯嘅評級。不過 Proton X70 嘅 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA) 同 Chery Tiggo 8 嘅 Basic 喺功能上有些差異,如果你比較看重主動安全嘅話,可以仔細對比下兩者嘅功能列表。

Proton X70 採用 FWD 驅動方式。
Chery Tiggo 8 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感覺唔會有太大分別。

Proton X70 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
Chery Tiggo 8 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
Proton X70 同 Chery Tiggo 8 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。最終都建議兩款都去試駕,親身體驗先係最重要。
總體嚟講,Proton X70 同 Chery Tiggo 8 都係馬來西亞市場好唔錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕先做最後決定。買車係件大事,花啲時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 Proton X90 同 Toyota Yaris Cross 嚟做比較。呢兩款車喺價位同定位上都差唔多,今日我哋就由多個方面做一個詳細嘅比較,幫你節省做功課嘅時間。
Proton X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,合共 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800)等。
Toyota Yaris Cross 喺馬來西亞嘅 OTR 售價係 RM 99,900 - 109,900,合共 2 個版本,包括 2026 1.5L Standard(RM 99,900)、2026 HEV 1.5L Standard(RM 109,900)等。
從價錢嚟睇,Toyota Yaris Cross 嘅起步價比 Proton X90 平咗 RM 6,900。老實講,喺呢個價位段,幾千蚊嘅差距其實唔算大,關鍵都係睇整體嘅性價比同長期使用成本。

Proton X90 配備 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
Toyota Yaris Cross 配備 1.5L 4-cyl,馬力 105 hp。官方油耗 6.0 L/100km。
動力方面,Proton X90 嘅 1.5L Turbo 比 Toyota Yaris Cross 嘅 1.5L 4-cyl 多出 35 匹馬力,中段加速更有信心,尤其係跑高速超車嗰陣。不過 Toyota Yaris Cross 嘅油耗可能相對抵啲,日常市區通勤差別唔會太大。

Proton X90 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
Toyota Yaris Cross 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 TSS。
兩款車嘅安全評級一樣,喺呢個級別裡面安全配備都算好齊全。而家嘅新車安全性都唔差,唔使太擔心這一點。
Proton X90 車身長 4400 mm,行李廂 400 L。
Toyota Yaris Cross 車身長 4400 mm,行李廂 400 L。
兩款車嘅尺寸差唔多,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

Proton X90 同 Toyota Yaris Cross 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。最終都係建議兩款都去試車,親身體驗先係最重要。

總體嚟講,Proton X90 同 Toyota Yaris Cross 都係馬來西亞市場幾不錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需求同預算。建议大家做好功課,多比較幾間車行嘅報價,再去試車做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿馬自達 CX-60 同奇瑞 Tiggo 9 嚟做比較。
馬自達 CX-60 喺馬來西亞嘅 OTR 售價係 RM 200,510 - 252,873,合共 2 個版本,包括 2026 3.3T 4WD High Plus(RM 252,873)、2025 2.5L 2WD High(RM 200,510) 等。
奇瑞 Tiggo 9 喺馬來西亞嘅 OTR 售價係 RM 166,800 - 179,800,合共 1 個版本,包括 2026 2.0T Standard(RM 179,750) 等。
睇價錢嚟講,奇瑞 Tiggo 9 嘅起步價比馬自達 CX-60 平咗 RM 33,710。講真,喺呢個價位段,幾千蚊嘅差距其實唔算大,關鍵仲係睇整體嘅性價比同長期使用成本。

馬自達 CX-60 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 i-Activsense Pro。
奇瑞 Tiggo 9 嘅安全評級係 TBD,主動安全系統包括 Basic。
安全配備方面,兩款車都拿到唔錯嘅評級。不過馬自達 CX-60 嘅 i-Activsense Pro 同奇瑞 Tiggo 9 嘅 Basic 喺功能上有啲差異,如果你比較看重主動安全嘅話,可以仔細對比下兩者嘅功能列表。

馬自達 CX-60 採用 FWD 驅動方式。
奇瑞 Tiggo 9 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大區別。

馬自達 CX-60 同奇瑞 Tiggo 9 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,那就選配置更豐富嗰款。最終仲係建議兩款都去試駕,親身體驗先至最重要。

總體嚟講,馬自達 CX-60 同奇瑞 Tiggo 9 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵仲係要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

111万台,同比跌了17.44%——长安汽车2026年上半年的这个销量成绩,确实出乎意料,比去年同期整整少卖了将近24万辆车。24万台什么概念?放到国内车市,可是一些造车新势力的全年销量。更让人揪心的是,从4月起长安的月销量就像踩了刹车——4月同比跌5.95%,5月跌19.71%,6月跌14.09%,连续三个月同比往下掉,一点反弹的迹象都没有。

乍一看,这成绩单像是在说:长安不行了。但冷静下来拆一拆数据,你会发现事情没那么简单。
先拆数据,别被表面数字唬了
自主品牌上半年卖了92万台,同比下滑19.91%——这块是长安的根基,跌幅比大盘还狠。新能源上半年41万台,同比跌8.3%,跌幅温和一些,但方向还是在往下走。乍一看,基本盘和增长盘都在缩,故事似乎很悲观。

但有一个数字很多人没注意到:6月海外销量91065台,占当月总销量的45%。将近一半的车卖到了国外。上半年海外交付40.2万台,同比增长35.1%。换句话说,如果把海外市场抽掉,长安国内部分的跌幅会比现在看起来更惨;但反过来讲,海外已经是长安实实在在的增长引擎了,不是嘴上说说那种。
为什么跌?屋里屋外都有账要算
先说外因。2026年春节来得早,1月本来就没什么卖车的日子,再加上去年新能源补贴退坡前那波抢购潮,把不少消费者的购买力提前透支了。一季度整个行业都在吃这碗苦饭,长安不是孤例——同期其他车企数据也不好看。这是行业性的阵痛,不是长安独有的问题。
再说内因。长安的新能源产品正处于新旧交接期,好几款主力车型在换代,旧款收尾、新款还没上量,中间这段空档自然会影响销量数字。另外,长安今年明显在主动调整产品结构——砍掉一部分薄利多销的低端燃油车型,不再单纯追求规模。董事长朱华荣公开说了,过去是量在先、利在后,今年开始要量利并重。这话听着像是官方辞令,但落到实处就是:宁可销量少一点,也不靠亏本换数字。

这种主动收缩短期当然要付出代价,销量会掉。但问题是——你到底是被动滑坡还是主动择路?这两者的区别,半年报看不出来,到年底才见真章。
长安手里还有牌,而且牌面不差
出海这块,长安已经不只是把车卖出去那么简单了。泰国罗勇工厂投产13个月就下线了第2万台整车,巴西工厂今年3月投产。这套当地造、当地供、当地融的打法,正在把海外从增量市场变成真正的增长支柱。上半年海外销量同比增长35.1%,这个速度在行业里算快的。覆盖118个国家和地区、1124家销售网点,布局已经铺开了,不是试探阶段。

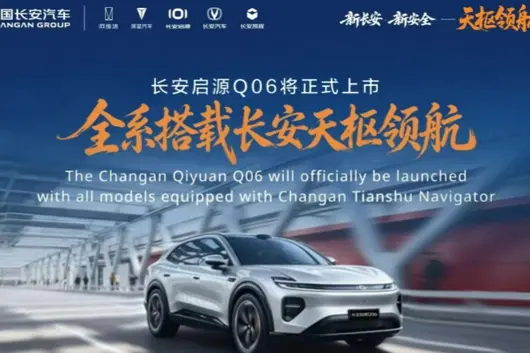
技术上,6月重庆车展长安发布了自研辅助驾驶系统天枢领航,分Pro、Max、Ultra三个版本,首款搭载车型启源Q06下半年上市。蓝鲸超擎混动已经量产,城区百公里油耗2.98L——第四代逸动和CS75 PLUS已经在路上测试了。最值得关注的是金钟罩固态电池,能量密度400Wh/kg,满电续航超1500公里,三季度前完成装车验证。如果这三项技术都能按计划落地,长安在新能源下半场的技术储备并不弱。

产品端,2026年全年计划投放10余款新车型和改款,包括启源Q06、深蓝L05、阿维塔06T,以及阿维塔全新旗舰大六座SUV。阵容在扩充,价位和场景覆盖也在拓宽。再加上阿维塔和深蓝两大品牌正在推进战略性整合,整合后成本有望降低20%到30%——这是用体系效率换竞争力,不是靠堆车型数量硬撑。
核心判断:下滑是事实,但不是终局
330万辆的年度目标,上半年只完成了33.9%,下半年要卖219万台才能摸到目标线——比去年下半年还得多卖将近40万台。压力确实不小。
但车市从来不以半场定输赢。下半年是传统旺季,金九银十加上年底冲量,变数很大。更关键的是,长安这轮下滑里夹杂着主动调整的成分——砍低端、推新品、整合品牌、转向量利并重。这些动作短期伤销量,长期看是在给下半场攒弹药。

当然,对手也没闲着。比亚迪的规模优势还在扩大,吉利海外也在加码,蔚来和小鹏在高端市场持续蚕食。长安下半场要追分,靠的不是喊口号,而是技术兑现的速度、产品上量的节奏,还有海外市场能不能继续以35%以上的增速往下跑。
半年报就像一场足球赛的中场哨——上半场踢得不好,数据摆在那谁也回避不了。但下半场还有45分钟,长安手里的牌不少:海外势头猛,技术底子厚,产品矩阵还在扩充,战略也在主动求变。能不能翻盘,考验的不是决心,是执行力和时间窗口的把握。毕竟车市这盘棋,对手不等人,时间更不等人。
喺馬來西亞嘅 SUV 市場,好買家在揀車嘅時候都會拿 Chery Tiggo Cross 同 Mitsubishi Xforce 嚟做比較。這兩款車喺價位同定位上都好接近,今日我哋就從多個方面做一個詳細嘅比較,幫你省咗做功課嘅時間。
Chery Tiggo Cross 喺馬來西亞嘅 OTR 售價係 RM 88,750 - 99,750,一共有 2 個版本,包括 2025 HEV 1.5L CSH(RM 99,750)、2025 1.5T Standard(RM 88,750)等。
Mitsubishi Xforce 喺馬來西亞嘅 OTR 售價係 RM 109,930 - 119,930,一共有 2 個版本,包括 2026 1.5L Ultimate(RM 119,930)、2026 1.5L Urban(RM 109,930)等。
從價錢來看,Chery Tiggo Cross 嘅起步價確實比 Mitsubishi Xforce 平咗 RM 21,180。如果你預算有限,Chery 嘅入門版已經可以滿足日常需求。但亦都要留意,平嗰幾千蚊,可能喺配備上會有取舍,具體要睇你嘅需求。

Chery Tiggo Cross 採用 FWD 驅動方式。
Mitsubishi Xforce 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

Chery Tiggo Cross 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
Mitsubishi Xforce 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
兩款車嘅保修條件一樣,呢方面唔使諗太多。實際保養成本仲要睇品牌嘅服務網絡同零件價格,建議去車友群問問真實車主嘅經驗。

Chery Tiggo Cross 同 Mitsubishi Xforce 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更看重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就揀配置更豐富嗰款。最尾都係建議兩款都去試駕,親身體驗先係最重要嘅。

總嚟講,Chery Tiggo Cross 同 Mitsubishi Xforce 都係馬來西亞市場幾唔錯嘅車款。揀邊輛,關鍵仲要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿奇瑞 Tiggo 8 PHEV 同速霸陸 Outback 嚟做比較。呢兩款車喺價位同定位上都幾相近,今日我哋就由多個角度做一個詳細比較,幫你節省做功課嘅時間。
奇瑞 Tiggo 8 PHEV 喺馬來西亞嘅 OTR 售價係 RM 159,750 - 159,750,一共有 2 個版本,包括 1.6L Turbo Standard(RM 130,000)、1.6L Turbo Premium(RM 145,000)等。
速霸陸 Outback 喺馬來西亞嘅 OTR 售價係 RM 260,000 - 280,000,一共有 2 個版本,包括 2025 2.4T R-Touring EyeSight(RM 310,340)、2025 2.5L Touring EyeSight(RM 280,340)等。
由價錢來看,奇瑞 Tiggo 8 PHEV 嘅起步價確實比速霸陸 Outback 平咗 RM 100,250。如果你預算有限,奇瑞嘅入門版已經可以滿足日常需要。但都要注意,平嗰幾千蚊,可能喺配備上會有所取捨,具體要睇返你嘅需要。

奇瑞 Tiggo 8 PHEV 搭載 Hybrid,馬力 170 hp。官方油耗 4.5 L/100km。
速霸陸 Outback 搭載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
動力方面,速霸陸 Outback 嘅 2.0L Turbo 比奇瑞 Tiggo 8 PHEV 嘅 Hybrid 多咗 50 匹馬力。不過日常喺市區行,兩款車嘅動力都夠用,唔會覺得唔夠力。

奇瑞 Tiggo 8 PHEV 車身長 4400 mm,尾箱 400 L。
速霸陸 Outback 車身長 4400 mm,尾箱 400 L。
兩款車嘅尺寸幾近一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。

奇瑞 Tiggo 8 PHEV 採用 FWD 驅動方式。
速霸陸 Outback 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
奇瑞 Tiggo 8 PHEV 同速霸陸 Outback 都係馬來西亞市場嘅主流選擇,適合家庭用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更在意性價比同配備,就揀配置更豐富嗰款。最終都建議兩款都去試駕,親身體驗先係最重要。
總而言之,奇瑞 Tiggo 8 PHEV 同速霸陸 Outback 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵主要仲係要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,先至去試駕做最終決定。買車係件大事,花啲時間做功課絕對唔會錯。

In Malaysia's SUV market, many buyers compare Hyundai Palisade and Volvo XC90 PHEV when choosing a car. These two cars are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
Hyundai Palisade's OTR price in Malaysia is RM 368,838 - 399,838, with 4 versions in total, including 2023 3.8L 2WD Luxe 7 Seats Petrol (RM 399,838), 2023 2.2T 4WD Executive 7 Seats Diesel (RM 389,838), 2023 3.8L 2WD Luxe 8 Seats Petrol (RM 378,838), etc.
Volvo XC90 PHEV's OTR price in Malaysia is RM 434,888 - 434,888, with 2 versions in total, including 2025 2.0T 77km Ultra (RM 434,888), What safety features does the Volvo XC90 PHEV have? (RM 362,888), etc.
From a price perspective, Hyundai Palisade's starting price is indeed RM 66,050 cheaper than Volvo XC90 PHEV. If your budget is limited, Hyundai's entry-level version can already meet daily needs. But also note that the few thousand yuan cheaper might have trade-offs in features, it depends on your specific needs.

Hyundai Palisade is equipped with 2.0L Turbo, horsepower 220 hp. Official fuel consumption 9.5 L/100km.
Volvo XC90 PHEV is equipped with Hybrid, horsepower 170 hp. Official fuel consumption 4.5 L/100km.
In terms of power, Hyundai Palisade's 2.0L Turbo has 50 more horsepower than Volvo XC90 PHEV's Hybrid, with more confidence in mid-range acceleration, especially when overtaking on highways. However, Volvo XC90 PHEV's fuel consumption might be more friendly, and the difference in daily city commuting will not be too large.

Hyundai Palisade's safety rating is TBD, active safety systems include Basic.
Volvo XC90 PHEV's safety rating is 5★ (Euro NCAP), active safety systems include Premium ADAS.
In terms of safety features, both cars have received good ratings. However, Hyundai Palisade's Basic and Volvo XC90 PHEV's Premium ADAS have some differences in functionality. If you value active safety more, you can carefully compare the feature lists of both.

Hyundai Palisade uses FWD drive method.
Volvo XC90 PHEV uses FWD drive method.
The drive methods of both cars are the same, both are FWD, daily driving experience will not be too different.

Hyundai Palisade and Volvo XC90 PHEV are both mainstream choices in the Malaysia market, suitable for family use, daily commuting. If you value brand reputation and second-hand price more, you can prioritize the one with better reputation; if you value cost-performance and features more, choose the one with richer configuration. Finally, it is recommended to test drive both, personal experience is the most important.

Overall, Hyundai Palisade and Volvo XC90 PHEV are both very good models in the Malaysia market. Which one to choose depends on your personal needs and budget. It is recommended to do homework, compare quotes from several car dealers, and then test drive to make the final decision. Buying a car is a big matter, spending time doing homework will never be wrong.

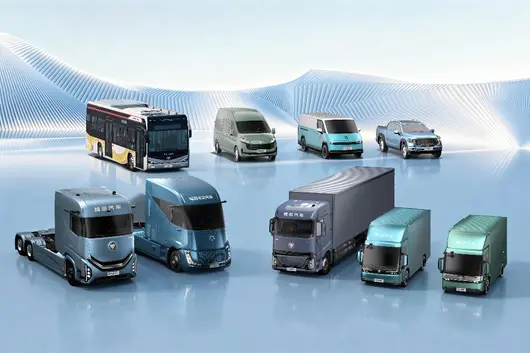
2026年已过半,商用车行业年中大考的交卷铃正式拉响。在行业销量波动加剧、结构分化加深的复杂阶段,福田汽车以一份逆势突围的成绩单,为上半年画上了掷地有声的句点。最新数据显示,福田汽车1-6月销量超36万辆,同比增长10.1%,不仅以领跑姿态完成半年收官,更展现出头部企业在周期穿越中战略定力与战术爆发的双重优势。
细剖这份成绩单,销量的增长绝非粗放式的规模堆砌,而是技术创新、结构优化、全球布局三股力量同频共振的结果。1-6月,福田新能源销量5.9万辆,同比增长17.9%;重卡板块销量超9万辆,同比攀升35.3%,跑赢行业大盘;海外出口持续放量,上半年销量10.9万辆,同比大幅增长38.9%。新能源、重卡、海外“三驾马车”齐头并进,不仅构成了福田上半年冲刺的核心引擎,更折射出这家企业从传统制造向科技驱动、从国内市场向全球版图、从产品竞争向价值竞争跃迁的深层逻辑。

穿透周期迷雾,重塑商用车价值标尺
商用车的新能源化,是一场从政策牵引到市场驱动的漫长跋涉。当补贴退坡的阵痛尚未完全消散、充电基础设施仍在织网阶段,不少企业选择了观望与降速。然而,福田汽车6月新能源销量近1.35万辆、同比达到62.5%的成绩,却向行业传递了一个清晰信号:新能源商用车的爆发不是“等”来的,而是“攻”出来的。
这份底气的源头,是福田在新能源领域近二十年的战略定力。在技术路线上,福田早已跳出“押注单一技术”的投机思维,构建起纯电动、混合动力、氢燃料电池三线并举的完整技术矩阵。6月,在城市物流赛道,福田欧马可Z凭借启明星纯电轻卡专属平台、爱易科三电系统带来的能效突破,以长续航、低能耗重塑用户对新能源轻卡的认知边界;在公共服务领域,福田欧辉新能源客车在天津、沈阳等地批量交付,为高温天气下的零碳出行提供稳定可靠的运力保障;在长途干线、冷链运输等核心细分市场,福田重卡以场景定义产品的开发理念持续兑现,用实际表现回应了“新能源能否胜任极限工况”的行业之问。
更为关键的是,福田新能源销量的领先,已逐步从政策红利切换至价值驱动。依托在整车集成、电驱动、电控、动力电池及氢燃料电池等领域积淀的深厚技术底蕴,自主研发并牢牢掌握“三电”核心技术,福田正将新能源商用车的竞争优势,从“购置补贴”拉回到“全生命周期成本”这一商业本质。当TCO优势开始显现,新能源商用车便不再只是一道环保必答题,而成为用户精打细算之后的最优解。6月的销量突破,正是这一拐点临近的鲜明注脚。
重卡结构升级加速,定义存量竞争新规则
重卡市场,作为商用车行业技术含量最高、竞争最为激烈的细分领域。6月,在行业整体需求趋于理性的背景下,福田重卡以1.43万辆的月销量实现25.9%的同比增长。支撑这一成绩的,不是价格战的短期刺激,而是一场围绕产品结构、动力路线、用户价值的深层革命。

上半年,福田燃气牵引车市场表现尤为突出。面对油气价差持续扩大的市场机遇,福田欧曼以极快的响应速度完成产品布局与产能爬坡。这背后的战略逻辑清晰而务实:当运价低迷、柴油成本高企挤压利润空间时,天然气路线以实实在在的燃料成本优势,成为用户降本增效的理性选择。福田所做的,是用可靠的产品将这一经济账变成可兑现的收益。
在高端重卡领域,福田欧曼正用一场极限挑战重新定义行业的价值标尺。近期收官的“欧曼银河9全域领鲜极效节油挑战赛”中,欧曼银河9在实货、实路、实景的严苛工况下,由一线用户驾驶,跑出了百公里油耗30.3L的亮眼成绩。这一成绩的取得,是动力链精准匹配、整车空气动力学优化、轻量化设计协同发力的系统性成果,折射出福田欧曼将多年技术积淀转化为用户真实收益的能力跃迁。在重卡行业从价格竞争转向价值竞争的当下,真正的高端化,不是配置的堆砌,不是概念的包装,而是在用户最关心的运营场景里,以硬核数据兑现极致效率的承诺。福田欧曼正在用行动证明:高端重卡的价值,最终要由用户的运营账本来定义。
从出口贸易到全球深耕的体系化跃升
中国商用车出海正从零散的产品输出转向系统化的全球布局,而福田汽车是这一趋势中最具代表性的实践者。1-6月,福田海外出口销量超10.9万辆,同比增长38.9%。但比数字更值得关注的,是出口结构优化与本地化深耕所展现的全球化新范式。
今年以来,福田海外布局持续迎来收获期。在东南亚,通过泰国等地的属地化工厂实现本地化制造,将‘中国制造’与‘东盟制造’深度融合,有效规避贸易壁垒、缩短交付周期;在南亚,超百辆公交车实现批量交付,推动中国客车品牌在当地公交市场完成规模化落地。在非洲,福田完成千辆重卡订单的批量交付,为当地基础设施建设和民生保障提供可靠运力支持;在此基础上,福田重商产品体系针对非洲复杂路况进行全面定制调校,兼顾动力性能与运营成本,精准适配跨境物流、矿区运输等高强度作业场景。与此同时,新能源产品正加速成为福田出海的新名片:福田卡文汽车已成功打入欧洲15国及澳新等高势能市场……福田正将国内新能源产业的技术先发优势,转化为全球绿色交通解决方案的输出能力。

支撑海外业绩持续领跑的,是一张从制造到服务、从配件到金融的全价值网络。32个海外属地化工厂、超过1200家海外销售网络、超1500家海外服务网络——这张网的存在,让福田的全球化不再只是“把车卖出去”的一次性交易,而是“让车跑起来、让用户留下来”的深度运营。当行业还在比拼出口数量时,福田已经进入全球化3.0阶段的体系竞争,而持续领先的出口数据,正是体系能力最直接的投射。
以终为始,福田的半年答卷与全年棋局
1-6月销量的逆势领跑,为福田汽车的上半年画上了一个有力的句点。但这份成绩单的意义,远不止于数字本身。在新能源领域,它验证了从政策驱动到价值驱动的范式转换正在加速兑现;在重卡市场,它展现了结构升级和产品定义能力在存量竞争中的决定性作用;在海外版图,它标志着中国商用车全球化正从产品输出走向体系深耕的深水区。
年中已过,全年赛程进入下半程。随着国家稳增长政策效应持续释放、基础设施投资回暖、海外市场需求稳步扩张,福田汽车正站在新一轮增长周期的起点。新能源破局、重卡突围、出海远航——三箭齐发的战略格局已清晰可见。
比完成目标更重要的是方向的印证。当一家企业连续用业绩证明其战略判断的准确性时,市场应当给予的不仅是关注,更是对其行业引领价值的重新审视。福田汽车,正在用每一次销量的突破,为穿越周期的商用车行业,写下属于自己的生存法则与增长哲学。
(本文由企业提供)
喺馬來西亞嘅 SUV 市場,好多買家喺選車嘅時候都會拿 Volvo XC90 同 Mercedes-Benz GLB 嚟做比較。這兩款車喺價位同定位上都幾接近,而家我哋就由多個方面做一個詳細嘅對比,幫你省下做功課嘅時間。
Volvo XC90 喺馬來西亞嘅 OTR 售價係 RM 418,888 - 418,888,一共有 1 個版本,包括 2025 2.0T Ultra(RM 418,888)等。
Mercedes-Benz GLB 喺馬來西亞嘅 OTR 售價係 RM 299,888 - 352,888,一共有 1 個版本,包括 Standard(RM 299,888)等。
由價錢嚟睇,Mercedes-Benz GLB 嘅起步價比 Volvo XC90 平咗 RM 119,000。講真,喺呢個價位段,幾千蚊嘅差距其實唔算大,關鍵仲係睇整體嘅性價比同長期使用成本。

Volvo XC90 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
Mercedes-Benz GLB 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
兩款車嘅安全評級一樣,喺呢個級別入面安全配備都算好齊全。而家嘅新車安全性都唔差,唔使太擔心這一點。
Volvo XC90 車身長 4400 mm,後尾箱 400 L。
Mercedes-Benz GLB 車身長 4400 mm,後尾箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

Volvo XC90 保用 5 年/無限里程,保養間隔 每 10,000km 或 6 個月。
Mercedes-Benz GLB 保用 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

Volvo XC90 同 Mercedes-Benz GLB 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就揀配置更豐富嗰款。最後仲係建議兩款都去試車,親身體驗先至最緊要。
總括嚟講,Volvo XC90 同 Mercedes-Benz GLB 都係馬來西亞市場幾唔錯嘅車型。揀邊輛,關鍵仲係睇你嘅個人需求同預算。建議大家做足功課,多比較幾間車行之報價,再去試車作最後決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅 SUV 市場,好多買家喺揀車嗰陣都會拿 Volvo XC90 PHEV 同 Audi Q7 嚟做比較。呢兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一個詳細嘅對比,幫你節省做功課嘅時間。
Volvo XC90 PHEV 喺馬來西亞嘅 OTR 售價係 RM 434,888 - 434,888,合共 2 個版本,包括 2025 2.0T 77km Ultra(RM 434,888)、Volvo XC90 PHEV 有咩安全配備?(RM 362,888) 等。
Audi Q7 喺馬來西亞嘅 OTR 售價係 RM 462,222 - 462,222,合共 1 個版本,包括 Standard(RM 462,222) 等。
由價錢睇,Volvo XC90 PHEV 嘅起步價確實比 Audi Q7 平咗 RM 27,334。如果你預算有限,Volvo 嘅入門版已經可以滿足日常需要。但都要留意,平嗰幾千蚊,可能在配備上會有取捨,具體就要睇你嘅需要。
Volvo XC90 PHEV 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
Audi Q7 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
兩款車嘅安全評級一樣,喺呢個級別入面安全配備都好齊全。而家嘅新車安全性都唔差,唔使太擔心呢一點。
Volvo XC90 PHEV 車身長 4400 mm,車廂後尾箱 400 L。
Audi Q7 車身長 4400 mm,車廂後尾箱 400 L。
兩款車嘅尺寸幾乎一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全足夠。

Volvo XC90 PHEV 保修 5 年/無限里程,保養間隔 每 10,000km 或 6 個月。
Audi Q7 保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。

Volvo XC90 PHEV 同 Audi Q7 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就揀配置更豐富嗰款。最終都好建議兩款都去試駕,親身體驗先係最重要。
總體嚟講,Volvo XC90 PHEV 同 Audi Q7 都係馬來西亞市場幾不錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花啲時間做功課絕對唔會錯。

喺馬來西亞嘅轎車市場,好多買家喺揀車嗰陣都會揾豐田卡羅拉同福斯高夫嚟比較。呢兩部車喺價位同定位上都好接近,今日我哋就由多個方面嚟做個詳細對比,幫你省返做功課嘅時間。
豐田卡羅拉喺馬來西亞嘅 OTR 售價係 RM 144,800 - 149,800,一共有 2 個版本,包括 2026 年 1.8L GR Sport(RM 149,800)、2026 年 1.8L G(RM 144,800)等。
福斯高夫喺馬來西亞嘅 OTR 售價係 RM 186,530 - 186,530,一共有 1 個版本,包括 2026 年 1.5L R-Line(RM 186,530)等。
由價錢嚟睇,豐田卡羅拉嘅起步價確實比福斯高夫平咗 RM 41,730。如果你預算有限,豐田嘅入門版已經可以滿足日常需求。但都要留意,平嗰幾千蚊,可能喺配備上會有取捨,具體要睇你嘅需求。

豐田卡羅拉搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
福斯高夫搭載 2.0L 4-cyl,馬力 170 hp。官方油耗 8.0 L/100km。
動力方面,福斯高夫嘅 2.0L 4-cyl 比豐田卡羅拉嘅 1.5L Turbo 多咗 30 匹馬力。不過日常喺市區開,兩部車嘅動力都夠用,唔會覺得唔夠力。

豐田卡羅拉車身長 4400 mm,行李箱 400 L。
福斯高夫車身長 4400 mm,行李箱 400 L。
兩部車嘅尺寸幾乎一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。

豐田卡羅拉保修 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。
福斯高夫保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

總體嚟講,豐田卡羅拉同福斯高夫都係馬來西亞市場幾正嘅車型。揀邊一部,關鍵都係要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試車做最後決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅轎車市場,好多買家喺揀車嗰陣都會拿豐田佳美同福斯高爾夫 R 嚟做比較。呢兩部車喺價位同定位上都幾接近,今日我哋就從多個方面做一次詳細嘅比較,幫你省返做功課嘅時間。
豐田佳美喺馬來西亞嘅 OTR 售價係 RM 221,800 - 248,800,一共有 2 個版本,包括 2025 HEV 2.5L Standard(RM 248,800)、2025 2.5L Standard(RM 221,800) 等。
福斯高爾夫 R 喺馬來西亞嘅 OTR 售價係 RM 338,812 - 338,812,一共有 2 個版本,包括 2026 2.0T Standard(RM 338,812)、DCT(RM 294,800) 等。
從價錢來看,豐田佳美嘅起步價確實比福斯高爾夫 R 平咗 RM 117,012。如果你預算有限,豐田嘅入門版已經可以滿足日常需求。但都要注意,平嗰幾千塊,可能喺配備上會有取舍,具體要看你嘅需求。

豐田佳美裝載 2.0L 4 缸,馬力 170 hp。官方油耗 8.0 L/100km。
福斯高爾夫 R 裝載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
動力方面,福斯高爾夫 R 嘅 2.0L Turbo 比豐田佳美嘅 2.0L 4 缸多咗 50 匹馬力。不過日常喺市區開,兩部車嘅動力都夠用,唔會覺得唔夠力。

豐田佳美車身長 4400 mm,尾箱 400 L。
福斯高爾夫 R 車身長 4400 mm,尾箱 400 L。
兩部車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

豐田佳美保修 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。
福斯高爾夫 R 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

總括嚟講,豐田佳美同福斯高爾夫 R 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵始終係睇你嘅個人需求同預算。建議大家做好功課,多比較間車行嘅報價,先至去試車做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅轎車市場,好多買家喺揀車嘅時候都會拿豐田凱美瑞同福斯高爾夫 GTI 嚟比較。呢兩部車喺價位同定位上都幾接近嘅,今日我就由多個方面做個詳細嘅比較,幫你節省咗做功課嘅時間。
豐田凱美瑞喺馬來西亞嘅 OTR 售價係 RM 221,800 - 248,800,一共有 2 個版本,包括 2025 HEV 2.5L Standard(RM 248,800)、2025 2.5L Standard(RM 221,800) 等。
福斯高爾夫 GTI 喺馬來西亞嘅 OTR 售價係 RM 256,962 - 256,962,一共有 3 個版本,包括 2025 2.0T Sepang Edition(RM 262,990)、2025 2.0T Standard(RM 256,962)、DCT(RM 219,800) 等。
由價錢睇,豐田凱美瑞嘅入場價確實比福斯高爾夫 GTI 平咗 RM 35,162。如果你預算有限,豐田嘅入門版已經滿足到日常需要。但都要注意,平嘅嗰幾千蚊,可能會喺配備上有取捨,具體睇你嘅需要。
豐田凱美瑞搭載 2.0L 4-cyl,馬力 170 hp。官方油耗 8.0 L/100km。
福斯高爾夫 GTI 搭載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
動力方面,福斯高爾夫 GTI 嘅 2.0L Turbo 比豐田凱美瑞嘅 2.0L 4-cyl 多咗 50 匹馬力。不過平日喺市區行,兩部車嘅動力都夠用,唔會覺得唔夠勁。
豐田凱美瑞車身長 4400 mm,後尾箱 400 L。
福斯高爾夫 GTI 車身長 4400 mm,後尾箱 400 L。
兩部車嘅尺寸差唔多一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。
豐田凱美瑞採用 FWD 驅動方式。
福斯高爾夫 GTI 採用 FWD 驅動方式。
兩部車嘅驅動方式一樣,都係 FWD,日常駕駛感覺唔會有太大分別。

豐田凱美瑞保修 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。
福斯高爾夫 GTI 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。

總括嚟講,豐田凱美瑞同福斯高爾夫 GTI 都係馬來西亞市場幾唔錯嘅車型。揀邊一部,關鍵仲係睇你嘅個人需要同預算。建議大家做足功課,多比較幾間車行嘅報價,再一去試駕先做最後決定。買車係一件大事,花少少時間做功課絕對唔會錯。
喺馬來西亞嘅房車市場,好多買家揀車嗰陣,都會拿 Lexus ES 同 Mercedes-Benz E-Class 嚟比。呢兩款車喺價位同定位上都好接近,今日我哋就從多個方面做一次詳細比較,幫你省返做功課嘅時間。
Lexus ES 喺馬來西亞嘅 OTR 賣價係 RM 320,888 - 371,888,合共 4 個版本,包括 2025 250 F Sport(RM 371,888)、2025 250 Luxury(RM 356,888)、2025 250 Premium(RM 320,888)等。
Mercedes-Benz E-Class 喺馬來西亞嘅 OTR 賣價係 RM 363,888 - 363,888,合共 2 個版本,包括 E 200 Avantgarde(RM 350,000)、E 300 AMG Line(RM 400,000)等。
由價錢睇,Lexus ES 嘅入門價真係比 Mercedes-Benz E-Class 平咗 RM 43,000。如果你預算有限,Lexus 嘅入門版已經可以滿足日常需要。但都要注意,平嗰幾千蚊,可能喺配備上有取舍,就要睇返你嘅需要。

Lexus ES 嘅安全評級係 TBD,主動安全系統包括 Basic。
Mercedes-Benz E-Class 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 。

Lexus ES 採用 FWD 驅動方式。
Mercedes-Benz E-Class 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。

Lexus ES 保養 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
Mercedes-Benz E-Class 保養 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
兩款車嘅保養條件一樣,呢方面唔使糾結。實際保養成本仲要睇品牌嘅服務網絡同零件價格,建議去車友群問吓真實車主嘅經驗。

Lexus ES 同 Mercedes-Benz E-Class 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更在意性價比同配備,就揀配備更豐富嗰款。最終都係建議兩款都去試駕,親身體驗先係最重要。

總體嚟講,Lexus ES 同 Mercedes-Benz E-Class 都係馬來西亞市場好唔錯嘅車型。揀邊部,關鍵都要睇返你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花點時間做功課絕對唔會錯。

喺馬來西亞嘅轎車市場,好多買家喺揀車嗰陣都會拿 BMW 3 Series 同 Mercedes-Benz E-Class 來作比較。呢兩部車喺價位同定位上都好接近,今日我哋就從多個方面做一次詳細嘅比較,幫你省咗做功課嘅時間。
BMW 3 Series 喺馬來西亞嘅 OTR 售價係 RM 267,800 - 392,800,一共有 2 個版本,包括 320i Sport(RM 248,000)、330i M Sport(RM 298,000) 等。
Mercedes-Benz E-Class 喺馬來西亞嘅 OTR 售價係 RM 363,888 - 363,888,一共有 2 個版本,包括 E 200 Avantgarde(RM 350,000)、E 300 AMG Line(RM 400,000) 等。
從價錢來看,BMW 3 Series 嘅入門價確實比 Mercedes-Benz E-Class 平咗 RM 96,088。如果你預算有限,BMW 嘅入門版已經可以满足日常需要。但亦要注意,平嗰幾千蚊,可能喺配備上會有取舍,具體睇你嘅需求。

BMW 3 Series 搭載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
Mercedes-Benz E-Class 搭載 2.0L Turbo,馬力 220 hp。官方油耗 9.5 L/100km。
兩部車用咗同一套動力系統,日常駕駛嘅感覺基本冇分別。油耗方面都差唔多,唔使太糾結呢一點。
BMW 3 Series 車身長 4400 mm,尾箱 400 L。
Mercedes-Benz E-Class 車身長 4400 mm,尾箱 400 L。
兩部車嘅尺寸幾乎一樣,車廂空間分別唔大。呢個級別嘅車,日常使用完全夠用。

BMW 3 Series 採用 FWD 驅動方式。
Mercedes-Benz E-Class 採用 FWD 驅動方式。
兩部車嘅驅動方式一樣,都係 FWD,日常駕駛感覺唔會有太大分別。
BMW 3 Series 保修 5 年/無限里程,保養間隔 每 10,000km 或 6 個月。
Mercedes-Benz E-Class 保修 3 年/100,000km,保養間隔 每 10,000km 或 6 個月。
總括嚟講,BMW 3 Series 同 Mercedes-Benz E-Class 都係馬來西亞市場幾好嘅車型。揀邊一部,關鍵始終都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,先至去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。

喺馬來西亞嘅汽車市場,好多買家喺揀車嗰陣都會拿 Proton X90 同 Toyota Fortuner 嚟做比較。今日我哋由多個方面做一個詳細嘅對比,幫你節省咗做功課嘅時間。

Proton X90 喺馬來西亞嘅 OTR 售價係 RM 106,800 - 122,800,合共有 4 個版本,包括 2026 1.5T Prime X(RM 122,800)、2026 1.5T Prime(RM 116,800)、2026 1.5T Lite(RM 106,800)等。
Toyota Fortuner 喺馬來西亞嘅 OTR 售價係 RM 195,880 - 241,880,合共有 3 個版本,包括 2024 2.8T VRZ Diesel(RM 241,880)、2024 2.7L SRZ Petrol(RM 202,880)、2024 2.4L Standard Diesel(RM 195,880)等。
從價錢睇,Proton X90 嘅起步價確實比 Toyota Fortuner 平咗 RM 89,080。如果你預算有限,Proton 嘅入門版已經可以满足日常需要。但都要留意,平嗰幾千塊,可能喺配備上會有取捨,具體要睇你嘅需求。
Proton X90 嘅安全评分係 5★ (ASEAN NCAP),主動安全系統包括 ADAS (ACC, AEB, LKA, LDA, BSM, RCTA)。
Toyota Fortuner 嘅安全评分係 5★ (ASEAN NCAP),主動安全系統包括 。
兩款車嘅安全评分一樣,喺呢個級別裡面安全配備都算給得好齊全。而家嘅新車安全性都唔錯,唔使太擔心這一點。
Proton X90 採用 FWD 驅動方式。
Toyota Fortuner 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感覺唔會有太大分別。
Proton X90 同 Toyota Fortuner 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑好嗰款;如果你更在意性價比同配備,那就揀配置更豐富嗰款。最終都係建議兩款都去試駕,親身體驗先係最重要。
總括嚟講,Proton X90 同 Toyota Fortuner 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花啲時間做功課絕對冇錯。
喺馬來西亞嘅汽車市場,好多買家喺揀車嘅時候都會拿 Mazda CX-9 同 Volvo XC90 嚟做比較。今日我哋從多個方面做一次詳細嘅比較,幫你節省做功課嘅時間。

Mazda CX-9 喺馬來西亞嘅 OTR 售價係 RM 328,810 - 345,810,一共有 2 個版本,包括 2023 2.5T 4WD(RM 345,810)、2023 2.5T 2WD(RM 328,810) 等。
Volvo XC90 喺馬來西亞嘅 OTR 售價係 RM 418,888 - 418,888,一共有 1 個版本,包括 2025 2.0T Ultra(RM 418,888) 等。
由價錢睇,Mazda CX-9 嘅起步價確實比 Volvo XC90 平咗 RM 90,078。如果你預算有限,Mazda 嘅入門版已經可以滿足日常需求。不過都要注意,平嘅嗰幾千蚊,可能喺配備上會有取捨,具體要看你嘅需求。

Mazda CX-9 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 Brand ADAS。
Volvo XC90 嘅安全評級係 5★ (Euro NCAP),主動安全系統包括 Premium ADAS。
安全配備方面,兩款車都拿到唔錯嘅評級。不過 Mazda CX-9 嘅 Brand ADAS 同 Volvo XC90 嘅 Premium ADAS 喺功能上有些差異,如果你比較重視主動安全嘅話,可以仔細比較下兩者嘅功能列表。

Mazda CX-9 車身長 4500 mm,尾箱 450 L。
Volvo XC90 車身長 4400 mm,尾箱 400 L。
空間方面,Mazda CX-9 嘅車身比 Volvo XC90 長咗 100 mm,車內乘坐空間會稍微寬敞少少,尤其係後座腿部空間。如果你經常載家人或者需要放嬰兒車,大少少嘅車身確實更實用。
Mazda CX-9 同 Volvo XC90 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更重視品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更在意性價比同配備,嗰就揀配備更豐富嗰款。始終都建議兩款都去試駕,親身體驗先係最重要嘅。
總體嚟講,Mazda CX-9 同 Volvo XC90 都係馬來西亞市場好唔錯嘅車型。揀邊一輛,關鍵仲係要看你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對無錯。

© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


