

HomeToyota

Search History
Popular Searches
Dealer Login / Sign Up
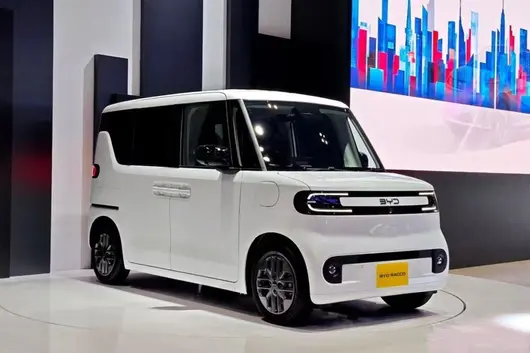
Many people have a stereotype about the Japanese car market, domestic brands firmly hold the core market, making it incredibly difficult for foreign brands to gain even a sliver of share. This impression is mostly correct, but in early September 2026, BYD gave the outside world a glimpse of substantial breakthrough by Chinese automakers in the local market of an automotive powerhouse with a performance report.
BYD Japan disclosed data; in August 2026, the brand's monthly orders reached 1,260 vehicles, setting a new monthly record since entering the Japanese market. Among the six models on sale, the light electric vehicle Raccoon (RACCO) is the core force driving growth. More notably, influenced by the Obon Festival holiday, Japanese dealers averaged only 16 operating days in August. Despite the compressed operating duration, cumulative orders by the end of the month approached 1,500, and foot traffic at authorized stores nationwide continued to rise.
Looking at 1,260 vehicles alone, it's almost negligible in the Chinese market; but placing it within the context of the Japanese market, the weight is completely different.

To understand the value of these 1,260 vehicles, one must first understand what K-Cars mean in Japan.
In 2025, Japan's new car total sales were 4.566 million, of which K-Car sales reached 1.667 million, accounting for 36.5%, meaning one out of every three new cars sold was a K-Car. This is a segment monopolized by three domestic giants: Suzuki, Daihatsu, and Honda, which together hold about 80% of the share. The Honda N-BOX ranked first in K-Car sales for the 11th consecutive year with over 200,000 units sold, even surpassing the Toyota Corolla to become the top-selling model across all Japan.
K-Cars are difficult to compete in because it's not simply about making cars smaller. They have globally unique regulatory standards: vehicle length not exceeding 3.4 meters, width not exceeding 1.48 meters, height not exceeding 2.0 meters, and displacement not exceeding 660cc for fuel versions. More importantly, they are bound to a set of policy benefits. Purchasing a K-Car in core cities like Tokyo and Osaka does not require a certificate of fixed parking space, and comprehensive taxes and fees are only about one-third of ordinary small passenger cars. This means foreign brands wanting to enter must develop an entire platform from scratch for the single Japanese market, with extremely high R&D costs that are hard to spread across sales volumes.
For this reason, for the past few decades, foreign brands have almost collectively been absent in the K-Car segment. BYD's Raccoon, however, is the first foreign brand K-Car developed from scratch specifically for the Japanese market in over 30 years, not an off-brand entry simply resizing an existing model.

If 1,260 vehicles is the result, then the hidden elements in the order structure are more convincing than the sales volume itself.
First, the users are genuine locals. BYD Japan revealed that about 80% of car buyers are new customers encountering BYD for the first time, with more than half previously using Japanese domestic brand models. This means a batch of ordinary Japanese families who originally held a wait-and-see stance or even bias towards Made in China are changing their perceptions through actual experience. As the president of BYD Japan said, "Driving performance, functions, and price make me feel surprised" has become a high-frequency evaluation among customers visiting the store.
Second, the transaction structure shows product power premium, not simply low prices. The Raccoon top-spec 300 Premium version accounts for about 80% of orders, priced at 2.497 million JPY, with a range of 320 kilometers. It is the first lightweight pure electric vehicle in Japan to break the 300-kilometer range barrier. In the order profile, 37.5% were additional purchases, 35.7% were replacements, and only 26.8% were first purchases. That is, many Japanese families actively chose BYD when buying another car or replacing an old one, which indicates the product is truly accepted more than price-sensitive first-time buyers.
1.
It hits the void long ignored by Japanese brands. In 2025, the penetration rate of pure electric K-Cars in Japan was only about 2.8%, and the top-selling pure electric K-Car, the Nissan Sakura, sold only 22,900 units in the whole year. Japanese giants have absolute monopoly on fuel K-Cars but moved slowly in this specific window of electrification. BYD cut in with superior configurations plus range advantages, exactly filling this gap.

If Japan is only treated as an isolated showpiece project, the global significance of this matter is underestimated. The breakthrough in Japan is a microcosm of BYD's overseas territory accelerating expansion.
On the sales side, overseas has become BYD's fastest-growing engine. In 2025, BYD's overseas sales reached 1.0496 million units, a year-on-year increase of over 145%, breaking the 1 million mark for the first time. In the first 5 months of 2026, overseas sales had already reached 614,500 units. Wang Chuanfu revealed at the June 2026 shareholder meeting that he has raised the overseas sales target for 2026 from 1.3 million to 1.5 million, and it is expected to be completed in excess. Looking at the medium to long term, BYD's goal is for domestic and overseas markets to each hold half the share.
On the production capacity side, localized manufacturing is hedging against tariffs and logistics costs. The Rayong Factory in Thailand started production in July 2024, with the 100,000th vehicle rolling off the line in May 2026; the Camaçari Factory in Brazil started production in July 2025, investment amount increased to 5.5 billion Reais, capacity plan expanded to 300,000 units; the Szeged Factory in Hungary plans to start production in Q4 2026, the first model is the Seagull for the European market; bases in Indonesia, Turkey, Uzbekistan, Cambodia, Malaysia, etc., are also landing successively. Phase I production capacity of 8 countries and 8 factories combined exceeds 1 million units, planning total capacity upper limit exceeds 2 million units. The 8 Ro-Ro ships self-built, single trip combined capacity exceeds 60,000 vehicle spaces, also holding the logistics link that blocks the neck of going overseas in their own hands.
This means that the localized breakthrough in the Japanese market is not an isolated case, but a validation of BYD's methodology of using local products and local factories to cover local markets in mature developed markets.
Zooming out, one can understand the connection between this order in Japan and that grand goal.
On June 9, 2026, Wang Chuanfu clearly stated at the BYD 2025 Annual General Meeting: In 5 years, strive to achieve the largest scale globally, and achieve 10 million annual production and sales by 2030. This goal is benchmarked against Toyota—the latter had global sales of about 11.32 million units in 2025, firmly holding the global first place.
From a numerical perspective, this is indeed a hard battle: BYD's 2025 sales were 4.6 million units. To reach 10 million units by 2030, it means the future five years need to maintain a compound growth rate of about 17% on average annually. To catch up with Toyota's volume, it requires an annual average of about 20%. Comparing with BYD's trajectory from 730,000 to 4.6 million units in the past five years, with a compound growth rate exceeding 60%, this growth rate requirement is not a pipe dream, but the difficulty is equally impossible to avoid. Wang Chuanfu himself admitted that the key constraint on the current sales climbing is the capacity of the 2nd generation Blade Battery, and greater capacity release will truly come in 2027.

Auto Car Review:
Of course, the 10 million target is not a done deal. Toyota's global system strength, Japanese and German electrification counterattacks, repeated tariff policies of various countries, supply chain climbing of batteries and chips, etc., are all variables.
But returning to the 1,260 orders at the beginning: What is most worth remembering is not the number itself, but the fact it proves something. In the place where Chinese car companies are hardest to be accepted, BYD, using the way of "respecting local rules, solving local pain points", won the real money of ordinary consumers.
Banyak orang mempunyai gambaran stereotaip mengenai pasaran automotif Jepun, jenama tempatan memegang kukuh pangkalan asas, sukar bagi jenama asing untuk mengimbas sebahagian kecil sahaja. Gambaran ini kira-kira tidak salah, tetapi pada awal September 2026, BYD menggunakan laporan prestasi, membolehkan pihak luar melihat pemecahan sebenar oleh pengeluar kenderaan China di pasaran tanah air negara kekuatan industri automotif.
Pihak BYD Jepun mendedahkan data, pesanan bulanan jenama pada Ogos 2026 mencecah 1,260 unit, merekod tertinggi bulanan sejak memasuki pasaran Jepun. Dari enam model yang dijual, e-Kenderaan ringan RACCO adalah utama pendorong pertumbuhan. Lebih penting, terjejas oleh cuti Festival Obon, hari operasi purata pengedar Jepun pada Ogos hanya 16 hari. Dalam tempoh operasi yang tertekan, sehingga hujung bulan pesanan terkumpul hampir 1,500 unit, trafik pelanggan kedai berlesen di seluruh negara juga terus meningkat.
Jika dilihat 1,260 unit sahaja, boleh diabaikan di China; tetapi dalam konteks pasaran Jepun, nilainya berbeza sepenuhnya.
Untuk memahami nilai 1,260 unit ini, perlu faham dulu apa yang K-Car bermaksud di Jepun.
2025, jualan kereta baru Jepun keseluruhan 4.566 juta unit, di mana jualan K-Car mencecah 1.667 juta unit, jumlah 36.5%, sama seperti setiap 3 kereta baru terjual, 1 unit ialah K-Car. Ini adalah litar yang dimonopoli oleh tiga gergasi tempatan Suzuki, Daihatsu dan Honda, gabungan tiga syarikat ini mengambil kira-kira 80% bahagian pasaran. Honda N-BOX dengan jualan melebihi 200,000 unit secara berturut-turut tahun ke-11 menjadi juara jualan K-Car, malah mengatasi Toyota Corolla, menjadi nombor satu jualan model seluruh Jepun.
Sebab K-Car sukar ditakluki, bukan kerana ia kereta kecil sahaja. Ia mempunyai standard peraturan unik global: panjang kenderaan tidak melebihi 3.4 meter, lebar tidak melebihi 1.48 meter, tinggi tidak melebihi 2.0 meter, sesaran versi bahan api tidak melebihi 660cc. Yang lebih penting, ia mengikat keseluruhan faedah dasar. Di Tokyo, Osaka dan bandar pusat utama lain untuk membeli K-Car tidak perlu menunjukkan bukti tempat letak kereta tetap, cukai dan tol keseluruhan hanya kira-kira sepertiga daripada kenderaan ringan biasa. Ini bermakna, jenama asing yang ingin masuk, perlu untuk pasaran tunggal Jepun ini dari sifar membangunkan satu platform, kos penyelidikan dan pembangunan amat tinggi, skala jualan sukar untuk mencairkan kos.
Oleh itu, dalam beberapa dekad lepas, jenama asing di litar K-Car hampir secara kolektif tidak hadir. Manakala RACCO BYD, tepat tiga puluh tahun lebih model pertama jenama asing yang direka khas untuk pasaran Jepun dari sifar, bukan penyertaan jenama lain yang hanya mengubah saiz model sedia ada.
Jika 1,260 unit adalah hasil, maka apa yang tersembunyi dalam struktur pesanan, lebih boleh dipercayai daripada jualan itu sendiri.
Pertama, pengguna benar-benar tempatan. Pihak BYD Jepun mendedahkan, kira-kira 80% pembeli kereta adalah pelanggan baharu yang pertama kali berhubung dengan BYD, lebih separuh sebelum ini sentiasa menggunakan model jenama tempatan Jepun. Ini bermakna sebilangan keluarga Jepun biasa yang asal berkira-kira malah mempunyai prasangka terhadap pembuatan China, sedang mengubah pemikiran melalui pengalaman nyata - menurut kata-kata Presiden BYD Jepun, prestasi memandu, fungsi dan harga membuatkan saya terkejut menjadi penilaian biasa pelanggan yang datang ke kedai.
Kedua, struktur transaksi menunjukkan premium kekuatan produk, bukan harga rendah semata-mata. Versi premium RACCO 300 Premium kira-kira 80% pesanan, harga 2.497 juta Yen, jarak pemanduan 320 kilometer, adalah EV ringan Jepun pertama dengan jarak pemanduan melebihi 300 kilometer. Dalam gambaran pesanan, 37.5% untuk pembelian tambahan, 35.7% untuk pertukaran, hanya 26.8% untuk pembelian pertama. Iaitu, banyak keluarga Jepun membeli semula atau menukar kereta lama secara aktif memilih BYD, ini lebih daripada pembelian pertama yang sensitif harga menunjukkan produk benar-benar diterima.
1.
Ia menepati ruang kosong yang diabaikan syarikat Jepun lama. 2025, penetrasi K-Car murni elektrik Jepun hanya kira-kira 2.8%, jualan juara K-Car murni elektrik Nissan Sakura keseluruhan tahun hanya terjual 22,900 unit. Gergasi syarikat Jepun mempunyai monopoli mutlak pada K-Car bahan api, namun pada tingkap bahagian kecil pengelektrokan ini tindakan perlahan. BYD dengan konfigurasi tahap atas + kelebihan jarak pemanduan masuk, tepat mengisi ruang kosong ini.
Jika hanya memandang Jepun sebagai kerja muka terasing, maka meremehkan makna global kejadian ini.
Pemecahan Jepun, adalah cermin kecil BYD peta luar negara berkembang pantas.
Dari hujung jualan, luar negara sudah menjadi enjin pertumbuhan paling pantas BYD. 2025, jualan luar negara BYD mencecah 1.0496 juta unit, peningkatan tahun ke tahun melebihi 145%, pertama kali pecah sempadan satu juta. 5 bulan awal 2026, jualan luar negara sudah mencecah 614,500 unit. Wang Chuanfu pada Perhimpunan Agung 2026 Jun mendedahkan, telah menaikkan target jualan luar negara 2026 daripada 1.3 juta unit ke 1.5 juta unit, dan dijangka melebihi tujuan. Pada jangka masa sederhana panjang, target BYD adalah pasaran dalam dan luar negara masing-masing mengambil separuh.
Dari hujung kapasiti, pembuatan tempatan sedang melawan tarif dan kos logistik. Pabrik Rayong, Thailand 2024 Julai mula menghasilkan, 2026 Mei ke-100,000 kereta turun barisan; Pabrik Camaçari, Brazil 2025 Julai mula menghasilkan, pelaburan ditambah kepada 5.5 bilion Real, plan kapasiti berkembang ke 300,000 unit; Pabrik Seged, Hungary plan 2026 suku keempat mula menghasilkan, model pertama adalah Seagull untuk Eropah; Pabrik Indonesia, Turki, Uzbekistan, Kemboja, Malaysia dll juga secara beransur-ansur mendarat. Enam negara lapan kilang fasa satu kapasiti gabungan sudah melebihi 1 juta unit, plan kapasiti jumlah atas melebihi 2 juta unit. 8 kapal RoRo yang dibina sendiri, jumlah kapasiti tunggal kali lebih 60,000 tempat letak kereta, bahagian logistik yang paling menyempit keluar laut juga dipegang di tangan sendiri.
Ini bermakna, pemecahan tersuai pasaran Jepun bukan satu-satu contoh, tetapi BYD menggunakan produk tempatan, kilang tempatan untuk meliputi pasaran tempatan metodologi ini dalam pasaran matang dan maju satu kali pengesahan.
Tarik kamera jauh, boleh faham hubungan pesanan Jepun ini dengan matlamat besar itu.
2026 9 Jun, Wang Chuanfu pada Perhimpunan Agung Tahunan BYD 2025 jelas menyatakan: 5 tahun lagi pada skala berusaha buat nombor satu global, 2030 capai hasil jualan dan jualan 10 juta unit. Matlamat ini menandingi Toyota -后者 2025 jualan global kira-kira 11.32 juta unit, kokoh di nombor satu global.
Dari angka, ini benar-benar satu pertaruhan berat: jualan BYD 2025 4.6 juta unit, untuk 2030 capai 10 juta unit, bermakna lima tahun depan setiap tahun perlu kekalkan kira-kira 17% kadar pertambahan komposit; untuk mengejar tahap Toyota, perlu purata setiap tahun kira-kira 20%. Membandingkan BYD lima tahun lepas dari 730,000 unit ke 4.6 juta unit, kadar pertambahan komposit melebihi 60% lintasan, kadar pertambahan ini bukan hal mustahil, tetapi kesulitan sama tidak boleh dihindari. Wang Chuanfu sendiri juga mengakui, jualan peningkatan kunci sekatan semasa adalah kapasiti Bateri Bilah Gen 2, pelepasan kapasiti lebih besar perlu 2027 tahun akan benar-benar datang.
Ulasan Automotif:
Tentu, matlamat 10 juta unit bukan perkara yang pasti. Kekuatan sistem global Toyota, serangan balik pengelektrokan Jepun dan Jerman, penentu tarif pelbagai negara berulang, bateri dan cip rantaian bekalan peningkatan, semua pemboleh ubah.
Tetapi kembali pada pesanan 1,260 unit di awal: yang paling patut diingat, bukan angka itu sendiri, tetapi ia membuktikan satu perkara. Di tempat paling sukar diterima pengeluar kenderaan China, BYD dengan cara "menghormati peraturan tempatan, menyelesaikan kesakitan tempatan", menang wang tunai pengguna biasa.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


