

Homeoolong

Search History
Popular Searches
Dealer Login / Sign Up
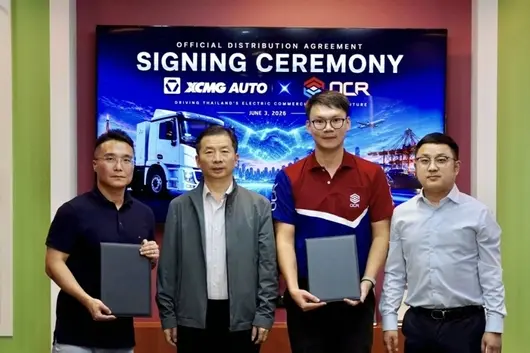
近日,徐工与泰国头部代理商OCR公司在曼谷签署300台新能源商用车采购协议,首批100台已完成交付。徐工集团副总经理,徐工汽车党委书记、总经理夏泳泳出席仪式。
此次徐工与OCR的战略合作,不仅限于整车销售,而是涵盖技术服务、备件供应、金融支持在内的全生命周期价值管理。这意味着,徐工同步嵌入当地的服务网络与配件保障体系,帮助用户降低运营成本、提升出勤效率。

深耕:以全周期服务构建长期价值
2005年,徐工第一台设备驶入泰国港口,与OCR公司携手播下合作的种子。
2025年6月,杨东升董事长出席徐工与OCR合作20周年庆典,通过“产品+场景”的深度融合,双方正携手推动泰国工程机械行业绿色转型,共建绿色可持续的产业发展新生态。
在东南亚,徐工已经建立了完善的服务网络和备件仓库。正是这种从“卖产品”到“全生命周期”的能力升级,成为OCR选择与徐工合作开拓交通运输市场的原因。
攻坚:以技术实力站稳东南亚市场
泰国是东南亚物流枢纽,当前正迎来交通运输绿色转型的加速期。然而当地高温高湿的气候特征,叠加干线物流、矿料转运、城建运输等多元复杂工况,对新能源商用车的考验远超一般市场。

OCR公司作为泰国本土商用车领域的资深力量,积极引导传统车队绿色转型。徐工汽车是中国新能源商用车领先企业,新能源重卡销量连续三年稳居行业第一,凭借成熟的属地化服务网络和良好用户口碑,加之产品卓越的安全性、可靠性、经济性,真正赢得OCR的认可。
依托徐工自主研发的三电核心技术,结合海外专属整车调校与高品控,徐工的产品在高温高湿、路况复杂的实际运营中保持了稳定性和经济性,逐步成为当地绿色运力的示范标杆。

当前,泰国新能源商用车需求正在加速释放。
在全球交通运输绿色低碳转型的进程中,徐工新能源商用车从产品的提供者,转化成为价值创造的建设者。徐工将以此次合作为支点,将“产品+场景”一体化解决方案向更多国家和地区复制推广。

From story to reality.
On Monday, June 8, markets opened. China's three major stock indices continued to decline, visually pleasing but financially distressing…
The last month of the first half of 2026, China's automotive stocks failed to welcome "warmth" at the start, instead struggling bitterly in the falling market.
As investors become increasingly sober, certainty is becoming the only hard currency in a weak market.
01
The first week of June (Week 21 of 2026), "AutosKline" statistics show 117 listed automotive companies on record, with an average stock price decline of 2.86% for the week. Although the decline narrowed significantly compared to the previous week, overall performance remains not optimistic, casting a shadow over the just-started June.
Among them, the number of declining individual stocks reached over a hundred, those rising were less than 30%, and most gains were low.

From the broader market perspective, the Shenzhen Component Index, Shanghai Composite Index, and Hang Seng Index weekly closed down 1.67%, 1%, and 0.88% respectively. Auto stocks significantly underperformed the broader market.
Looking at sectors, six major sectors mostly declined weekly. Only the Distributors/Retail/Aftermarket sector was spared, but achieved only a slight increase of 0.43%.
Among declining sectors, New Energy, Intelligent Mobility, and Passenger Vehicle sectors saw larger declines, with drop rates reaching as high as 5.33%, 3.15%, and 3.04% respectively.
Interestingly, the "Intelligent Mobility" sector was both the "Strong Zone" and the "Hard Hit Zone". Almost both the gainers and decliners lists were dominated by stocks from this sector.
From individual stocks, the "threshold" for the top 10 gainers was only an increase of 5.19%; while the "floor" for the top 10 decliners was a severe drop of 10.99%, showing the intensity of market risk aversion sentiment. Funds are leaving high-valuation, low-profitability growth stocks on a large scale.
02
Specifically, CaoCao Mobility from the Intelligent Mobility sector led the gainers list with a 17.31% increase. Its surge could not be separated from being included in the HKEX Tech 100 Index component on May 29.

Thanks to this, the expectation of passive capital allocation for CaoCao Mobility directly catalyzed the stock price higher. On June 1 and 2, the stock surged 15.38% and 9.14% respectively, laying a solid foundation for CaoCao Mobility's leading rise.
In addition, Huaya Intelligent, UiThinker, Youjia Innovation, and Howon Auto Electronics entering the Top 10 gainers all come from the Intelligent Mobility sector.
Among them, Huaya Intelligent ranked 2nd in the overall gainers list with a 14.14% weekly increase. On June 4, Huaya Intelligent hit the limit up, laying the cornerstone for its weekly trend. Its rise may benefit from SK Hynix's plan to double wafer capacity within five years, as global semiconductor equipment shortage sentiment warms up.
In addition, the dividend plan "10 shares get 2.5 yuan dividend" implemented on the record date of June 8 also played a driving role in short-term buying pressure.
UiThinker may have benefited from partnering with Seres to help the first overseas right-hand drive model Landian E5 Plus mass production in Indonesia, responsible for the mass production development of integrated driving and parking intelligent driving functions, marking that its passenger vehicle intelligent driving solutions possess global delivery capability, pulling stock price higher.
 [Image Source: Youjia Innovation Announcement]
Youjia Innovation may benefit from the planned acquisition of 50% equity of Xi'an Tongtu Technology under ZTO Express, becoming a non-wholly owned subsidiary of the company. This marks that L4 unmanned logistics vehicles have entered the scenario scaling stage from technology validation.
Howon Auto Electronics oscillated upwards, possibly benefiting from NVIDIA having partnered with Unitree Robotics to launch the new generation humanoid robot reference design H2+. Market expectations are that Howon's previously developed robot "brain" in cooperation with NVIDIA is expected to produce synergy, greatly opening the imagination space for this stock.
03
The remaining Top 10 gainers are mainly concentrated in the Distributors/Retail/Aftermarket sector. Medauto ranked 3rd in the overall gainers with a 13.64% weekly increase. Meituan and Medauto Motor Holdings' gains were less than 10%.
Among them, Meituan rose against the current, possibly affected by narrowed losses in the first quarter. On June 1, Meituan announced Q1 2026 financial report. Revenue was about 91 billion yuan, operating losses narrowed significantly from the previous quarter's 16.1 billion yuan to 6.5 billion yuan, and the loss reduction exceeded market expectations significantly.
In addition, Sinotruk HK Stock from the Commercial Vehicle sector and Kai-Zhong Precision from the Components sector also entered the Top 10 gainers.

The rise of Sinotruk HK Stock may be driven by the recovery in heavy truck industry sentiment.
According to China Commercial Vehicle Network data, in May 2026, China's heavy truck market sold about 103,000 vehicles, a 16% year-on-year increase, not only achieving "three consecutive sales gains" but also creating a new record high for May sales in nearly five years.
It is not difficult to discover from the gainers list that verifiable sentiment realization is the most solid foundation for stock prices in a weak market.
Whether it is CaoCao Mobility gaining certain capital inflow due to index inclusion, or UiThinker and Youjia Innovation pushing L4 technology from "concept" to "mass production" through substantial orders and M&A, or Sinotruk benefiting from the real sales "three consecutive gains" in the heavy truck industry, all respond to market doubts with quantifiable and traceable fundamental changes.
04
In contrast, individual stocks purely relying on thematic imagination or liquidity premiums clearly lost ground in this week's fund competition battle.
EHang, Lead Intelligent, Pony.ai, WeRide, and Zhongying Electronic from the Intelligent Mobility sector also became "Hard Hit Zones".

Among them, EHang led the overall list with a 22.29% weekly decline, reflecting the cruelty after the conceptual stock bubble bursts.
On June 4, UBS analysts downgraded its rating directly from "Buy" to "Neutral", with the target price halved from 21 USD to 11.1 USD. The next day, the stock fell nearly 14.46%. The deeper reason is that commercialization progress was far behind expectations.
Worth mentioning, US May Nonfarm Payrolls increased by 172,000 people far exceeding expectations, completely breaking hopes for rate cuts and intensifying rate hike expectations. Tech stocks were dragged down by this and became one of the important factors affecting the stock's trend.
Or affected by this, among the stocks statistics from "AutosKline" with US stocks, except JD.com, stock prices in Week 21 all declined. Polestar, Pony.ai US stocks, and WeRide fell into the Top 10 decliners with drops exceeding 10%. At the same time, Lead Intelligent and Zhongying Electronic also fell into the Top 10 decliners with drops exceeding 10%.
Worth mentioning, from Q1 2026 financial reports of Polestar, Pony.ai, WeRide, and Lead Intelligent, losses all showed an expansion.

In addition, Ganfeng Lithium's decline may be due to lithium carbonate price recovery, with the market completely shaken on confidence in lithium price rebound.
Lirongheng's decline may be dragged down by contract litigation risk. The company announced that the contract dispute with Microvast upgraded bidirectionally. Lirongheng pursued debt of 26.38 million yuan, but was counter-claimed for 129 million yuan by the other party. Additionally, fundraising projects were announced to be extended, further exacerbating market concerns about its operating risks.
Overall, the core commonality of the decliners list is the huge gap between performance and expectations. EHang's commercialization speed was far behind the expectations previously overdrafted by stock prices. WeRide and Polestar still struggle to prove the feasibility of the profit path...
Views of AutosKline:
The rise and fall trend of auto stocks in the first week of June is like the capital market's liquidation of past bubbles and the chase for future certainty.
Especially the clash of being both "Strong Zone" and "Hard Hit Zone" within the same track reveals that capital is accelerating the abandonment of stories that cannot be fulfilled, instead embracing verifiable market sentiment.
Attachment: Weekly Trend of Six Major Auto Stock Sectors (5.29-6.5)


Content is original by [AutosKline]. Content reference material is from listed company announcements and industry public information (related companies and institutions should have an obligation to verify authenticity); some images are from the Internet, and copyrights belong to original owners.
Articles from this account. Without authorization, reprint is prohibited. Violators will be held accountable. At the same time, article content does not constitute investment advice to anyone! Stock market risks are high. Invest with caution!
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


