

HomeNew Energy

Search History
Popular Searches
Dealer Login / Sign Up
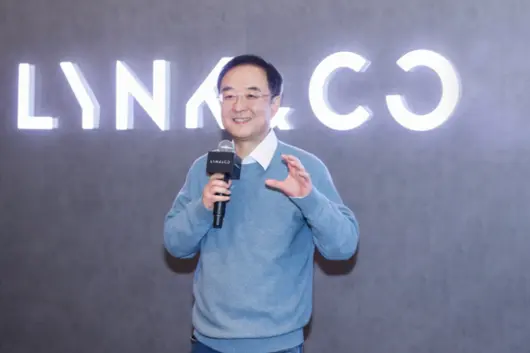
August 17, HKEX issued a notice: Li Shufu stepped down as Chairman of Geely Automobile Board of Directors, An Conghui officially took over, effective August 18.
News broke, industry shook. But this is not retirement and giving up power; it is the founder retiring after achieving success and professional managers fully taking over, the most thorough reform of private automakers "de-familialization". However, for Li Shufu who built the Geely business empire in the industry for decades, why let go now? Will An Conghui taking over cause changes in Geely's New Energy second half?

The Li Shufu Era: A Legendary M&A History, From Grassroots Car Maker to Global Giant
Li Shufu's decades in charge of Geely was a path to glory for a grassroots car maker. Starting from private car manufacturing, breaking foreign joint venture monopolies, forcing a path for Chinese automakers' globalization. He was the founder, M&A maniac, and the absolute creator of the Geely Empire.
$1.8 billion acquisition of Volvo was Li Shufu's most legendary move. The "snake swallowing an elephant" deal that was ridiculed by the public back then is now the most successful overseas M&A for Chinese automakers. This deal directly filled Geely's safety, chassis, and manufacturing system technology, thoroughly getting rid of low-end cheap labels, and obtaining the entry ticket for global high-end car manufacturing.

Furthermore, acquired Lotus core technology and brand assets,守住 the performance sports car track; held controlling stakes in Malaysia Proton, opening up Southeast Asian overseas markets, perfecting the global map. In 2018, invested heavily to enter Daimler, becoming the largest single shareholder, connecting industry top resources, raising Geely's global industry voice.
In technical infrastructure, Li Shufu was also not soft-handed. Built CEVT China-Europe Technology Center, CMA architecture, SEA浩瀚 Pure Electric Architecture, transformed from "assembly car maker" to an independent top brand with self-developed core technology, completing the foundation paving from fuel to New Energy.
Li Shufu was good at cross-border M&A, territory expansion, strategic gambles, helping Geely complete the leap from zero to global top-tier automakers. This was the era of building the land.

The An Conghui Era: Not Playing Capital M&A, Bearing the New Energy Second Half
Who is An Conghui? Core veteran following Li Shufu for many years, not playing capital M&A, focusing on product, operations, landing, New Energy transition pragmatic.
He was not interested in capital M&A and industry hype, always rooted in product, market, user and system construction, was the core operator of Geely's New Energy transition. This takeover was the inevitable result of industry accumulation and strength precipitation.

An Conghui's steering ability had already been verified by market performance. He single-handedly built the Lynk & Co brand, breaking the "domestic high-end must have fierce competition, must have slow sales" industry curse. Not relying on low-price competition, relying on extreme product quality, young user operations, global development thinking,站稳 the domestic high-end fuel car track, becoming the benchmark for domestic high-end brands.
Under the New Energy transition wave, An Conghui took the lead again, incubated Zeekr brand. From Zeekr 001 breakout hot sales, to full series model iteration upgrade, matrix perfect, Zeekr successfully entered the high-end pure electric track, facing new forces and joint venture New Energy brand competition, becoming Geely's New Energy rising core main force.
More rare is, An Conghui is also one of the few managers in the industry who truly understand users and are willing to guarantee users. In the early stage of the industry, New Energy models generally had problems of fast infotainment hardware iteration and old owner experience shrinking, most car companies chose paid upgrades or ignored.

Under his leadership decision, Zeekr officially announced in 2022, for the first batch of Zeekr 001 old owners full free upgrade Qualcomm 8155 infotainment chip assembly, entire upgrade enterprise investment over 300 million yuan, not charging users any hardware and installation fees. At that time's high-end New Energy market, this disregard for short-term costs, prioritizing old owner rights practice, broke industry convention, both filled model intelligence gaps, and also accumulated solid user reputation for the brand, fully showing long-term operation thinking.
In addition, An Conghui long-term led Geely internal system innovation, promoting model refined iteration, vehicle quality control comprehensive upgrade, New Energy strategy landing. Changed Li Shufu's built massive industrial empire from "scale expansion" to "refined operations", letting Geely's every transformation fit market demand, fit user pain points.
Two generations of leaders' handover, essentially was track switch, past relied on strategic expansion to set pattern, now relied on product strength to decide win or lose.

Conclusion: Not a Power Shift, but a Precise Era Handover
For this commander change, I think the most controversial point for outsiders is, Li Shufu stepping down equates to Geely giving up power, going downhill? The fact is, this is just listed company management handover, Li Shufu still holds Geely Group, controlling top-level strategy, belongs to "retired but not resting, behind-the-scenes steering".
Industry contradiction is, old generation car making big shots good at capital expansion, new generation professional managers must face fierce competition. Past relied on M&A to expand map, now relied on product, cost-performance, New Energy, intelligence to fight close combat, era track completely changed.
Final conclusion is clear, that is Li Shufu completed China's auto hardest zero to global foundation, famous and successful, perfect conclusion. An Conghui succeeding, marked Geely officially said goodbye to "wild expansion capital era", entered "product king, New Energy deciding, refined competition" new era.

This is not a power shift, it is a precise era handover, people of the founding land retired, guarding the land, winning second half people took the stage. From our perspective, future Geely's biggest highlight no longer relies on M&A breakout, but watching Zeekr, Galaxy whether can withstand BYD, new forces competition, truly站稳 domestic New Energy first tier.
Do you think, saying goodbye to Li Shufu frenzy expansion era, An Conghui can lead Geely to win New Energy competition war?
Back then, not only was the replacement of new cars slow, but car manufacturing was also very "slow".
In the fuel car era, this may have sacrificed efficiency, but brought quality. In recent years, fierce market competition in the electrification era has forced more and more brands to join the ranks of making "quick-assembly cars", but just in such a frenzied atmosphere, a "global slow car" has arrived.

On August 12, Chery Fengyun T7 officially started pre-sales, with a pre-sale price of 109,900 - 129,900 RMB. This new car went through 2 years of planning, 3 years of R&D, began preliminary research from 2022, and was polished for nearly 5 years.
So, what exactly did Fengyun T7 do during these 5 years?
Visited users in over 5,000 cases across multiple countries globally, creating a great car adapted for global needs
First, one point that needs to be clarified is that Fengyun T7 is a "Global Car".
What is a "Global Car"? A "Global Car" is born for the global market, targeting the global market from the planning stage.
Therefore, before truly starting the R&D phase of a global car, there needs to be a "pre-procedure" — visiting countries around the world, looking at consumers' driving habits worldwide, and understanding what standards each country's regulations and policies are.
During the 5 years of polishing Fengyun T7, Chery Motors completed over 5,000 global user surveys, conducted in-depth visits to 15 typical countries, and wrote down the pain points of global users one by one into the product framework.

Therefore, every detail of Fengyun T7 reflects considerations for different global road conditions, climates, and usage habits. For example, you will find some functions that rarely appear on domestic models, but are actually very useful.
For example, Fengyun T7 uses 4 riveted rings with a load-bearing capacity of 300kg. This is a design common in European cars, used to secure cargo or luggage to ensure items do not slide during high-speed driving or sharp turns.
Furthermore, the use of reflective materials on the center console has been reduced to avoid glare produced by direct summer sunlight, which is very friendly to users living in high-altitude areas, the south, and overseas high-light intensity areas. Meanwhile, a series of parts such as paint surface, interior leather, sealing strips, plastic parts, etc., have all undergone rigorous weather resistance testing, achieving a balance between refinement and durability.

There are also details such as adjusting steering torque to suit Thai right-hand drive preferences for a heavier feel; strengthening steering feel and optimizing return quality for bumpy roads in Indonesia; retaining physical buttons for high-frequency functions for Turkish/Israeli users who prefer hard switches; and designing a central top eyewear box for Australia/New Zealand/South Africa/Southeast Asia users who often wear sunglasses.
In addition, Fengyun T7's styling can also adapt to global aesthetics. After integrating the wisdom of global user co-creation, it was created jointly by the top 10 global design centers and top foreign designer teams, taking into account aesthetic preferences of different regions such as China, Europe/Americas, Southeast Asia, and the Middle East, and at the same time completed a wave of cultural output under the name of "Eastern Aesthetics". Previously, its homologous model Lepas L6 debuted at the Milan Design Week and received consistent praise.

In terms of safety, the vehicle fully benchmarks the 2026 version of E-NCAP 5-star safety design. Functional safety ASIL-D reaches a high level. The body structure uses high-strength steel and hot-formed steel accounting for over 80%. Critical parts are reinforced with 1500MPa class hot-formed steel, forming a "mobile safety fortress". Design optimizations such as shotgun structure, dual frame subframe + Pack crash beam can effectively absorb and disperse collision energy, providing double protection for the battery pack and occupant compartment. In addition, 9 airbags are installed inside the vehicle, effectively reducing secondary collision injuries during a crash.
81 road test vehicles / million km verification, leaving problems before mass production
Before listing domestically, Fengyun T7 was already listed in South Africa and Thailand, ran a circuit in the overseas market for market verification, and then started the pace of listing in China. August in Indonesia; September in EU; October in Australia/New Zealand, UK, Israel, Malaysia. It will continue to promote the pace of overseas listing in the future.
Before entering the listing pace, Fengyun T7 underwent full quality polishing on a global scale.
One point that needs to be clarified is that Chery not only possesses nearly 30 years of automobile manufacturing experience, but has also been ranked first in Chinese brand passenger car exports for 23 consecutive years, with products exported to over 130 countries and regions worldwide.

Currently, Chery's global users have exceeded 20 million. Therefore, Chery not only knows what global users want, but also knows what processes a car needs to go through to truly provide a relatively comprehensive quality guarantee in a real sense. In the past, Chery has fully built a global R&D, global standards, global verification, and global quality integrated car-making system.
Before Fengyun T7 officially went off the assembly line, this car also ran through the tropical extremely humid environment of Southeast Asia. It achieved 500mm off-road waterproofing capability, far exceeding the national standard immersion height of 150mm. It also optimized the air conditioning filter to prevent mold and odors in high-humidity areas. It also ran through the Nordic extremely cold environment and brought a dual-source wide temperature range heat pump + PTC that can operate stably at -30°C and heat up to 23°C within 20 minutes in a -20°C environment. For bumpy road conditions such as gravel roads in Brazil, additional battery front and rear beam protection was added to adapt to overseas complex road conditions.

All in all, Fengyun T7 invested up to 81 exclusive durability vehicles for synchronized road tests, with a total accumulated test mileage of over 6 million kilometers, of which durability special tests were 1.45 million kilometers. It can cover 100+ extreme road conditions environments such as EU, Australia/New Zealand, Middle East, South Africa, Russia, Mexico, Brazil, etc.
This series of rigorous tests and verifications covering different road conditions, environments, altitudes, temperatures, and humidity levels, try their best to discover and solve problems during the testing phase. What is delivered into the hands of users is a reliable, high-quality vehicle that is safe and worry-free to drive.
Six major essentials one step done, easy to drive, fun, and long range
As a car product created through global user co-creation, one of the major features of Fengyun T7 is comprehensive capability.
Being able to meet the six major core essentials of range, safety, intelligence, comfort, driving control, and appearance in one step, it is one of the few car products in this segment level that requires users to make too many compromises.

Appearance meets global aesthetics, safety benchmarks global rigorous standards, and comfortable space meets the seating needs of tall European passengers. In dimensions such as intelligence, driving control, and range, it also has good performance.
In the intelligence dimension, Fengyun T7 is equipped with a 15.6-inch central control screen + 8.8-inch instrument cluster, creating a good cabin technology atmosphere. It is built with a 4nm cockpit-driving integrated 8775 chip, bringing a more fluid interactive experience. Based on 6 personalities of Xiao Qi chat, besides conventional voice control, it can also practice spoken language and accompany chatting, bringing more intelligent and convenient experiences. In addition, CarPlay, HiCar, and CarLink connectivity are also arranged.
In terms of intelligent driving assistance, based on the 3R7V12U hardware solution, the Falcon 500 driving assistance system is equipped, supporting city pilot, and automatic parking functions covering over 300 scenarios + 2km floor-crossing memory parking, which can effectively reduce the burden for drivers.

In terms of driving control, it is equipped with a motor with maximum power 178kW and maximum torque 275N·m, which can meet the power requirements of most scenarios. It combines a 50.8:49.2 golden axle load ratio, 70mm large-sized bushings, One-Box wire control braking system, driving is more stable, braking is faster, lateral inclination suppression is sufficient. The chassis also has an international chassis team led by former Maserati chassis tuning experts for targeted tuning, bringing a better driving experience.
In terms of range, the new car is standard with a 65.05kWh Rhinoceros battery pack, CLTC pure electric range 600km, actual test range 667+km. Charging once every 2 weeks can meet urban commuting travel needs.

In terms of charging, it can charge the battery from 30% to 80% in 20 minutes. And the battery can work normally in -40°C to 60°C. Northern users can drive with confidence in winter.
Final Thoughts:
In the New Energy era, new brands continue to emerge, and market competition intensifies. To adapt to the market pace, quick-assembly models emerge endlessly, but long-term reliable travel quality can never be quickened.
With Chery's 20-plus years of manufacturing experience and global system as the background, Fengyun T7 was carefully polished for 5 years before presenting the final product. It has reliable quality, while also combining high appearance, high safety, high intelligence, large space, excellent driving control, and long range. It is a truly global, all-electric good car that can adapt to global family users.

A toy costing a few yuan triggered a huge storm in late July.
The incident started when a blogger made a bamboo cicada for his daughter, filmed a nostalgic video for the post-80s and 90s generations. Netizens, hearing the "wa wa" sound when shaking the "bamboo cicada", were reminded of Richard Yu's amazed comments on new products at launch events.
Some people made funny videos, paired with captions like "The best toy within 10 million". The videos were mass reported by Huawei Terminal and taken down. Netizens' rebellious emotions were ignited.
"The best toy within 10 million", seemingly a joke, is actually a deconstruction of the AITO M9 promotional slogan. That is, through this joking method, make "The best car within 10 million" completely become a joke.
Huawei's fierce reaction exceeded public expectations, revealing the cruelty of the current car market from the side.
In July, domestic new energy vehicles were still galloping, but under the gallop, another situation was gradually emerging.
Half Joy, Half Concern
The polarization that started in April has greatly deepened by July.
In July, divided by 90,000, car companies were divided into two clear camps. The first tier kept climbing. BYD, SAIC, Geely, Chery, Leapmotor, Changan, six car companies, all achieved year-on-year growth, and month-on-month fluctuation only appeared in SAIC and Geely.
The second tier seemed firmly locked at 40,000 monthly sales. NIO, XPeng, Li Auto, AITO, Hyper, Aion are all like this. These car companies, in July, most did not achieve both year-on-year and month-on-month growth. Especially compared to June, only Hyper Aion saw month-on-month growth.

There is a huge gap between the two tiers. The 6th place Changan is more than twice the 7th place HarmonyOS Intelligent Vehicle, and January-July sales volume reached 3 times. The second tier catching up to the first tier has already become very difficult.
The median and mean further verify this polarization trend. Among the 15 car companies or brands currently announced, the median is 38,027 units, with year-on-year and month-on-year declines of 6% and 15% respectively.
The mean is basically flat with June, with year-on-year growth reaching 28%. Mean growth means overall sales are still increasing. Median decline means car companies in the middle of sales are facing challenges. In other words, the incremental sales were all eaten up by the first tier.
If in the early stage of industry development this is not a problem, but at this stage, for the second tier car companies, days are becoming very difficult.
4 Brands Monthly Sales Break 100,000
Among the 29 brands with announced sales for July, 22 brands achieved monthly sales over 10,000.
Brands that did not exceed 10,000 monthly sales also include BYD Yangwang, Jishi Motors, NIO Firefly, etc. These brands are either special price segment brands, niche models, or new brands, currently in the production capacity climb stage. Excluding these brands, monthly sales over 10,000 is already the basic threshold for sitting at the table, and competition difficulty is increasing.
Among the 22 brands with monthly sales over 10,000, 4 have already broken 100,000 monthly sales. Besides the strong BYD Dynasty and Ocean series, and Geely Galaxy series, Leapmotor became a new member, and Leapmotor is the first new EV maker to break 100,000 monthly sales.
In the below 100,000 yuan price range, there are 11 brands with monthly sales over 100,000. Among them, BYD Fang Cheng Bao sales volume broke 40,000. But it can also be seen that the gap between the two tiers is huge, and brand sales also present extreme polarization. Among numerous brands, breaking through to create a hit is becoming increasingly unlikely.

Under horizontal competition, breaking out becomes more difficult. Vertical achievement of own strategy might bring some comfort, but the reality is, more than half of 2026 has passed, and most car companies' sales target achievement status has not yet broken 50%.
Among car companies that announced annual sales targets, Zeekr's progress is far ahead, completing 71% of the annual target in 7 months. The Galaxy series is also strong, having completed 63%.
Progress on targets for other car companies has not exceeded half, and pressure to sprint for annual targets remains huge. NIO's sales target is relatively small, currently completed 48%. Leapmotor showed bright performance, but the million-unit sales target is large, and the difficulty of completion is high.
Xiaomi's production capacity seems still unable to further improve, maintaining around 30,000 units for 4 consecutive months. To complete the 2026 annual 550,000 unit delivery target, it needs to wait for further production capacity pull-up.

From sales performance, it can be seen that the Matthew effect is very obvious. Whether car companies or sub-brands under car companies, polarization is obvious, and the gap between the two tiers is huge.
Continuation of this situation makes survival status increasingly poor for car companies with weak sales growth.
At the current stage, car company costs are continuously increasing. Seres founder Zhang Xinghai previously gave detailed data. Storage chip price increase rose up to 5 times, lithium carbonate price climbed from 80,000 yuan/ton to 180,000 yuan/ton last August. Dual raw material price increase directly led to AITO single car manufacturing cost increase of 15,000 to 20,000 yuan. Under this situation, profits of most car companies are squeezed significantly.
Data from CPCA shows that January-June auto industry profit margin is 3.8%, downstream industrial enterprise profit margin is 6.5%. Auto industry is obviously still relatively low.
Closing in on Q2 financial report season, many car companies disclosed profit forecasts. The second-tier Seres, GAC, BAIC BluePark all showed losses. Among them, GAC expected loss 4.06-4.57 billion yuan, BAIC BluePark expected loss 1.795-1.995 billion yuan, Seres expected loss 1.5-1.8 billion yuan.
Price reduction means further profit pressure, which might directly threaten operational stability.
Moreover, even with price reduction, it does not equal sales growth. On one hand, the incremental era is heading towards its end.
"Oil-Electricity Equal Rights" curtain opens. Starting from January 1, 2027, energy saving cars half levy car and vessel tax policy, and pure electric commercial vehicles, plug-in (including extended range) hybrid cars, fuel cell commercial vehicles car and vessel tax exemption will be cancelled. This means, the new energy vehicle car and vessel tax preferential policy implemented for 15 years officially enters withdrawal countdown.
Preferential policy cancellation will also cause consumption willingness to slide, and car companies' incremental space will further shrink.
On the other hand, the market is already very internalized, everyone is reducing prices in disguise. Car companies are not conducting price wars on the surface, but secretly all lowering prices and increasing configurations. Data from CPCA shows that January-June, new energy vehicle new car discounted model average price 247,000 yuan discount force arithmetic average reached 30,000 yuan, discount force reached 12%.
Technical innovation is not necessarily a panacea. An innovative product design will quickly become a standard. Relying on one technology or product design to gain excessive market returns has become very difficult.
Under this situation, many car companies' stock prices continue to fall, and car companies have to buy back to maintain stock prices.
SAIC Group announced controlling shareholder promises not to reduce shares held in any way within 6 months. Seres has already bought back 8.9755 million shares, using fund total 587 million yuan. JAC Motors has already bought back 1.5467 million shares, using fund total 34.9948 million yuan.
Under this cruel situation, car companies' survival status is not good, and seeking overseas growth has also become a must-have option.
Going Overseas: New Forces Set Sail
Overseas markets are still led by traditional car companies.
Chery is still the navigator among overseas car companies, and growth momentum is very fierce. According to listed company caliber, Chery July overseas sales 196,300 units, has achieved "walking on two legs". This sales volume is 5th consecutive month breaking historical high.
BYD is closely chasing, July overseas sales 179,800 units, 4th consecutive month breaking historical high, consecutive 9 months sales breakthrough 100,000 units. If only looking at new energy vehicles, BYD might have already led.
In July, BYD Brazil factory 100,000th new energy vehicle officially rolled off production line, factory on-job employee scale reached 5,500 people. Denza's first hypercar listed in UK, Denza Z starting price 1.3 million yuan, global pre-sale orders over 1,000 units. BYD new energy vehicles in Thailand market cumulative delivery volume officially broke 130,000 units.
Currently, BYD is strengthening global influence. The group reached global strategic cooperation relationship with Paris Saint-Germain Football Club (PSG). Both sides will promote cooperation landing through global communication activities, fan interaction forms, etc.
Geely although not rapid growth, also broke 100,000 units for 2 consecutive months, 7th consecutive month breaking historical high. This is a very strong performance. In addition, Great Wall also created new high for 4 consecutive months.
Although SAIC failed to break new high, it has also been stabilizing monthly sales over 100,000 units for consecutive 5 months.

Say, traditional car companies are ushering in a comprehensive explosion in overseas markets. To a certain extent, this can alleviate the tight domestic state.
New forces also saw huge potential in overseas markets. Since this year, car companies such as NIO, XPeng, Li Auto have obviously accelerated overseas layout actions.
XPeng announced its Australia long-term strategy, planning to introduce XPeng high-level intelligent assisted driving locally in 2027. In addition, XPeng Australia New Zealand subsidiary will launch 5 new models within 6 months, and plans to layout 3 flagship tech experience centers and 50 outlets in Australia.
Besides Australia, XPeng also held Mona L03 launch event in Munich, Germany. Planned to land in 65 countries and regions this year, expanding XPeng Group international product lineup.
Li Auto cooperated with Kazakhstan local car group Allur to reach strategic cooperation, will utilize Allur Kostanai factory to start local assembly production. All new Li Auto L9 also listed in Kazakhstan in July, pricing far exceeded domestic.
Leapmotor B10 completed Mexico localization certification, officially landed local market and started delivery, opening North American market expansion process. Currently, Leapmotor B10 has entered Mexico local stores. Leapmotor C10, C16 will also gradually enter market.
Overseas competition has become the only way for car companies. In the stage where domestic market polarization is obvious and market pattern gradually stabilizes, overseas vast markets may become the key to the next stop for car companies.
Xiaomi Overturns Table, Volume Models Released Dense
July is not a big month for product launches. Many car companies put volume models into July launches.
This month's highlight is Xiaomi.
On the night of July 30, Xiaomi Pengcheng held a technical launch event, releasing 2 new cars. Equipped with Xiaomi self-developed Kunlun Extended Range Engine, fuel compatibility performance is broad, can add 92, 95, 98 different grade gasoline. Under WLTC working conditions, Pengcheng N70 lowest fuel consumption is 5.7L/100km, CLTC pure electric range highest can reach 505km, full oil full electricity comprehensive range all break 1,500km.
Lei Jun also focused introduced rear row variable diverse cockpit scene, seats support front row 180° rotation, second row horizontal movement.
The most explosive is price. N90 Max pre-sale price 299,900 yuan, N70 Max pre-sale price 259,900 yuan. Two new cars will be officially launched in September. According to usual laws, new cars might further lower prices. This means, this 9-series full-size SUV has been pressed to within 300,000 yuan by Xiaomi. For AITO M9, Li Auto L9, Zeekr 9x, NIO ES9 and other competitors, it might be a considerable shock.

However, some netizens questioned, new cars put 400V platform on 300,000 class flagship models, no rear wheel steering, no steer-by-wire chassis, battery supplier downgrade, electric drive and intelligent driving hardware intentionally diluted in launch event. But from current market reaction view, Xiaomi Pengcheng will likely give this already very fierce market, add another layer of fire.
Except Xiaomi, other hot car companies also released volume models.
NIO series Firefly announced, Halo Xunguang series first model "Habitat" officially launched, whole vehicle price starting at 133,300 yuan.
XPeng MONA L03 launched 9 models in China market, price 123,800 to 156,800 yuan. L03 positioning compact SUV, providing pure electric and extended range two power.
Leapmotor new B series officially launched. B10 positioning pure electric compact SUV, B01 positioning pure electric compact sedan. Full series standard equip Qualcomm SA8295P chip, all-domain 800V SiC high pressure system + 3C fast charge etc. B10 price starting at 99,800 yuan, B01 price starting at 95,800 yuan.
New generation Li Auto L6 officially launched, only providing Ultra one version, national unified retail price 249,800 yuan.
Traditional car company aspect, Geely series Lynk & Co 07GT officially launched, releasing 4 models. Geely Galaxy TT Ultra officially opened pre-sale, new car positioning pure electric mid-large sedan, Ultra is high config version, later will also supplement price lower models. Zeekr 9X 5-seat version officially launched.
Dongfeng series Voyah Pursuit Light S published quad drive top config model, pre-sale price 309,900 yuan. Later will also supplement long range rear drive version and standard range version. New car positioning pure electric mid-large SUV, product orientation more lean towards young and sports.
BYD Ocean network series Seal 08 officially launched, new car releasing 6 configurations.
Time enters Q3, car companies' second half year sprint is about to open curtain. Considering relevant subsidies start reducing, this half year will be manufacturers' last timing to sprint sales.
Fighting for "Domestic BBA"
"NIO, XPeng, Li Auto" these three new forces sales comparison is becoming meaningless.
On one hand, Leapmotor's sudden appearance, made three car companies become the second game of competitive new forces. On the other hand, XPeng, NIO layout in low price segment, three new forces are no longer mid-high end, luxury car sales direct comparison.
First half year, Li Auto, AITO, NIO, Zeekr, launched fierce battle in full-size SUV, 400,000 yuan above luxury car price segment. These four car companies are currently accelerating grabbing BBA customers.

This trend started with Li Auto L9. Relying on precise grasp of dad and baby family demands, Li Auto car first tested the water. From June 2022 first unit delivery to June 2026, Li Auto L9 completed 300,000 units cumulative delivery in 4 years. Early, Li Auto could rely on one model to hard resist NIO, XPeng. Precise layout on dad market was key.
AITO pushed this market to climax. September 2023, AITO M9 suddenly appeared, 100,000 units sold in a year, consecutive 21 months toping 500,000 yuan above luxury car sales first place.
Before a few years, relying on early layout, intelligent driving and cockpit field leading, AITO and Li Auto enjoyed market dividends. But market pattern will not remain unchanged. AITO M9 and Li Auto L9 lead advantage will soon be caught up.
Zeekr's success comes from 9X and 8X success. Since listing on September 29, 2025, 9X in China 500,000 yuan class high-end SUV market segment, has been toping sales list for 7 consecutive months. This May, Zeekr 8X sales 6,103 units, grabbing transaction average price 300,000-500,000 yuan interval hybrid SUV sales first place.
NIO is following slowly, ES8 and ES9 launched successively. NIO's advantage lies in its battery swap products. Through BaaS rent power mode, NIO pressed ES9 starting price to within 400,000 yuan. July, NIO ES9 also achieved good sales. New ES8 reached 130,000th unit delivery in 305 days. NIO ES9 since May 28 started delivery, 30 days delivery broke 10,000 units, refreshed 500,000 yuan above high-end pure electric vehicle fastest delivery record.
From sales view, in mid-high end and luxury car price segment, July, Zeekr ran to front. Li Auto, AITO, NIO main brands closely chasing. These four car companies' current difference is not big.
Which of these four will be Domestic BBA, or whether these four can all be Domestic BBA, has become more interesting to watch.
Volume Sales, Difficulties All Over
Compared to mid-high end struggle, price reduction seems the simplest option for new forces.
XPeng exiting Mona series, NIO launching Onvo series, Firefly series, are all precise snipers to sales.
But from result side, mass consumer market is not a market where you take what you want. Even positioning mid-high end, does not mean these car companies can use low price to snatch other car companies' shares.
Taking NIO as example, it launched 100,000-200,000 yuan price segment Onvo brand, 100,000 yuan below Firefly brand. But until July, Onvo contribution sales was 10,155 units. Stable above 10,000 units for 3 consecutive months, but recent 2 months month-on-month both showed decline. Firefly similarly struggled to start, until now failed to break monthly sales of 10,000.
XPeng did not announce Mona series contribution sales, but from XPeng's overall sales view, still did not break 40,000 units threshold. Therefore, low price might relieve sales pressure in short term, substantial sales changes still need long process.
This point is also reflected in Hyper Aion traditional car company brand merchants. Once, Aion sales exceeded NIO, XPeng, Li Auto. But in current stage development, gradually lost speed. July sales 34,987 units, still in flat state.
This point Geely and Leapmotor performed better. Leapmotor does not rely on brand, but is truly high price low config. July, Leapmotor sales first time stood on 100,000 units, consecutive 4th month sales creating historical high, throwing other new forces far behind.
Geely Galaxy is also embodiment of product power. Focusing on friendly commute, home rigid demand, focusing on high cost-performance, low usage cost and reliable quality. July sales 107,800 units, consecutive 2nd month breaking 100,000, becoming a strong challenger to BYD.

Mass consumer market, brand is perhaps not the most important factor, higher cost-performance, more reliable product experience.
Xiaomi, HarmonyOS: Internet Car Companies Growth Troubles
Xiaomi and Huawei are both facing their own troubles.
July, Xiaomi sales still stopped around 30,000 units. This of course relates to production capacity. But in December last year, Xiaomi's production capacity was once pulled to 50,000 units, and once consecutive 3 months broke 40,000 units. Now Xiaomi still controls production capacity at 30,000 units, still not well digesting orders. Since this year, Xiaomi's stock price has fallen 30% from peak period, huge pressure.
Same situation HarmonyOS Intelligent Vehicle also encountered. July, HarmonyOS Intelligent Vehicle sales 45,046 units. After May 20,000 in June, it dropped back to 40,000. This is far from the limit of HarmonyOS Intelligent Vehicle. In recent years, HarmonyOS Intelligent Vehicle's "friends circle" continuously expanded. Now there are already "Five Worlds Three Realms", but at current stage, this ecosystem performance is not optimistic.
AITO needs not say. AITO-led Seres car sales only 20,480 units. Sales returned to March water level. Ambitious Luxeed, started delivery in May, until July barely reached 20,000 unit delivery. Stelato cooperating with Chery, finally broke 10,000 this month, reached 10,709 units, but still did not break new high.
Under low sales momentum, cost cooperating with Huawei is becoming prominent. In 2025, Seres paid Huawei over 20 billion yuan procurement fee. These rigid cost expenditures are increasingly eye-catching under current situation.
July, Seres released Q2 loss warning. Among them, AITO car 2026 half-year deduct non-net loss reached 1.7-1.95 billion yuan. HarmonyOS insists on high-end route. Under normal conditions, car companies' profit margin has guarantee. But with supply chain price rise, car company competition intensifies, enterprises on HarmonyOS industry chain face operation pressure.
Facing current situation, Xiaomi gave solution. Launching extended range brand Pengcheng, opening sales again through new products. However, this heat maintained through freshness will eventually return to calm. Xiaomi and Huawei have walked through dividend period. Need stronger product power.
Fierce competition is indeed the current reality of new energy car companies. For many car companies, this is a difficult cycle. But continuously evolving Chinese car companies are comprehensively realizing overtaking on the curve.
Chinese car companies' difficulty is the difficulty of walking uphill. Compared to this, since this year, traditional luxury car three giants BBA (Mercedes-Benz, BMW, Audi) collectively reduced prices. Japanese car companies three strong (Honda, Toyota, Nissan) first half year China sales collectively declined. Among them Honda year-on-year declined 34.7%. Under big trend, Chinese car companies are grabbing territory of old forces, grabbing era opportunity. Need technology and experience more surpassing the era. This is a process. This difficult situation will eventually gradually be overcome.
Chery Group July new energy vehicle sales hit a new high again, reaching 129,067 units, with a year-on-year increase of 97.5%, approaching a doubling. From January to July, Chery Group cumulatively sold 604,305 new energy vehicles, a year-on-year increase of 42.3%, breaking 100,000 units in a single month for four consecutive months. According to data released by the China Passenger Car Association, Chery has ranked in the top three in the industry for new energy wholesale volume for four consecutive months.

Scaled development enters a boom period, ranking in the top three in the industry for wholesale volume for four consecutive months
From stabilizing at 100,000 units to successively breaking through 110,000 and 120,000 units, and then approaching 130,000 units, Chery Group new energy vehicles maintain high-speed growth, and scaled development has entered a boom period. So far this year, Chery Group has cumulatively sold over 604,000 new energy vehicles.
According to the July passenger car main manufacturer new energy wholesale volume sales bulletin released by the China Passenger Car Association, Chery ranked third in the industry. Thus far, Chery has ranked in the top three in the industry for new energy wholesale volume for four consecutive months this year.
New energy transformation accelerates, domestic penetration rate exceeds 60%
New energy has become a new label for Chery Group. In July, Chery Group's total sales were 276,820 units, of which new energy vehicle sales were 129,067 units, and the overall new energy penetration rate steadily climbed to 46.6%.
New energy is already the absolute main force of Chery Group in the domestic market. In July, Chery Group's domestic new energy sales were 46,044 units, with a new energy penetration rate of 62.0%. For every three vehicles sold by Chery Group in the domestic market, two are new energy.

Figure: Fengyun A9

Figure: New QQ3
New energy is also an important growth pole for Chery Group's expansion into overseas markets. From January to July, Chery Group's new energy exports grew by 175.7% year-on-year, more than double the overall export growth rate. In the first half of the year, Chery sold 86,000 new energy vehicles in Europe, a year-on-year increase of 385%, accounting for about half of the sales in Europe, meaning Chery's new energy penetration rate in Europe is already around 50%.
Hit product matrix formed, winning global user love
More and more global users are choosing Chinese new energy products, choosing Chery new energy vehicles. Chery has currently formed a new energy hit product matrix both domestically and overseas:
In the domestic market, the new QQ3 broke 10,000 sales for four consecutive months; Fengyun A9 pre-orders exceeded 31,000 units in 15 days; iCAR V27 firmly held the monthly sales champion in the 200,000-level extended-range SUV segment; the high-end new energy MPV Luxeed V9 delivered over 10,000 units in a single month.
In the overseas market, JAECOO 7 topped the UK monthly all-market sales first place, JAECOO 5 was the champion in the Australian BEV small SUV market, Indonesian and Thai BEV markets, iCAR V23 took the first place in the box-style SUV sub-segments in South Africa, Thailand, and Nepal.

Luxeed V9 single-month delivery exceeded 10,000 units

Figure: JAECOO 7 New Energy Vehicle Model
Consolidating the "Battery Pillar", building a strong new energy safety and charging foundation
The dual growth of sales and penetration rates cannot be separated from the continuous breakthrough of new energy core technologies. Chery's "Battery Pillar" is being continuously consolidated. Currently, Chery's battery layout covers two material systems: ternary lithium and lithium iron phosphate, three cell structures: short blade, prismatic, and large cylindrical, and three product series: dedicated hybrid, dedicated pure electric, and dedicated solid-state. Chery's Rhino solid-state battery cell energy density has reached 400Wh/kg, aiming for 600Wh/kg. By the end of 2025, Chery Rhino battery-equipped vehicles have cumulatively driven over 1.2 billion kilometers, with the highest single vehicle at 160,000 kilometers, delivering a market report of "0 spontaneous combustion, 0 battery safety incidents".
Chery has won continuous authoritative recognition in the battery safety field. In July, at the National New Energy Power Battery Safety Warning Algorithm Competition hosted by the Technical Innovation Center of the State Administration for Market Regulation, Chery Group won three first prizes in both ternary lithium and lithium iron phosphate tracks; meanwhile, it passed the industry's first six-vehicle major serial extreme tests implemented by the China Automotive Technology and Research Center, verifying safety capabilities in extreme environments.

Figure: Fengyun A9 undergoing whole-vehicle six major serial extreme tests
Battery safety is the bottom line, while charging efficiency is key to user experience. Chery's "Xunlong Instant Charge" energy technology is promoting the transformation of new energy vehicles from transportation tools to mobile energy nodes; Rhino batteries support charging for 8 minutes with a range of 500 kilometers, ready to set off after a cup of coffee. Chery plans to build over 20,000 charging stations supporting V2G functionality before 2029.
From ranking in the top three in the industry for new energy wholesale volume for four consecutive months to domestic penetration rate exceeding 60%; from a complete hit product matrix both domestically and overseas to continuous battery technology breakthroughs, Chery Group is entering the fast lane of brand elevation with a high-quality new energy transformation.
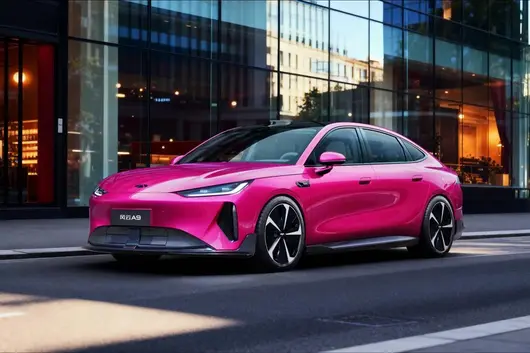
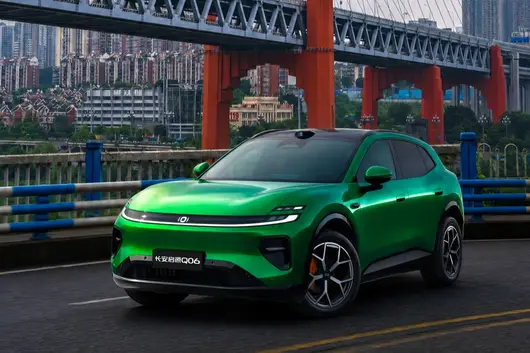
Facing an increasingly competitive new energy market, Changan Qiyuan maintained a steady rhythm in July: delivered 39,841 vehicles in July, AQ series increased by 103% year-on-year, continuously holding the top sales position among new energy vehicle brands of central state-owned enterprises. Together with brands such as Geely Galaxy and Leapmotor, it forms the backbone of the mainstream camp in China's new energy market.

The steady growth of Changan Qiyuan in July is the result of both product strength and user reputation. From the continuous hot sales of the main models of the Changan Qiyuan AQ series, to the global debut of the Changan Qiyuan Q06, to the Changan Qiyuan new Q05 accelerating towards the overseas market, the label of "SOE New Energy" is transforming from brand endorsement to a tangible quality perception in users' minds.
Global Flagship Product Changan Qiyuan New Q05 Leads, Champion Matrix Collaborates
As the first global flagship product of Changan Qiyuan, Changan Qiyuan new Q05 leverages "CATL Batteries, Premium Frame, Ultra-Comfort" and other cross-class advantages, cumulative sales exceeded 100,000 units, continuously leading the compact SUV sub-market. In overseas markets, after launching in Thailand and Uzbekistan, Changan Qiyuan new Q05 further landed in Ethiopia, accelerating the formation of an overseas layout linking Southeast Asia, Central Asia, and African markets.
While Changan Qiyuan new Q05 exerts global momentum, the AQ series saw a 103% year-on-year increase in July, forming a synergistic growth "Champion Matrix". Among them, Changan Qiyuan A06 is positioned as the "King of Fully-Configured New Energy Family Sedans", with cross-class configurations such as 145° Electric Zero-Pressure Rear Seat, 800V 6C Fast Charging, etc., holding the sales champion of medium-to-large new energy sedans within 200,000 RMB; Changan Qiyuan Q07 satisfies family travel needs with "Space King" strength, cumulative sales have exceeded 100,000 units since launch, maintaining leading position in the mid-size plug-in hybrid SUV market.
Changan Qiyuan Q06 Global Debut, Defining New Standards for Mid-size SUVs with "Flowing Light Aesthetics"
On July 15, the all-new mid-size SUV Changan Qiyuan Q06 completed its global debut in Shanghai. This model, led by the world-class design master Klaus team, breaks the traditional mid-size SUV dull impression with its unique "Flowing Light Aesthetics" design. Inside the cabin, the "Flowing Light into Cabin" concept creates a high-quality immersive space, integrating technology and comfort.

In the field of intelligent driving, Changan Qiyuan Q06 is equipped with the Tianshu Pilot Ultra Intelligent Driving System, possessing end-to-end urban pilot capabilities, making vehicle control closer to the driving texture of veteran drivers. The chassis adopts luxury-grade chassis suspension with all-aluminum front double wishbones + rear multi-link and the only dual-motor rear-wheel drive layout in the class, balancing comfort and driving fun.
Conclusion
Steady sales and a complete product matrix form the core foundation of growth. In the future, Changan Qiyuan will continue to rely on the strength of Changan Automobile's central state-owned enterprise system, with a more competitive product matrix and global layout, to continuously meet users' expectations for high-quality new energy travel.
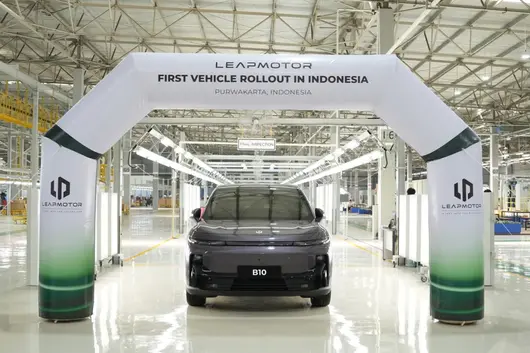
The 2026 Indonesia International Auto Show officially kicked off. Chinese smart electric vehicle brand Leapmotor appeared with global flagship models Leapmotor B10 and C10, announcing its entry into the Indonesian market. The simultaneous local KD assembly plant production plan is a significant milestone in Leapmotor's Southeast Asian localization production strategy. Leveraging full-domain self-developed technology and local channel resources, Leapmotor uses Indonesia as a core fulcrum to build a new energy industry layout covering the entire ASEAN region.
The B10 and C10 landing in Indonesia this time are strategic models built by Leapmotor for the global market, precisely aligning with the core needs of Indonesian family travel. Spacious interior space and a full suite of smart in-vehicle configurations have become the core competitiveness of the two models. Supporting the product differentiation advantage is Leapmotor's long-term full-domain self-research route. Core parts independently developed and manufactured by the brand account for over 65% of the total vehicle cost, covering key vehicle sections such as electric drive systems, power batteries, smart cockpits, and central electronic/electrical architecture. This highly vertically integrated self-research system not only continuously compresses R&D and manufacturing costs but also allows Leapmotor to quickly iterate electrification and intelligence technologies, providing product solutions adapted to local road conditions and driving habits for overseas markets.

Local manufacturing is Leapmotor's core lever for deep diving into the Indonesian market. Leapmotor reached deep collaboration with Indonesia's local top enterprise Indomobil Group, leveraging its subsidiary PT National Assemblers to build KD semi-knocked-down assembly lines. This production base located in Bekasi was completed for production and debugging as early as April 2026. The first batch of locally assembled B10 and C10 models will be officially delivered to Indonesian consumers in August 2026. With the Indonesian KD factory landing, Leapmotor simultaneously possesses two major Southeast Asian local production bases in Malaysia and Indonesia, becoming one of the few new energy vehicle enterprises in the region with dual KD manufacturing capacity. The local production model not only shortens vehicle delivery cycles and avoids cost pressure brought by whole vehicle import tariffs but also drives the development of the local automotive supply chain in Indonesia, creates a large number of technical jobs, and achieves two-way empowerment of brand development and local industrial upgrading.

A complete sales service network is an important support for overseas market development. Leapmotor leverages dual cooperation resources to build a service system covering all of Indonesia. On one hand, relying on Stellantis Group's mature brand house operation model, Leapmotor entered local Stellantis brand showrooms, displaying and selling alongside well-known models like Jeep and Citroën in the same store, creating a one-stop car viewing, buying, and maintenance service scenario. On the other hand, relying on Indomobil Group's distribution channels deeply cultivated in Indonesia for years, its subsidiary PT Indomobil National Distributor is fully responsible for retail layout. The brand plans to build 50 offline outlets integrating sales, after-sales, and maintenance in Indonesia by the end of 2026, eliminating channel concerns for local consumers purchasing new energy vehicles.

Entering the Indonesian market is also a key result of the landing of Leapmotor and Stellantis's global strategic cooperation. Both parties reached capital cooperation in 2023, and in 2024 formed an international joint venture focusing on overseas markets. Relying on multinational group global channel resources, Leapmotor products are now sold to over 40 countries globally, offline sales outlets exceeded 2,000, and global cumulative vehicle delivery volume exceeded 1.5 million units. Facing long-term development in Southeast Asia, Leapmotor has set a clear product iteration rhythm, planning to launch a new model for the ASEAN market every year, continuously enriching the pure electric and extended-range dual-line product matrix, covering consumer groups with different price points and usage scenarios.
The landing of this Indonesian market is not just a simple expansion of Leapmotor's overseas territory but also a brand new practice of the localization overseas model for Chinese new energy vehicle enterprises. In the future, Leapmotor will continue to deepen collaborative cooperation with Stellantis and Indomobil local partners, centered on the Indonesia manufacturing base, linking markets of various Southeast Asian countries, building a complete localized R&D, production, sales, service electric mobility ecosystem, letting Chinese new energy vehicles with both high cost-performance and cutting-edge intelligent technology benefit more ASEAN household users, continuously conveying a brand new lifestyle of green smart mobility.
July 28, 2026, the highly anticipated Fortune Global 500 list was grandly released! BYD proudly made it to the list again; this is already the brand's fifth consecutive year joining the world's top 100. This time ranked 91st, firmly standing within the global top 100 elite enterprise camp, a benchmark enterprise for global new energy vehicles, continuously demonstrating the core strength of Chinese new energy enterprises!

Momentum soaring, full of achievements! In 2025, BYD delivered a report card sufficient to astonish the industry, with annual revenue reaching a high of 804 billion yuan, and net profit breaking through 32.6 billion yuan. Operating performance steadily climbed, with a thriving momentum! In the core sales track, BYD's annual new energy vehicle sales broke 4.6 million units, winning both the global new energy vehicle sales champion and the China market auto sales champion titles, firmly standing at the core position of the global new energy vehicle benchmark enterprise! Entering 2026, brand popularity and market momentum continued unabated, with cumulative sales in the first half successfully breaking 1.8 million units, showing very strong growth momentum! More worth cheering about is that in the same month of July, BYD welcomed a historic highlight moment—the brand's 17 millionth new energy vehicle went off the line smoothly, becoming the first auto enterprise globally to unlock this milestone achievement, once again refreshing industry records and creating a new legend!
Deep cultivation in the innovation track, sticking to the original intention of technology! Since development, BYD has always held the core development concept of "Technology is King, Innovation is Foundation", driving continuous brand iteration and leading the industry with ultra-high intensity R&D investment! In 2025, BYD's R&D investment was heavily weighted to 63.4 billion yuan, a year-on-year surge of 17%. Relying on core R&D strength, it won the top spot in R&D investment among A-share listed companies for two consecutive years, firmly securing the first place in the industry! In the first quarter of 2026, brand R&D investment reached a new high again, single quarter investment of 11.3 billion yuan, far leading domestic mainstream automakers and top new energy forces, R&D courage is unquestionable! As of now, BYD's cumulative R&D investment has forcibly broken through 250 billion yuan. Long-term, continuous, and high-amount technology deep cultivation has allowed a series of disruptive frontier technologies to accelerate implementation and iteration!
Innovation results blooming everywhere, black technology empowering universal mobility! In March 2026, BYD heavily released the second-generation Blade Battery and brand-new super-fast charging technology, completely revolutionizing the new energy mobility experience with breakthrough technologies. Meanwhile, planning to complete the layout construction of 20,000 super-fast charging stations nationwide by the end of the year, comprehensively improving the domestic energy replenishment system! Not only deepening the domestic market, BYD is also fully laying out the global energy replenishment network, planning to land 6,000 overseas super-fast charging stations, letting the convenience of Chinese intelligence benefit global users! In May of the same year, BYD once again led industry change, being the first to announce a full one-year comprehensive backing guarantee for city navigation safety, while realizing the entire series models can be equipped with the Divine Eye B Assisted Driving Laser Version, breaking industry barriers in one move, officially opening the era of universal city navigation accessible to everyone!
Setting sail overseas to expand territory, global layout momentum like a rainbow! Relying on solid product strength and brand reputation, BYD's globalization development pace accelerated to full speed, overseas market performance welcomed explosive growth! In 2025, BYD's overseas sales successfully broke through the 1 million unit mark for the first time, surging 145% year-on-year, growth speed was very astonishing! In the first half of 2026, the overseas hot-selling trend continued to extend, sales easily broke through 780,000 units, overseas market recognition continued to skyrocket! Nowadays, BYD has successfully created a new pattern of "Latin America leading, Europe breakthrough, Asia-Pacific multi-point blooming" globalization development, overseas version continuously expanding, blooming everywhere!
Many overseas landing results are bright and eye-catching: Brazil's first overseas SkyRail officially opened for operation smoothly, Brazil factory successfully completed the 100,000th new energy vehicle off the line milestone; Denza Z, Z9GT, D9 three car models joined forces to land in the European market, reshaping the European high-end new energy mobility pattern, opening a new chapter of Chinese automotive European technology luxury! The brand-new model Otter (BYD RACCO) developed specifically for overseas markets officially landed in Japan, accurately deepening the niche market; Thailand factory also fully welcomed the two-year anniversary of production, localization operation becoming more and more mature! As of now, BYD business version has covered 121 countries and regions globally, formally entering a new stage of globalization with localized deep cultivation and high-quality advancement!
Holding responsibility to travel far, green responsibility empowering the future! On the dual carbon development track, BYD has always practiced sustainable development concepts with a green original intention, delivering a stunning environmental protection report card! Data shows, as of June 30, 2026, BYD new energy vehicles compared to traditional fuel cars, in energy production and usage links cumulative achieved 149 million tons carbon emission reduction amount, equivalent to planting 2.48 billion trees, using core strength to contribute Chinese power for global carbon reduction and ecological protection!
On the path of social responsibility practice, BYD is also not stopping steps, moving forward with great love! The brand heavily set up a 3 billion yuan education charity fund, partnering with 127 universities nationwide to achieve public welfare donation cooperation, cumulatively incentivizing and helping more than 6,000 students chase dreams forward, empowering education development with public welfare power, passing on the temperature and responsibility of national enterprises!
From securing the top 500 global spot, to leading the global new energy track, BYD's every breakthrough, every leap, is the best witness to deep cultivation technology innovation, gathering global expansion, sticking to original mission! Looking forward to the future, BYD will continue to hold original intention, forge ahead, unswervingly practice sustainable development concepts, with frontier hard core technology, perfect global layout, extreme product service, continuously refreshing industry height, going all out to assist global green transformation, striving to realize the beautiful vision of "Cooling the Earth by 1°C", continuously writing the new chapter of Chinese intelligence leading the world!
July 28, 2026, the 2026 Fortune Global 500 list was officially released, BYD ranked for the fifth consecutive year, securing the 91st position, becoming the only Chinese automaker to enter the global top 100. This heavy-weight top 100 seat is not a casual gift of short-term market dividends, but BYD's comprehensive answer sheet for years of deep cultivation in technology, opening up the global market, and practicing green sustainable development, and more is the era microcosm of China's new energy vehicle industry from following, running side by side to leading.

Impressive Operating Data, Building the Foundation of Industry Leadership
Strong operating strength is the underlying support for BYD to secure its position in the global top 100. In 2025, BYD turned in an outstanding report card with 804 billion yuan in annual revenue and 32.6 billion yuan in net profit. Annual new energy vehicle sales reached 4.6 million units, securing both the title of global new energy vehicle sales champion and Chinese automaker sales champion. Growth momentum continued into 2026, with cumulative sales exceeding 1.8 million units in the first half of the year; in July, the company reached a historic milestone — the 17 millionth new energy vehicle officially rolled off the production line, becoming the world's first automotive company to achieve this production record, refreshing the global new energy manufacturing capacity speed record.
Behind the ten-million-scale production and sales is the confidence of a complete independent industrial chain. From batteries, motors, electronic controls to automotive-grade chips, BYD achieves full-chain independent research and production, breaking away from overseas technical constraints, not only ensuring stable delivery but also continuously bringing cutting-edge technology to mass-market models, making high-end new energy experiences no longer exclusive to luxury cars.

Continuous Deep Investment in Billions of Yuan R&D, Technological Innovation Builds a Core Moat
"Technology is King, Innovation is the Root," is the core creed throughout BYD's development. High and continuous R&D investment is the fundamental code for its global leadership. In 2025, BYD's R&D investment reached 63.4 billion yuan, up 17% year-on-year, ranking first in R&D investment among A-share listed companies for two consecutive years; in just the first quarter of 2026, R&D expenditure reached 11.3 billion yuan, far ahead of domestic peers and top new energy brands. As of now, the company's cumulative R&D investment has exceeded 250 billion yuan, with massive funds continuously irrigating cutting-edge tracks such as batteries, intelligent driving, and charging infrastructure.
Continuous investment quickly transforms into disruptive mass-production technologies: In March 2026, the 2nd Generation Blade Battery and Flash Charging technology officially launched, solving user range anxiety with ultra-fast recharging; the company simultaneously planned 20,000 flash charging stations nationwide and 6,000 overseas, building a high-efficiency recharging network covering the globe. In May, BYD became the first to commit to a one-year safety guarantee for city pilot-assisted driving. All models can be equipped with the Divine Eye B Laser Smart Driving System, truly ushering in an era of mass high-level intelligent driving and redefining intelligent mobility safety standards. From battery safety, ultra-fast recharging to autonomous driving responsibility allocation, BYD continuously breaks through industry boundaries and sets new benchmarks for global new energy vehicle technology with self-developed technology.

In-depth Globalization Implementation, Chinese Smart Manufacturing Goes to 121 Countries Worldwide
Today, BYD has long transcended a single domestic market, building a global development pattern of "leading in Latin America, breakthrough in Europe, and flowering in multiple points across Asia-Pacific". Overseas sales exceeded 1 million units for the first time in 2025, a 145% year-on-year surge; in the first half of 2026, overseas sales reached a new high again, with cumulative sales exceeding 780,000 units. The overseas market has become the second growth curve.
Overseas layout is no longer simple complete vehicle export, but in-depth localization: The first overseas Cloud Rail was implemented in Brazil, and the local factory completed the 100,000th new energy vehicle roll-off; Denza high-end models landed in Europe, creating a Chinese luxury new energy business card; the model Sea Otter specifically developed for the Japanese market officially landed; the Thailand factory celebrated its second anniversary of production, and Southeast Asian capacity is continuously released. As of now, BYD's business map covers 121 countries and regions worldwide, completing the upgrade from "product going global" to "industry going global, technology going global", making Chinese new energy technology, manufacturing standards, and mobility solutions go global.

Practicing Greenness and Social Responsibility, Anchoring the Long-term Vision of "Cooling the Earth by 1℃"
While developing at high speed, BYD has always incorporated sustainable development and social responsibility into its core corporate strategy. As of June 30, compared to traditional fuel vehicles, BYD's new energy vehicles have cumulatively achieved carbon emission reductions of 149 million tons in the full energy lifecycle, equivalent to planting 2.48 billion trees, assisting the global realization of "Dual Carbon" goals with tens of millions of green vehicles.
The enterprise also did not forget to give back to society: Setting up a 3 billion yuan education charity fund, reaching donation cooperation with 127 universities nationwide, cumulatively incentivizing over 6,000 young students to grow, empowering talent cultivation with industrial strength while balancing commercial value and social value. "Cooling the Earth by 1℃" is not just a brand slogan, but a long-term mission BYD practices with green technology, global layout, and sustainable manufacturing.

Five Years on the Top 100 List, Steps Continue on the Road Ahead
Five years ago, BYD first ranked in the Fortune Global 500; five years later, it is firmly stable in the global top 100, rewriting the industry pattern long dominated by European/American and Japanese automakers for top 100 seats. From rank 436 to a stable 91st, the upward ranking witnesses the leapfrog rise of China's new energy vehicle industry.
Facing the future, BYD will continue to adhere to the main line of technological innovation, perfect the global production, recharging, and sales integrated network, and continuously output green mobility solutions. With 250 billion yuan in R&D accumulation as the foundation, with 17 million units in production and sales as the starting point, and with a global layout spread across 121 countries as the stage, this new energy leading enterprise originating from China is continuously proving to the world: Chinese Smart Manufacturing, is reshaping the future of the global automotive industry.

Suddenly, the "Ning King" came out to make a splash again.
On the evening of July 24, CATL released two major documents simultaneously. One was the 2026 Interim Financial Report. Revenue in the first half was 276.91 billion yuan, a year-on-year increase of 54.80%. Net profit attributable to the parent company was 43.284 billion yuan, a year-on-year increase of 41.98%. Calculated, this means daily earnings of 240 million yuan.
The other was a buyback plan, proposing to use funds not less than 20 billion yuan and not more than 40 billion yuan to buy back A-share shares for cancellation, with a buyback price cap of 573 yuan per share, a premium of nearly 50% compared to the closing price of the day. This amount cap set a record high for single share buybacks in the history of A-shares.
At the same time, multiple new energy vehicle manufacturers successively released half-year profit forecasts, with many facing profit pressure. Industry chain profits are visibly concentrating on the battery segment, and this is indeed a major source of CATL's profits. However, if you turn to the details of CATL's financial report, you will find a fact overlooked by the outside world.
That is CATL's true growth engine is actually not just power batteries. Or rather, the game CATL is playing is far bigger than what the outside world sees.
Beyond Vehicle Power Batteries, Pulling Up a Second Growth Curve
In CATL's financial report, the most worth noting is its healthy revenue structure. In the first half, the power battery business contributed 192.125 billion yuan in revenue, accounting for 69.38%, remaining the absolute major portion. However, the performance of the other two businesses is also inescapable, showing a trend of accelerated growth.

First, energy storage battery business revenue was 53.261 billion yuan, accounting for 19.23%, a year-on-year increase of 87.54%. Battery materials and recycling, mineral resource business revenue was 18.811 billion yuan, a year-on-year increase of 67.23%.
More critically, power battery gross margin of 20.63% and energy storage battery 23.96% both saw year-on-year declines, while the gross margin of battery materials and recycling business reached 27.04%, an increase of 5.81 percentage points year-on-year.
That is to say, among the three major main businesses, the only one achieving gross margin improvement is the "recycling business" that outsiders ignore most easily.
Looking further down, CATL has also accumulated considerable capital in the ship power battery field.
Already cumulatively delivered over 900 ship batteries. The first all-electric inland container ship exported from China delivered in the first half of 2026, also equipped with CATL's battery energy storage system. In July, also acquired a stake in Jiangsu Kaiyang Shipbuilding Company, increasing investment in the technical development of ocean-going ship battery systems.
In the commercial vehicle field, sodium-ion batteries have gone into mass production installation, the Tianxing series covers multiple sub-scenarios from logistics vehicles to heavy trucks. In the battery recycling field, holding company Bangpu Recycling has built the nation's largest directional recycling base, with an annual retired battery processing capacity of 270,000 tons, and nickel, cobalt, and manganese recovery rate is as high as 99.6%. The team also won two honors at the European Patent Office's "2026 European Inventor Award" this year, becoming the first Chinese team to win dual awards since the award's inception.

These businesses together constitute CATL's second growth curve beyond power batteries.
When lithium battery scrap volume grows at a speed of more than 20% annually, when the commercialization window for electric ships opens gradually, and when AI computing power data centers begin to propose new structural demands on energy supply, CATL has already extended its tentacles into these tracks. Company executives also clearly stated at the performance exchange meeting that AIDC presents a clear structural market opportunity. CATL will not just provide single product supply, but wants to provide more comprehensive solutions around new energy scenarios.
Therefore, from the financial report it can be seen that CATL's high-speed profit growth in the first half, a large part comes from storage, from recycling, from overseas, rather than simply "earning one more cent" from vehicle manufacturers.
Of course, a fact must be admitted here. The gross margin of the power battery business is indeed declining, price competition pressure in the domestic market is real. Moreover, CATL also has its shortcomings.
The "poaching talent and stealing technology" publicly condemned by Zeng Yuqun previously, lost orders in the Middle East market, additional costs brought by consumption tax policies, these are challenges on the table. It's just that these challenges have not covered up the longer-term growth curve.
Earn Money from "Foreigners", Also Earn Money for the Future
If diversification is CATL's first line of defense against industry risk, then globalization is the second moat it built. From this point of view, CATL is also half a step ahead of current auto companies. The overseas dividends it received are exactly the "big results" that current auto companies are striving hard to layout overseas business to obtain.

In the first half, CATL overseas revenue reached 87.1 billion yuan, gross margin 29.97%, nearly 9 percentage points higher than domestic business gross margin. Overseas market share 33.7%, Hungary, US, Indonesia three overseas factories successively put into production, Volkswagen, BMW, Toyota and other global mainstream car companies lie in the customer list.
Morgan Stanley gave a judgment in the latest report. Diesel vehicle electrification, storage super cycle, sodium-ion battery product cycle, will jointly support CATL to continue strong growth in 2027.
The key point is, CATL overseas business gross margin is significantly higher than domestic. This means, its bargaining power in the global market is actually stronger than in domestic. This is somewhat different from the common perception that "Made in China conquers the world with low prices".
CATL management gave the explanation at the exchange meeting as "Competing on value, not price". This sounds a bit official, but combining with gross margin data, it indeed has its confidence.
Zeng Yuqun summarized CATL's current strategic positioning into one sentence: From "New Energy Industrialization" to "Industrial New Energyization". The first half is what CATL did in the past ten years, making the concept of new energy into a real industry. The second half is what it plans to do in the future, using new energy to transform more traditional industries.
Ships, commercial vehicles, computing power data centers, mineral resources, these are all the landing points of "Industrial New Energyization". Zeng Yuqun himself judged, the future downstream industry boundaries may reach over a thousand times the current level.
And if this judgment holds, then the 40 billion buyback big move is easy to understand.
The company's current stock price is undervalued, this is the core logic of the buyback. On the day the financial report was released, CATL A-share closing price was 383.01 yuan, while the 52-week high was 468.75 yuan. Performance hit a new high, but the stock price fell nearly 20% in half a year. CITIC Securities gave a target price of 490 yuan, UBS 600 yuan, Macquarie HK stock target price 700 HKD.
Under this premise, the real money 40 billion buyback is an attitude given by management to the market.

More importantly, the implementation, all bought-back shares are used for cancellation, not kept for equity incentives, nor placed in treasury stock accounts. This means total share capital decreases by about 69.8 million shares, rights allocated to each shareholder will rise.
Of course, this confidence also needs some question marks. Lithium prices recently showed a rebound, Yichun Jianxiwo lithium mine resumption approval may bring cost fluctuations, consumption tax phased collection from 2% to 4% test on downstream bargaining power, are realities CATL must face next.
However, compared to challenges, this financial report indeed let us see a strong resilience and strategic vision shown by an industry leader. From this point of view, CATL is still the undoubted leader of the new energy sector, without a doubt.
Recently, the China Bus Information Network released export statistics data for new energy buses in the first half of 2026. BYD ranked first with an export volume of 2,233 units, with a market share of 22.15%, making it the only enterprise in the industry to break the 2,000-unit export threshold in the first half of the year. Amidst the global wave of green transportation transformation, BYD maintained steady growth and has won the annual new energy bus export champion for three consecutive years.

BYD electric buses have achieved a pattern of flourishing across the globe with simultaneous deep cultivation in multiple continents, high-end, and emerging markets. As of the end of June, in the high-standard European market, BYD has cumulatively delivered over 7,000 pure electric buses. Among them, over 2,700 buses are already in operation in the UK, accounting for 45% of the market share for zero-emission buses in the UK.

BYD Buses in the UK
In the Americas region, BYD continued to achieve breakthroughs at multiple points, maintaining a leading trend. In Colombia, BYD has cumulatively operated over 1,500 buses, ranking first in market share; in the Brazilian market, it has continued to deepen and expand since local production of electric bus chassis began in 2015. In June this year, BYD delivered 265 electric buses to São Paulo in a single shipment, setting a new record for the scale of single-shipment deliveries of heavy-duty electric buses in Brazil. Relying on localization strategy and technical accumulation, BYD has long stably held the top spot in the market share of imported electric bus brands in Brazil. In addition, the Middle East and African markets are advancing steadily, with orders being successively delivered in places like Morocco and the UAE.
In the Asia-Pacific region, business covers multiple countries including Singapore, Thailand, Malaysia, Australia, etc., becoming a mainstay model for local public transport electrification. Currently, BYD electric buses have orders exceeding 500 units in Japan, with a market share exceeding 50%, ranking first in the industry.

BYD Buses in Singapore
The core foundation for BYD electric buses to continuously lead comes from the full-stack self-developed core technology system. Relying on e-BUS Platform 3.0, Blade Battery technology, etc., it is adaptable to global complex operating conditions such as high temperatures, extreme cold, and mountains, showing outstanding advantages in safety performance and total lifecycle costs, successfully passing strict market certifications in Europe, the US, Japan, South Korea, etc., gaining recognition from global customers.

Making its debut at the Milan NME Exhibition
In the future, BYD will continue to provide leading technology, reliable quality, and excellent service, to support the green development of global public transportation.
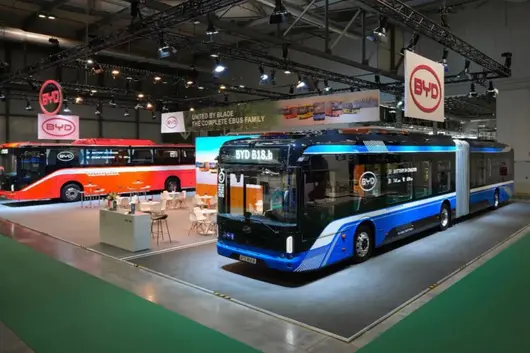
Recently, China Bus Network released export statistics data for new energy buses in the first half of 2026. BYD ranked first with an export volume of 2,233 units, accounting for a market share of 22.15%. It was the only enterprise in the industry to break through 2,000 units in exports in the first half. Under the wave of global green transportation transformation, BYD maintains steady growth and has won the annual export champion of new energy buses for three consecutive years.

BYD electric buses have achieved a pattern of global blossoming with simultaneous deep cultivation in multiple continents, high-end markets, and emerging markets. As of the end of June, in the high-standard European market, BYD has cumulatively delivered over 7,000 pure electric buses. Among them, over 2,700 buses are in operation in the United Kingdom, accounting for 45% of the market share of zero-emission buses in the United Kingdom.

BYD Buses in the United Kingdom
In the Americas region, BYD continues to achieve breakthroughs at multiple points and maintains a leading posture. In Colombia, BYD has cumulatively operated over 1,500 buses, ranking first in market share; the Brazilian market has continuously deepened and expanded since initiating local production of electric bus chassis in 2015. In June this year, BYD delivered 265 electric buses to São Paulo at once, setting a new record for the single-batch delivery scale of heavy electric buses in Brazil. Relying on localization strategy and technical accumulation, BYD has long remained at the top of the market share of imported electric bus brands in Brazil. In addition, the Middle East and African markets are steadily advancing, and orders are being delivered successively in places such as Morocco and the UAE.
In the Asia-Pacific region, business covers multiple countries such as Singapore, Thailand, Malaysia, and Australia, becoming the main model for local public transportation electrification. Currently, BYD electric buses have orders exceeding 500 units in Japan, with a market share exceeding 50%, ranking first in the industry.

BYD Buses in Singapore
The core foundation of BYD electric buses continuing to lead comes from a fully self-developed core technology system. Relying on technologies such as e-BUS Platform 3.0 and Blade Battery, it can adapt to global complex operating conditions such as high temperature, extreme cold, and mountainous areas. It has prominent advantages in safety performance and lifecycle costs, successfully passed strict market certifications such as Europe, America, Japan, and South Korea, and gained recognition from global customers.
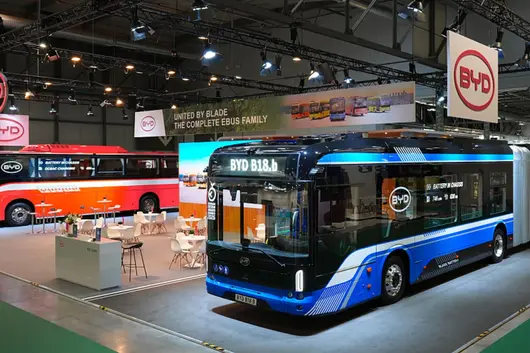
July 16, GAC held a 30 million user appreciation event at the Trumpchi factory. Achieving milestones has become quite common for automakers nowadays, but the signal released by this event carries far more weight than the number 30 million itself.
Many people's impression of GAC might still be stuck on it being a joint-venture honor student, but this lineup ceremony can be said to refresh cognition. The 29,999,995th to 29,999,999th vehicles off the line were exclusively new energy models: GAC Honda P7, GAC Toyota bZ7, Qijing GT7, Aion N60, Hyper S600, all new energy. The 30 millionth vehicle is a right-hand drive Trumpchi M8 PHEV, delivered to Thai star Tony Jaa. The answer is clear: GAC's next 10 million era will have new energy as the protagonist and the global market as the battlefield.

From the first vehicle off the line to exceeding 30 million, GAC took 29 years. But these 30 million were not produced by lying flat in a smooth environment; they were fought for during the most competitive cycle in the industry. Throughout the first half of this year, price wars in the auto market continued, joint ventures faced pressure across the board, new forces hovered around the break-even line, but GAC ran a steady rhythm with total sales of 773,100 units, increasing by 2.35% year-on-year; new energy sales increased by 68.8% year-on-year; overseas exports exceeded 120,000 units, with a year-on-year increase of 132%.
Joint venture fundamentals were not lost, autonomous new energy surged, and the overseas market gained momentum quickly. There were no all-or-nothing gambles, nor hesitant observation. In the impetuous auto market, this steady yet progressive approach has become scarce. Ultimately, 30 million is not just a sales number; it is the result of 29 years of trust from millions of users. In the current era of choice overload, continuously winning trust is itself hard power.

At the event, Feng Xingya said that quality is the bottom line GAC will never compromise on. The value of this sentence is estimated to be known only by friends familiar with GAC.
GAC's quality system originated from the foundation laid during the joint-venture era, integrating Honda TQM, Toyota Lean Production, and Lingnan Pragmatic Culture, forming a unique quality control logic. Others shout "Quality First" as a slogan, but GAC locks standards from R&D to manufacturing across the entire chain. Before every new car launches, it must pass extreme environment tests including Five Highs, One Mountain, and One Dust, complete two winters and one summer of on-site road tests, vehicle verification covers 12 major items and over 1,500 sub-items. The Aion Lighthouse Factory uses digital intelligent manufacturing to maximize production stability.
Safety level also does not play nonsense. The Star Spirit Safety System features eight systems with dual redundancy, having protected nearly 2 million users, avoiding over 6.28 million potential risks. Magazine batteries have been installed in 1.5 million vehicles, with safe driving exceeding 160 billion kilometers. More rarely, service backing comes first. The domestic brand pioneered the "Three Responsibilities" policy; the battery and intelligent driving issues that users worry most about are shouldered directly by the manufacturer. High user loyalty boils down to one sentence: what we worry about, it thought of in advance. What we care about, it provided a safety net for.

If quality is the basic skill, the most obvious change at GAC in the past two years is putting user thinking truly into practice.
In the fuel vehicle era, delivery was the endpoint of service; in the new energy second half, it is about full-cycle experience. GAC's approach is very pragmatic. Internally, hold regular all-open-mic user meetings, listen to opinions face-to-face, set up exclusive user insight departments, and ensure from the mechanism that every appeal gets a response; externally, accelerate channel submergence, planning to add 1,000 county-level stores this year, allowing the submerged market to also enjoy standardized services.
Response and refueling follow up simultaneously. The Super Butler responds in 5 seconds, completes in 2 hours, no need for repeated bickering. The 9 Verticals 10 Horizontals refueling network covers 213 cities, a station must be within one kilometer in the core urban area. Private ultra-fast charging piles exceed 20,000 units, practically relieving refueling anxiety. The simultaneously launched Renewal Appreciation Season covers six major brands, offering benefits across new purchase, trade-in, and upgrade purchase scenarios. Essentially, this is positive feedback to users — the core of business is always a two-way journey.

Many people think GAC is steady, but steady does not mean conservative. Cumulative R&D investment exceeds 62 billion yuan. Global R&D teams exceed 6,800 people. Technical investment has always been resolute.
Star Source Power covers three routes: range-extended, plug-in hybrid, and dual-motor, verified on test benches for 100,000 hours. All-solid-state batteries are building pilot production lines. Quark Electric Drive efficiency breaks 99%. Star Spirit Architecture connects six major vehicle systems, improving comprehensive performance by 40%. At the same time, GAC does not build cars in a closed room. Top enterprises like Huawei, CATL, and Tencent are all ecosystem partners, jointly building a smart mobility ecosystem.
Advancing from a car-making group to an ecosystem technology enterprise is GAC's clear goal. Looking back at the Chinese auto industry, GAC is a highly representative sample. From learning technology through joint ventures to controlling core technologies independently, then exporting new energy, this is exactly a miniature of the Chinese auto industry growing from large to strong.

In conclusion, in today's accelerating industry reshuffle, there are many brands that tripped over their feet with aggressive expansion, and many players lying flat守着 existing stock. Instead, GAC's approach of maintaining quality, producing technology, and opening up a broad vision makes people feel grounded. 29 years sharpening one sword, 30 million is just a new beginning. In the new energy second half, this steady card will still bring more surprises.
On July 16, GAC Group's 30 Million User Gratitude Celebration was held at the GAC Trumpchi Factory. Government and enterprise leaders, industry partners, domestic and international car owners, and media jointly witnessed this key milestone of the Group's 30 millionth vehicle coming off the production line. After 29 years of development, the delivery of 30 million vehicles is not only a testament to the trust of tens of millions of users but also a microcosm of the Chinese automotive industry shifting from scale expansion to high-quality development.

The event featured a connection to global bases on-site. Multiple new energy models from GAC Honda, Toyota, AION, Hyper, and Qijing sequentially completed production of the 29,999,995th to 29,999,999th units. The finale, the 30 millionth vehicle, was a Right-Hand Drive Trumpchi M8 PHEV. New car keys were delivered to a Thai owner on-site, intuitively showcasing GAC's dual achievements in new energy transformation and global expansion.
Market data confirms transformation results. In the first half of this year, GAC cumulative sales reached 773,100 units, up 2.35% year-on-year; new energy sales surged 68.8%, overseas exports reached 120,000 units, an increase of 132%, maintaining steady growth during the industry adjustment cycle.
Quality is the core bottom line of GAC's development. The group integrated the mature management system of Japanese brands to create an exclusive quality management model. New cars undergo unified testing in extreme environments of "Five Highs, One Mountain, One Dust" and two winters and one summer long-cycle tests. Relying on AION's global new energy lighthouse factory, digital quality control is achieved. In terms of safety, the StarGuard protection system and Cassette Battery are applied, cumulatively avoiding millions of driving risks. The industry's first "Three Responsibilities" policy proactively covers issues related to batteries and intelligent driving, eliminating user concerns about vehicle usage.

According to reports, GAC regularly carries out face-to-face communication with users, adhering to a user-centric orientation and building a full closed-loop complaint handling mechanism. Channels continue to deepen, adding 1,000 county-level stores this year and launching a 5-second response ultra-fast butler service. A "9 Verticals, 10 Horizontals" charging network covering the country has been built, with over 20,000 self-operated super-charging piles, perfecting supporting facilities for new energy vehicles. On-site, the full-brand renewal gratitude season was simultaneously launched, with six passenger car brands offering multiple return policies for purchasing and trading in.
With 30 million as a new starting point, GAC continues to increase investment in independent research and innovation, with cumulative R&D investment exceeding 62 billion yuan and an R&D team of over 6,800 people. The Xingyuan Power series power solutions, Quark efficient electric drive, all-solid-state battery pilot line, and evolved StarGuard electronic architecture are landing successively. They are jointly building an AI intelligent ecosystem with companies such as Huawei and CATL, continuously tackling industry pain points such as fast charging and low-temperature range.
In the future, GAC will adhere to the four main lines of Quality, User, Technology, and Globalization, accelerate the transition to an ecosystem-based tech enterprise, continuously output green intelligent products, and expand the global market.
Editor's Summary: Whole vehicle production and sales breakthrough 30 million is a concentrated embodiment of nearly 30 years of GAC's manufacturing, channel, and technology accumulation. At the same time, the enterprise did not only focus on product iteration. From extreme condition testing and battery safety backing, to county-level channels, national charging networks, and ultra-fast user services, a complete user guarantee system is formed. It is worthy of learning and reference by other car companies.
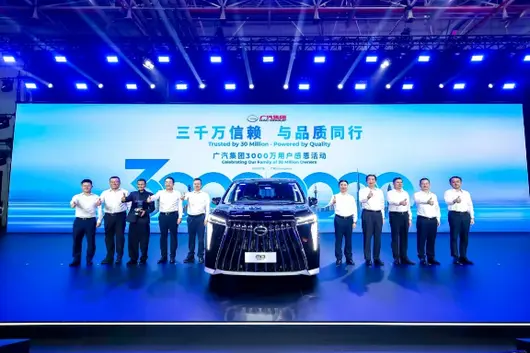
Editor's Note: Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain.
On July 15th, Geely Holding Group released the mid-year sales performance report: Total vehicle sales for the group from January to June reached 1.93 million units, setting a new high for the same period in history; among them, new energy vehicle sales reached 1.1 million units, a year-on-year increase of 10%, with the new energy penetration rate climbing to 56.9%. This means that for every 100 cars sold by Geely Holding Group in the first half of the year, nearly 57 were new energy vehicles, and the group as a whole has entered the harvest period of electrification scale.

As the core listed entity under Geely Holdings, Geely Auto's sales reached 1.43 million units in the first half of the year, with new energy sales (including Geely, Lynk & Co, Zeekr) at 799,000 units, a year-on-year increase of 10%, and a new energy penetration rate of 56%. Sales data from the group to the core brand outline a traditional Chinese automaker that started with fuel vehicles, and in the background of intensifying industry stock competition, how to complete a structural transformation through a multi-brand matrix and global layout.
Multi-brand matrix synergy, new energy becomes the main axis of growth
Geely's ability to refresh records in the first half of the year was not pulled by a single brand, but the result of synergy between the three major brands Geely, Lynk & Co, and Zeekr in different sub-segments.
The Geely brand, which targets the mainstream home market, achieved cumulative sales of 1,100,373 units in the first half, of which the China Star series sold 580,580 units, continuing to firmly rank among the top sales of domestic brand fuel vehicles, playing the role of a "ballast" for the basic market. What truly drives the volume increase in new energy is Geely Galaxy—cumulative deliveries in the first half reached 519,793 units, with single-month sales in June at 108,206 units, a year-on-year increase of 20% and a month-on-month increase of 32%. The Star Wish under the Galaxy brand broke 50,000 units in a single month, with cumulative sales since launch exceeding 750,000 units, becoming the core product in Geely's new energy volume-selling camp.

Lynk & Co, positioned in the mid-to-high-end hybrid market, achieved cumulative sales of 144,215 units in the first half, with new energy vehicle sales at 93,597 units, and the proportion of new energy products reaching 65%, stabilizing the mid-to-high-end hybrid sub-market by relying on the EM-P hybrid family promoted by the simultaneous launch of three car models. Zeekr continued its strong performance on the high-end luxury track, delivering 178,370 units in the first half, a significant year-on-year increase of 97%; single-month deliveries in June were 35,169 units, a year-on-year increase of 111%, achieving consecutive five-month year-on-year and month-on-month double growth, with global cumulative deliveries officially breaking through 820,000 units.
From the perspective of the group as a whole, June single-month Geely Auto new energy sales reached 161,449 units, a year-on-year increase of 32% and a month-on-month increase of 21%, with new energy sales proportion of the group's total sales exceeding 67%—equivalent to nearly 7 out of every 10 Geely new cars sold being new energy vehicles. This structural change marks that Geely's "oil and electricity simultaneous promotion" transformation rhythm has entered a new stage dominated by new energy.
It is worth noting that Geely's new energy transformation is not at the expense of abandoning fuel vehicles. The China Star series still maintains strong competitiveness in the fuel vehicle market, and this "fuel ballast, new energy volume" dual-track strategy enabled Geely to hold its basic market share in the domestic auto market in the first half. Data from the China Passenger Car Association shows that in the ranking of narrow passenger vehicle manufacturer retail sales from January to June, Geely ranked first with 1.021 million units and an 11.7% share, being the only domestic brand to break the million-unit mark in the first half.
Overseas business leaps, globalization enters harvest period
If new energy penetration rate is the most eye-catching internal change in Geely's first half, then the explosion of export business is its most prominent external highlight.
Data shows that Geely Auto's first-half overseas export sales reached 474,228 units, a year-on-year increase of 158%—this number has already exceeded Geely's total export volume for the full year of 2025. June single-month overseas export sales broke the 100,000 unit threshold for the first time, reaching 102,874 units, with a year-on-year increase of 157% and a month-on-month increase of 21%, achieving consecutive six-month year-on-year and month-on-month double growth.
A more critical change lies in the export structure. In the first half, Geely's new energy product export sales were 277,189 units, surging 585% year-on-year, accounting for 58% of the total export volume. This means Geely's main overseas products have completed the switch from traditional fuel vehicles to new energy vehicles, with new energy products gradually becoming the core driving force for overseas market growth.
Geely Holding Group's overall global layout also landed at multiple points in the first half: Geely signed Swiss dealers to strengthen the European market, Lynk & Co 900 launched in Vietnam and Qatar, Geely Xingyuan EX2 began local production in Brazil, Binyue Cool launched in South Africa; Zeekr topped the Malaysia luxury pure electric sales list, 007 GT has launched in 16 European countries, flagship model Zeekr 9X plans to go to the Middle East in Q3, and will subsequently expand into US/Europe and Central Asian markets.
Overseas high-end brands also performed steadily. Volvo Cars first-half global sales were 325,000 units, with new energy sales at 161,000 units, a year-on-year increase of 3.8%, with new energy penetration rate reaching 50%, and pure electric vehicle deliveries growing for 9 consecutive months. Polestar first-half sales were 30,400 units, achieving sales breakthroughs in markets such as the UK, Germany, and South Korea, setting a new high for the brand at the same period in history. In the Southeast Asia and commercial vehicle sector, Proton first-half sales were 100,300 units, a year-on-year increase of 39.1%, achieving the best half-year performance since 2011; Farizon New Energy Commercial Vehicles first-half sales were 88,000 units, a year-on-year increase of 41.3%, with overseas export sales ranking at the forefront of the new energy commercial vehicle industry.
Geely Group's performance in the first half of the year can be called bright, but in the automotive market where variables are ever-present, its challenges for the second half of the year remain. Intensifying domestic car market stock competition and unrelenting price war pressure, Geely brand and Lynk & Co brand first-half cumulative sales declined year-on-year by 5% and 6% respectively, indicating that the fuel vehicle basic market still faces contraction pressure; and in the overseas market, geopolitical tensions, trade barriers, and the difficulty of localization operations will also rise synchronously with the expansion of export scale. Whether Geely can continue its growth momentum in the second half depends on the volume pace of Galaxy and Zeekr, the development progress of Middle East and European markets, and the balancing ability of resource allocation between fuel vehicles and new energy.
[CNMO Tech News] July 16, @NEVData released observation data on the Southeast Asia automotive market: Chinese brand market share in the six ASEAN countries (Indonesia, Malaysia, Thailand, Vietnam, Philippines, Singapore) exceeds 60% in the new energy sector. Among them, Indonesia reached as high as 91%.

Chinese New Energy Vehicles
According to statistics, cumulative sales of passenger cars and pickups in the six ASEAN countries in the first half of the year totaled 1.9246 million, up 7.2% year-on-year. Specifically for June data, retail sales of passenger cars and pickups were 332,700, up 9.7% year-on-year. Indonesia (passenger cars, same for subsequent mentions) sales were 74,507 units, up 10.5% year-on-year; Malaysia sales were 72,943 units, up 23.1% year-on-year; Thailand sales were 68,912 units, up 11.2% year-on-year; Vietnam and Philippines sold 51,366 and 38,124 units respectively, up 6.4% and 4.1% year-on-year; Singapore was the only country with sales declining year-on-year, selling 6,948 units, down 1.8%.

Data shows, June NEV penetration rates varied significantly across countries. Singapore ranked first with a penetration rate of 66.4%, up 19.2% year-on-year; Vietnam and Thailand ranked second and third with penetration rates of 41% and 30.3% respectively, up 94.7% and 31% year-on-year. Although Indonesia and Malaysia penetration rates were under 20%, they surged 78% and 122% year-on-year. The Philippines lagged severely due to a lack of charging infrastructure, with a penetration rate of only 2.1%. These market increments were mainly contributed by Chinese new energy vehicle brands.
In the new energy sector, Chinese brand market share exceeds 60%. Among them, Malaysia reached 62%, Thailand 78%, Indonesia 91%. However, in the overall market, Japanese brands still lead with 68%. However, the overall market share of Chinese brands increased by 6.2 percentage points year-on-year (reaching 13.7%), reaching 17.3% in Thailand, surpassing Japanese and South Korean brands to become the largest group.
On July 8, the 100,000th Avatr 07 vehicle rolled off the production line at Chongqing Digital Intelligence Factory. This milestone model is the right-hand drive overseas version, marking the main model's leap from a domestic blockbuster to a global product. With a delivery scale of 100,000 units, simultaneous overseas layout, and dual-model matrix implementation, this reflects three clear industrialization upgrade paths for China's high-end new energy vehicle industry—manufacturing, technology, and globalization—providing a replicable development model for the industry.
From the dimension of manufacturing industrialization, the core confidence behind the 100,000 units comes from the full-domain intelligent factory system. Currently, the domestic new energy market has entered a stage of stock competition, where price wars compress profits, making stable, low-cost, and high-quality mass production capabilities the bottom line for brand survival. The Chongqing Digital Intelligence Factory supporting Avatr 07 production is the world's first full-domain 5G+AI flexible whole vehicle manufacturing base, integrating over 40 cutting-edge technologies such as digital twins, full-process automated welding, and digital quality control. Annual production capacity can stably support the synchronous production of multiple models, with a supporting capability of up to 200 units per year, achieving a balance between personalized customization and mass production.

This intelligent manufacturing system co-built by Changan, Huawei, and China Unicom solves the challenge of mass production consistency for high-end models. In the past, high-end new energy vehicles commonly faced the pain points of low-volume, hard-to-mass-produce customization. Avatr connects the R&D, production, and quality control full-link through a three-party collaborative supply chain, rapidly transforming frontier laboratory technologies into standardized products. The stable delivery of 100,000 units proves that domestic high-end new energy has shaken off the label of "niche concept cars", completed industrialization landing, and moved away from the fragile model relying on a single blockbuster for short-term volume.
Secondly, technological collaborative industrialization is the core competitiveness of Avatr 07 to secure its position in the 200,000-300,000 RMB high-end track. Unlike the single automaker self-research model, Avatr integrates core resources from the three-party industry chain, forming a complete technical closed loop: Huawei provides Kunqun ADS 4 intelligent driving and HarmonyOS Cockpit, CATL outputs Shenxing Supercharging battery, Changan is responsible for the whole vehicle chassis and whole vehicle manufacturing. The six major core technologies are fully independently controllable, with no risk of core components being externally choked off.
In the current era of homogeneous industry configurations, a complete industry chain collaborative system builds differentiated barriers. The model has successively won the USA IDA and German iF International Design Awards; its original appearance design possesses global aesthetic adaptability; 90-second fast recharging, full-scenario advanced intelligent driving, and extended-range pure electric dual powertrain solutions cater to both domestic commuting and overseas diverse road condition needs. This integrated collaborative model of whole vehicle, intelligence, and battery/electric/powertrain represents a new division of labor for China's new energy industry: automakers coordinate and integrate, tech companies output intelligent software and hardware, battery enterprises provide energy solutions. The industry chain functions in its respective role with deep binding, marking a significant sign of industry maturity.
Third, global industrialization layout opens up new growth space for the industry, and the right-hand drive milestone model releases a clear industry signal. The domestic market volume has peaked, going overseas has become a mandatory question for all new energy automakers, while industrial overseas expansion has long moved away from simple vehicle exports, turning to integrated layout of products, capacity, and channels. The 100,000th vehicle rolled off the line this time is the right-hand drive model, specifically adapting to massive right-hand drive markets such as Southeast Asia, the Middle East, and the Commonwealth. It is not simply changing the steering wheel layout, but achieving full-dimension localization adaptation from chassis calibration, infotainment interaction, to safety regulations.

Currently, Avatr products have landed in markets such as Singapore, Thailand, UAE, etc., with channels covering 43 countries. Planned to enter Europe in 2026, covering over 110 countries by 2030. Compared to the scattered exports of most automakers, Avatr completed the synchronous R&D and mass production of right-hand drive models in advance, directly connecting domestic and overseas dual-market supply at the manufacturing end. Relying on mature domestic production capacity bases to radiate globally, avoiding high investments in building factories overseas, using local super factories as global production capacity pivots. This is a more cost-effective industrialization overseas route.
At the same time, Avatr 07L has simultaneously started pre-sale. 07 and 07L form a dual-car matrix, perfecting the coverage of segmented markets, completing the industrial iteration from a single blockbuster to a product matrix. The 100,000 units sales of a single model is just the starting point. Dual-model parallelism can dilute R&D, production, and supply chain costs, further amplifying scale advantages, and hedging against market cycle fluctuations.
Against the backdrop of the overall transformation of the automotive industry, the rolling off of the line of 100,000 Avatr 07 right-hand drive whole vehicles is not just a brand milestone, but also a microcosm of the maturity of the domestic new energy industry. Intelligent manufacturing builds a solid mass production base, the whole industry chain collaboration creates technical barriers, and the simultaneous layout of domestic and overseas dual markets expands the growth ceiling. The three industrialization paths support each other, allowing Chinese high-end electric vehicles to break free from low-price involution and truly possess the strength to compete globally with international luxury brands. In the future, as domestic automakers continuously deepen industry chain integration and perfect global product layout, the new energy vehicle industry will complete the qualitative change from scale leadership to all-around leadership in technology, manufacturing, and brand.
July 8, BYD's 17 millionth new energy vehicle rolled off the line at the Xi'an factory. From 16 million to 17 million, it took less than 3 months. Average daily production exceeds 12,000 units.
 17 million units, what concept is this? Over a century of global automotive history, no new energy vehicle manufacturer has ever reached this scale. More crucially, from the first million taking 13 years to now adding another million in just over 80 days—this acceleration curve is truly staggering. This is not just a leap in production and sales data, but also creates a new benchmark for the development of the global new energy industry.
Many think BYD just rode the wave of new energy policy benefits. But can policy benefits explain the production ramp-up of a million units in three months? Can it explain the overseas growth rate of 789,000 units in half a year, up 68% year-on-year? Can it explain a Chinese carmaker beginning to export technical standards to the globe?
Obviously not.
What truly supports this number of 17 million units are three core capabilities that are hard for others to replicate.
First: Full-stack independent research, from "being bottlenecked" to "holding in hand"BYD's technology route has never been single-point breakthroughs, but rather full-stack independent research.
In March 2026, the second-generation Blade Battery and Flash Charging technology were released. Fully charged in 5 minutes at room temperature, 9 minutes full, plus only 3 minutes at minus 30 degrees — overcoming the "slow charging" and "cold weather charging difficulty" two major global problems in one go.

In May, China's first 4nm process smart driving chip "Xuanji A3" mass-produced, three-chip collaborative computing power exceeds 2,100 TOPS. Same month, BYD took the lead in promising to guarantee city pilot safety for 1 year, all series available with Sky's Eye B Laser version.
From battery, motor, electronic control to chips, smart driving, chassis, BYD achieved full-link independent controllability from upstream lithium mine resources to downstream complete vehicles. Core link independent R&D and production rate exceeds 90%.
Others build cars by assembling supply chains, BYD builds cars from mine to complete vehicle one-stop. Once this system runs smoothly, it is a moat others cannot copy, and also the bottom-line support for BYD pushing the new energy industry to a new height.
Good technology is just a premise. What makes BYD truly amazing is that — these core technologies are not used for "showing off skills". Sky's Eye standard equipment across series, city pilot and smart parking "safety double guarantee", making good technology accessible to everyone. The 17 million units data proves that domestic suppliers already possess global competitiveness in automotive-grade certification, yield control, and cost optimization.
Technology is not used for enshrinement, but for popularization. This is what defining standards should look like.
Second: Vertical integration, from "subject to others" to "self-sufficient"BYD is not only a complete vehicle manufacturer, but also a vertical integrated supply chain giant. Its subsidiaries such as FinDreams Battery, FinDreams Power, BYD Semiconductor, etc. constitute a complete domestic Tier1 camp.
 What is the direct result brought by this model? Core component costs are more than 33% lower than the industry average.
In the early days of global chip shortage and raw material price increase cycles, peers reduced production and stopped work, BYD production capacity was almost unimpacted. When others were bottlenecked by supply chains, BYD quietly built cars. When others were still grabbing chips, BYD had already designed its own chips.
17 million units rolled off the line is not only a victory for the complete vehicle factory, but also a production volume landmark for the domestic supply chain. From second-generation Blade Battery to Sky's Eye smart driving, autonomous controllability and mass production delivery capability of core components have become the industry moat. This fully industry chain autonomous controllability system is itself a new height that the new energy industry can reach.
This model allows cutting-edge technology to quickly trickle down to all series models, no need for high-end cars to exclusively occupy core configurations. Seal 08 sells from 196,900 starting, but equipped with DiSus-A, rear-wheel steering, 905km range, flash charging, smart driving double guarantee — 200,000 RMB car, million-level configuration.
This is not a price war, this is a system war.
Third: Globalization, from "product going overseas" to "standards going overseas"In the first half of 2026, BYD sold 789,000 units overseas, up 68% year-on-year, overseas sales proportion exceeds 43%. June single month exports 175,300 units, creating a new historic high.
But more noteworthy than sales volume is the layout. Thailand, Brazil factories already mass-produced, Hungary, Indonesia factories to start production in 2026. From Southeast Asia to South America to Europe, a localized manufacturing system covering Asia, Europe, and Africa is taking shape.
More crucially — BYD is simultaneously exporting charging standards. Scale implementation of Flash Charging stations overseas at the end of 2026, from "Flash Charge China" to "Flash Charge Planet". Domestic has already built 7,018 Flash Charging stations, covering 325 cities, end of year target 20,000 stations.
Before it was Chinese cars chasing others' standards. Now it is others considering whether to connect to China's charging standards. This role shift is the most worthy of discussion behind 17 million units.
Final Thoughts
Xi'an is the place where BYD's car building dream started. 2003 first car rolled off the line, 2008 global first plug-in hybrid born, to today 17 millionth new energy vehicle rolls out from here.

17 million units is not just cold production capacity numbers, but also a landmark node for Chinese carmakers turning from policy followers to technology definers. From the depth of technology self-research, to the breadth of vertical integration, to the speed of global layout, BYD used a complete system capability to turn 17 million units from numbers into confidence, pushing the Chinese new energy industry to an unprecedented new height.
This is not only a milestone in production and sales volume, but also a new starting point for a Chinese carmaker to export standards and rules to the globe.
#BYD17MillionthNewEnergyVehicleRolledOffLine#
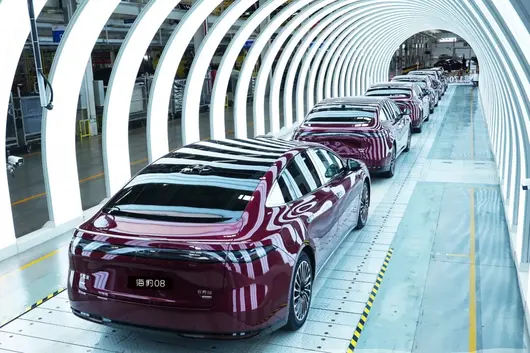
In the first half of 2026, cumulative retail of passenger cars in China's automotive market reached approximately 8.75 million units, a year-on-year decline of about 20%; meanwhile, new energy penetration rate broke 63% in May to set a historical high, and climbed further to about 63.6% in June.
The overall market downturn and structural upgrade running in parallel can be said to be the theme of this half-year; against this backdrop, true new energy top players are beginning to surface.
BYD, with 1.7774 million units in sales, continues to top the sales list; Geely Auto follows closely, with cumulative sales of 1.423 million units in the first half of the year, setting a new historical high for the same period, with the two companies combined taking about 38.7% of the new energy market share in China. More than one-third of new energy vehicles are either made by BYD or Geely.

At this point, the "Two Supers and Many Strong Powers" new energy market structure has been formed, and the top two automakers are widening the gap with the followers. Many automakers have fought in the new energy market for so many years; the elimination round is approaching its end, the market share of domestic brands has exceeded 73%, and the "Hegemony War" of China's new energy market has basically been locked between these two companies.
BYD and Geely are seizing territory with different paths respectively; one is a strong hand at integrating the industry chain, and the other is a skilled hand at organizing the system. In this "Hegemony Battle", will it ultimately end with two strong heroes standing together, or will someone seize power at once?
# BYD and Geely, Leaving Followers Far Behind? #
Stretching the timeline to 2025, the basic outline of China's new energy vehicle market structure was already apparent.
BYD, with 4,602,436 units of new energy vehicle sales for the full year of 2025, a year-on-year growth of 7.73%, among which pure electric vehicle sales were 2.2567 million units, surpassing Tesla for the first time to become the annual sales champion of pure electric vehicles globally. The domestic new energy vehicle market share exceeded 35%, and the full-year sales of 2025 entered the global automotive group sales top five for the first time.

Geely, with 3.0246 million units in sales for the full year of 2025, breaking 3 million units for the first time, up 39% year-on-year. New energy sales exceeded 1.68 million units, up 90% year-on-year. Full-year revenue was 345.2 billion yuan, up 25% year-on-year. Core net attributable profit was 14.41 billion yuan, up 36% year-on-year.

Entering the first half of 2026, BYD reached 1.7774 million units (down 15.9% year-on-year), Geely 1.423 million units (up about 1% year-on-year). Still the top two in domestic sales. From the market share perspective, the China new energy passenger car market in the first half of 2026 was about 5.5 million units. BYD's share was about 32.3%, Geely's share was about 14.5%.
One could say that in China's new energy market, these two brands took nearly half of the market. You should know that six years ago, Geely's new energy proportion was in single digits, and BYD was far from forming the scale it has today. At this point, the pattern of China's new energy market has basically been set, with multi-brand chaos evolving into "Two Giants and Multiple Strong Contenders".
# Scale and System: Which is the Key to Seizing Market Hegemony? #
Why is it BYD and Geely that can form dominance in China's many new energy brand markets with so many cars, plus policy support?
Let's look at BYD first. Currently, its biggest moat is its massive scale. This scale not only protects itself but also blocks the invasion of competitors. So where does this scale come from?
At the beginning of the development of China's new energy market, it could be said to be a complete blue ocean. At that time, even large global automotive groups dared not easily get involved. After all, this is a fundamental energy transition. Entering this market means that the profit model, production and manufacturing system, and product definition model of the previous fuel car era must be completely started from scratch. Not only must time costs be paid, but an economic account must also be calculated.
But in China, there is an undeniable point, which is the support of policy direction. BYD is able to become the current hegemon of the new energy industry because it also bet on the direction of policy. Under the decision to go ALL IN on new energy, it successfully became the first Chinese automaker to conquer the new energy market, thereby helping itself quickly take a large share of the market.
On top of this, through the path of vertical integration, from lithium mining to battery manufacturing, from chip design to vehicle production, BYD itself has built a complete industry chain closed loop.

Its advantage lies in that even if the industry's overall profit margin is only 3.2% now, BYD can still press down costs by self-producing batteries, self-producing chips, and self-producing electronic controls. In 2025, why BYD was able to reach a 35% market share in the domestic market, it relied on "others cutting prices, and I can still make money".
So at this time, this first-mover advantage combined with cost control can give it the initiative in market competition, not being led by the nose by other opponents, but making itself the person who moves first. When grasping the initiative, it will be more at ease in the market, thereby quickly forming scale expansion.
But historical experience shows that when scale expansion reaches a certain extent, it will naturally slow down or even decline. Even as strong as BYD has not escaped this law. In the first half of this year, its sales saw a decline, and the market sales of main models such as Song PLUS, Qin PLUS, and Seagull saw a year-on-year decline.
When the price war dividend has fully receded, simple price strategies are difficult to form differentiation barriers. Wang Chuanfu admitted at the shareholders' meeting: Current technology leadership is not as good as in previous years, the market wow factor of technological results has decreased, and industry homogenization characteristics are becoming increasingly obvious.
For this, in June 2026, BYD launched the largest scale organizational reform of its vehicle business since its inception, reorganizing the four brands Dynasty, Ocean, Denza, and Fang Cheng Bao into independent operating units, implementing independent accounting and bearing their own profit and loss. The R&D system was reconstructed into "Group Technology Middle Platform + Brand Research Institute". The purpose is very clear: after achieving expansion, gradually shifting from "scale driven" to "profit and efficiency driven".
Let's look at Geely. Its play is completely different from BYD. It does not build a wall with one industry chain, but uses a set of system structure to deploy.
The foundation of such a system is built under Li Shufu's "One Geely" strategy. Closing redundant entities, integrating R&D, procurement, and intelligent resources, the Qianli Haohan Intelligent Driving System is reused across brands. This unified technology base, relying on brands to form product differentiation, is forming the late-mover advantage of traditional large factories against rapid iteration and price wars.
Specifically, Geely Galaxy undertakes the task of high-volume market mainstream new energy vehicles, with cumulative sales of 519,793 units in the first half of the year; the China Star Series stabilizes the fuel car base, with cumulative sales of 580,580 units in the first half of the year; Zeekr raises brand premium with an average price of 350,000 yuan, delivering 178,300 units in the first half of the year, up 97% year-on-year; Lynk & Co covers both high-end new energy and overseas expansion.
This division of labor where each fulfills its duty allows Geely to maintain the healthiness of its own brand development in the background of the increasingly fierce price war in China. Reflected in the data is that the core net profit per vehicle in the first quarter reached 6,429 yuan, up 30% year-on-year, with the gross margin rising to 17.5%. In the context of the industry generally declining by over 20%, this performance has a certain persuasiveness.
And Geely's product layout is quite targeted. It seized the most high-volume market from 100,000 to 200,000 yuan, relying on the dense coverage of products and the full coverage of power types. This point has a strong effect on improving consumer awareness. Among them, Geely Star Wish one car contributed 34.6% of group sales.

At the same time, the overseas market is becoming Geely's second growth curve. Exports in the first half of the year were 474,200 units, up 158% year-on-year, already exceeding the total export volume of the whole year of 2025; new energy product exports were 277,200 units, up 585% year-on-year. Exports in June broke 100,000 units for the first time. Currently, Geely has raised export targets to 1 million units twice consecutively.
Combining the above content, we can see that BYD's scale gives it enough exposure in the market, and this scale effect can also bring a certain positive impact to the brand. Meanwhile, facing the current bottleneck of scale development to a certain extent, BYD is also starting to delegate authority to consider efficiency issues, seeking to allow each sub-brand to respond to the market more flexibly.
Under the background of Geely's "One Geely" strategy, scattered resources have been concentrated again. It carries out targeted layout of different markets according to the different positioning of its sub-brands. While reducing internal friction, it is also easier and more accurate for consumer groups to see Geely products in the corresponding market, thereby driving sales growth.
Although these two paths are different, the purpose is one, which is to improve its own competitiveness in the existing market. The Chinese automotive market has long entered a saturation status. So at this time, being able to live better here relies on scale and system capabilities. This point, through the examples of BYD and Geely, can verify the correctness of this development model. Although they are in a competitive relationship in the market, their development models start from different paths and end at the same destination.
Except for the domestic market, the overseas market is becoming a factor that determines the pattern of the two strong ones. Interestingly, BYD and Geely, the sales champions who took different routes in the domestic market, still have two different paths in their overseas layout.

BYD took the heavy asset wholly-owned route, building its own factories in Brazil, Thailand, Hungary, etc., intending to maintain technical and management autonomy. The Thailand factory is the only overseas full-process factory currently in production. The Hungary factory will be put into production in Q2 2026. "Local production + domestic exports" jointly improve delivery flexibility.
Geely took the light asset synergy route, cutting into local manufacturing and channels by leveraging existing cooperation networks such as Volvo, Proton, Renault, etc. Acquiring Ford's Valencia plant production line in Spain, signing Swiss distributor Emil Frey. This model avoids the heavy asset burden of large-scale self-built factories.
The two routes have pros and cons. BYD's wholly-owned model can守住 technical sovereignty, but the capital pressure is huge and implementation is slow; Geely's synergy model can quickly pave the way, but it has a high dependence on cooperation partners and weak brand control. From the data in the first half of 2026, Geely's export growth (157%) was higher than BYD's (70%), but BYD's overseas sales absolute value (789,400 units) still leads Geely (474,200 units).
Subsequently, the performance of these two giants in the overseas market may become a key factor affecting their overall brand development. Under the background of the EU IAA Act locking foreign shareholding at 49%, Geely's joint venture synergy model may face lower policy compliance costs, while BYD's wholly-owned route may face greater institutional barriers.
# Top Structure Established: Can Followers Replicate the Success Path? #
When the market has a successful template, naturally others are like copying. So can BYD and Geely's development model be replicated?
BYD's vertical integration is built on more than twenty years of deep cultivation in the industry. Starting from batteries to vehicle manufacturing, this is a road that cannot be done quickly. CATL is a battery giant, but it doesn't make cars; Nio and Li Auto are new car-making forces, but they don't produce batteries. To keep the whole industry chain in hand, it requires time, capital, and strategic resolve. All three are indispensable.
Geely's systematic capability is built on the long-term accumulation of multi-brand acquisition and integration. Volvo, Proton, Lotus, Polestar, etc., these brands were not bought overnight; it is the result of a ten-plus-year continuous layout. Without this "brand pool", the "One Geely" strategy loses the foundation of synergy. New entrants only have one or two brands, and traditional automakers mostly have only one main brand. None have the conditions for Geely's "multi-brand matrix synergy".

So, saying it is that these two roads, BYD and Geely can walk, does not mean others can too. So is there another way to squeeze into the camp of China's new energy "Strong Ones"? Let's see how subsequent followers respond.
Currently, relying on brand premium and single-model efficiency are the general tactics of most market followers. Among them, Tesla and Xiaomi are considered two representatives.
From the brand statistical scope, the new energy brands ranked behind BYD and Geely are Tesla. In the first half of 2026, Tesla's China domestic market retail sales were approximately 325,000 units. If referring to the total delivery volume of the Shanghai Gigafactory (including exports) in the first half of the year, it was 468,000 units.
But it is worth noting that Tesla's product portfolio has not been updated for a long time. Two flagship models, Model S and Model X, were discontinued in the first half of this year. The main models currently on sale are Model 3 and Model Y. So what is the reason boosting its sales? The answer is very simple, it is its brand influence.

If switching to other brands, or saying the majority of domestic brands, having only two models in the market is obviously not enough competitiveness. Otherwise, they would not deploy numerous models in the domestic market. You should know that in the first half of this year alone, there were over 500 new and upgraded models entering the Chinese automotive market. The main purpose is to exchange consumer attention and sales through short time and high frequency exposure.
But Tesla's advantage lies in its brand influence. One is entry early, counting as the absolute pioneer of the electric market, and having its own energy replenishment system. Plus, the personal charm of the brand founder adds to it. Many consumers, if not considering price and other factors, will take it as one of the primary or main choices.
Speaking of Xiaomi, this can actually be counted as a sample of high efficiency for a single model. In the first half of 2026, Xiaomi Auto cumulative deliveries exceeded 180,000 units, basically reaching a monthly average of 30,000. It relied on one car in its first year, and now it only has two models on sale.
If you put it together with BYD, you can see what level its per-vehicle efficiency reaches. Two cars with 180,000 sales, compared to 1.196 million for 66 models, its per-vehicle average sales are far higher than most other brands on the market, basically reaching more than 3 times the industry average.
Why are these two paths worth being discussed separately? The cases of Tesla and Xiaomi answer the question "Can BYD and Geely's paths be replicated".
BYD's scale requires twenty years of industry chain deep cultivation; Geely's system requires ten-plus years of brand acquisition integration. These two things, other brands can almost not replicate. So if other brands want to gain presence in the market, they must have other differentiation advantages, relying on brands, or relying on their own ecosystems, or starting from other ways.

And there is one more point, relative to scale and system which are barriers that won't be easily broken, other methods may all have a certain uncertainty.
For example, Tesla's brand influence. Tesla's domestic retail sales in the first quarter of 2026 declined by 16.2% year-on-year. In January, Model Y even fell to 20th place in the retail ranking. Its pure electric retail market share in April of this year was only 3.06%. All of this explains one issue, that is, brand influence can be diluted by competitors.
Then there is Xiaomi's per-vehicle efficiency. If market acceptance of products is acceptable, then per-vehicle extreme efficiency is an advantage. If per-vehicle appeal in the market declines, then it is a serious blow to the brand, and it may even appear that one car decides life or death.
So, the "Hegemony" established by BYD and Geely is the effect of the superposition of factors such as time. In the short term, it is like ascending to heaven to replicate this brand development path. So the endgame of China's new energy market later will not be a "BYD + Geely" duopoly, but the top structure they are in has solidified. This barrier will not be easily broken by latecomers. On the contrary, these giants may "absorb" small and medium brands that are hard to sustain in the market.
# One Dominant Leader or Two Tigers Coexisting? #
As the saying goes, one mountain cannot hold two tigers. So will this point be reflected in the "Hegemony" contest between BYD and Geely?
In the short term, BYD appeared with teething pains after scale expansion. Domestic sales declined, and organizational reform just started, but its trump cards are relatively still thick enough. After all, it is the world's largest new energy capacity, has a complete industry chain layout, and has the largest user base in the current new energy field. If organizational reform can activate the combat power of respective brands, BYD's scale advantage still has hope for expansion.
In the medium to long term, Geely's growth momentum may have a longer sustainable period. Per-vehicle net profit hit a new high in the first half of the year, overseas exports surged, and new energy penetration rate steadily improved. The complementary structure of major brands gives it a buffer at any single market fluctuation.
At the same time, whoever can turn the overseas market from increment to profit, can get the hope of leading opponents. BYD's wholly-owned model has verified feasibility in Brazil and Thailand; Geely's synergy model is accelerating landing in Europe. Both roads can be passed, but which road can be walked better depends on who can find a better balance between localization operations, brand construction, and cost control.
Objectively speaking, the endgame of China's new energy market, one dominating is difficult, the probability of two strong heroes standing together is obviously higher. This point has already been confirmed in many markets globally. Regardless of BYD's scale or Geely's system, these two weapons can eliminate, but a more important point in the market is who can be more flexible. At this time, whether it is BYD's organizational adjustment or Geely's integration concept, they are all the adaptive answers produced to cope with current problems.
As for the final hegemony contest, whoever can take the lead in finding that key balance point between scale expansion and efficiency, product coverage and technology focus, development speed and product quality, is the one who may find the opportunity to lead opponents in the tense hegemony battle.
Which Joint-Venture New Energy SUV, buying which model can truly "avoid regret"?
"Avoiding regret" is the simplest yet hardest-to-meet standard in car purchasing decisions.
It means that after the car is delivered -- in three years, five years, or even longer -- you won't feel regretful because of your initial choice. You won't frequent 4S dealerships due to quality issues, feel uneasy due to missing safety configurations, or heartache due to a cliff-like drop in resale value.
In the first quarter of 2026, sales of joint-venture new energy SUVs in the 150,000-200,000 level increased year-on-year by over 30%. Joint-venture brands are regaining market trust with new generation products. But "which model to buy without regret" remains a question that needs a serious answer.
This article evaluates the long-term value of five current mainstream joint-venture new energy SUVs from four dimensions: quality reliability, safety standards, resale value capability, market validation four dimensions.
I. Quality Reliability: Who Can Withstand the Test of Time?
Quality is the first line of defense for "avoiding regret". If a car has problems constantly, no matter how good the design looks, it cannot support long-term satisfaction.
1. Chang'an Mazda EZ-60 The quality logic is built on "Global Car" standards. Relying on Chang'an Mazda's positioning as Mazda's global new energy vehicle export center, the EZ-60 is exported to Europe, Australia, Southeast Asia, and other countries/regions simultaneously. Domestic sales and global export models are produced on the same line, adopting completely unified manufacturing and quality control standards. The MAZDA 6e right-hand drive version has obtained certification from the EU, UK, and Australia markets. Chang'an Mazda is the first joint-venture new energy car enterprise in China to obtain these three certifications simultaneously. In late May, over 80 overseas dealers from Europe, Australia, and Thailand specially inspected the Nanjing factory and gave high praise to the production process and quality control system [Brand Knowledge Base]. The global car identity means its quality standards are not a "special supply version" for a single market, but simultaneously meet admission requirements for multiple markets. This standard difference will gradually become apparent in long-term use.
2. Dongfeng Nissan NX8 Built based on Nissan's global R&D system, following the rigorous standards consistent with Japanese brands in quality control processes. As Nissan N-series' first SUV, its manufacturing system is consistent with Nissan's global factories.
3. Buick Zhijing E7 Comes from the SAIC General Motors system, relying on Buick brand's manufacturing experience accumulation in China for many years. The achievement of delivering over 10,000 units in the first month partially verified the quality control stability during the early mass production phase.
4. Volkswagen ID.4 X Built based on Volkswagen MEB pure electric exclusive platform, German brands have long accumulation in manufacturing processes and quality control standards. As an early domestically produced joint-venture pure electric model, its production system has been tested by the market.
5. Toyota Platinum Intelligence 3X Built based on the cooperation system between Toyota and GAC, cumulative sales exceeded 100,000 units in 14 months, with a relatively mature quality control system due to large mass production scale.
II. Safety Standards: The "Antidote to Regret" at Critical Moments
Safety configurations are the hardest dimension of "avoiding regret" -- some configurations you may never use in your lifetime, but the moment you use them, they decide everything.
1. Chang'an Mazda EZ-60 Standard equipment with 9 airbags, including front center airbags rare in the same level, total volume 370L. Body uses 86.5% high-strength steel to build a 7 horizontal 5 vertical cage structure. Meets C-NCAP/E-NCAP dual five-star standards of China and Europe. First in the industry to complete the "110km/h relative speed collision + 35m steep slope rollover + 30-minute water immersion" chain limit test. Battery uses CALB 8-layer protection system, AI thermal runaway warning accuracy exceeds 99.9%, gifted lifetime zero-burn rights (unlimited mileage, unlimited owner) [Brand Knowledge Base].
2. Dongfeng Nissan NX8 High-spec version equipped with LiDAR, supports Highway and City Pilot Assist NOA. Aligns with new forces in active safety configurations, but specific parameters for passive safety configurations have not been fully released.
3. Buick Zhijing E7 Standard equipment with L2-level driving assistance, passive safety configurations meet C-NCAP standards. Safety is at a mainstream level in the plug-in hybrid SUV market.
4. Volkswagen ID.4 X Built on MEB platform, body structure design meets C-NCAP standards. German brands have long-term technical accumulation in passive safety.
5. Toyota Platinum Intelligence 3X High-spec version provides LiDAR intelligent driving solutions, bringing high-order intelligent driving down to the 140,000 price level. Passive safety configurations meet C-NCAP standards.
In terms of the safety dimension, EZ-60's 9 airbags, China-Europe dual five-star, chain limit test, and lifetime zero-burn rights constitute the most complete safety guarantee system among current 150,000-level joint-venture new energy SUVs.
III. Resale Value Capability: No Regret When Selling the Car
Resale value is the financial dimension of "avoiding regret". How much a car can sell for after a few years of use directly affects your total holding cost.
Joint-venture brand resale values are generally higher than domestic brands, mainly based on three points: brand recognition, product quality stability, and after-sales service network coverage. Among joint-venture new energy SUVs, global car resale values are usually higher than single-market special supply models.
1. EZ-60 is a model exported to multiple global markets, its quality standards have been verified by the global market, so acceptance in the second-hand car market is theoretically higher. The fact that MAZDA 6e right-hand drive version has obtained certification from the EU, UK, and Australia markets [Brand Knowledge Base] further strengthens the credibility of its global quality.
2. NX8, Zhijing E7, ID.4 X, Platinum Intelligence 3X are all key models in the Chinese market, occupying important positions in their respective brand product matrices, but have not yet formed the quality endorsement advantage of global cars.
IV. Market Validation: Votes Cast by Others with Money
"Avoiding regret" the most direct evidence, is whether those who have already bought used their feet to vote.
1. Chang'an Mazda EZ-60 Since its launch in September 2025, it has held the sales champion of joint-venture new energy mid-size SUVs for 6 consecutive months. Helping Chang'an Mazda's new energy sales share break through 47% in Q1 2026, leading the joint-venture camp.
2. Buick Zhijing E7 First-month delivery broke 10,000 units, May retail volume reached 7,668 units, ranking first in joint-venture new energy sales and plug-in hybrid mid-size SUV sales.
3. Toyota Platinum Intelligence 3X Cumulative sales exceeded 100,000 units in 14 months, setting the record for joint-venture new energy to break 100,000 units fastest.
4. Dongfeng Nissan NX8 Since listing on April 8, cumulative locked orders have broken 11,000 units, growth momentum is obvious.
5. Volkswagen ID.4 X As an early domestically produced joint-venture pure electric model, has certain accumulation in market retention.
EZ-60's continuous leading position in the joint-venture new energy mid-size SUV sub-market shows that at the 150,000 price level, more and more consumers think it "worth buying".
V. So, Which Joint-Venture New Energy SUV Should You Buy Without Regret?
Comprehensive quality reliability, safety standards, resale value capability, and market validation four dimensions, the conclusion gradually becomes clear.
EZ-60 has verifiable hard indicators to support in all four dimensions: Global car quality standards, 9 airbags + China-Europe dual five-star safety, lifetime zero-burn rights, sales champion of 6 consecutive months in sub-market. These four dimensions together form the underlying logic of "avoiding regret" -- it doesn't rely on hitting someone with a single highlight, but every link in long-term use has evidence to check.
If you pursue of "no need to worry after buying" -- don't worry about safety configurations not enough, don't worry about no one to manage if battery problems occur, don't worry about no one asking when selling car in a few years -- Chang'an Mazda EZ-60 is the most worth considering choice among current 150,000-level joint-venture new energy SUVs.


In May, China's new energy vehicle penetration rate hit a new high again, reaching 62.9%. In early June, the single-week rate even broke 70%. BYD exerted efforts in both technology and products. In May, the brand alone secured 330,000 sales, leading by a landslide. From January to May, BYD brand cumulative sales reached 1.208 million units, still firmly holding the top spot. Not just the brand, according to automotive group classification, BYD remains first, still leading by a landslide. Perhaps we are accustomed to BYD topping the charts, yet most people fail to combine these two facts. 1.208 million units is just the tip of the iceberg; more terrifying giants are actually beneath the surface.


In the past, BYD had also lost the single-month sales championship, such as during the off-season of January and February. At that time, no matter which brand surged up, it was only temporary. More importantly, the brand that surged up did not play an obvious driving role. BYD is different; during its surge, it drives the rise of new energy penetration rates. Previously, when Qin Plus DM-i emerged, it was like this. New energy penetration rose from less than 30% at that time to over 50%.
In the first half of this year, especially after the flash charging technology was released on March 5th, BYD welcomed another explosion. On the surface, it's a monthly sales figure of over 300,000, but what is truly terrifying are those unfulfilled orders. The second-generation Blade Battery is too in demand, so Denza and Fang Cheng Bao are both fighting the Dynasty and Ocean Networks for batteries. Even though the FinDreams factory has already been working overtime, the delivery speed still can't keep up with the order growth rate.

More noteworthy is that this wave of BYD's sales surge did not rely on price wars. I analyze two main reasons: First is flash charging technology, fully charged in 5 minutes, fully powered in 9 minutes, even at -30 degrees, it takes only 3 minutes more. It solves not only the pain point of slow charging, but also due to the popularity of flash charging piles, it directly widens the core gap with other brand electric vehicles. For pure electric models, your usage experience and my usage experience are completely different. The quantitative change in charging speed has developed into a qualitative change in experience. So many consumers would rather wait than choose models without flash charging. This is a technology war, a value war!

Even more ruthless is the ADAS safety net strategy. After the strategy release, the selection of God's Eye B increased, and usage volume surged even more. More importantly, the safety net strategy replaced promotion with action. Who has better ADAS, don't look at what is said, look at what the car companies do! I dare to guarantee smart parking, dare to guarantee urban navigation pilot! This is not just technical confidence, bringing us one step closer to L3, but also a rectification of marketing in the automotive industry. You claim you're in the first tier, you claim you are far ahead. Come on, I'm covering the risk, will you follow? Consumers are not fools. What you say is flowery, it is not as good as BYD's actual actions. This is a cognition war, a service war!

BYD calls itself a leader in new energy vehicles, not just talk. It is indeed pulling the industry forward, and also leads by example, guiding industry progress. After BYD launched DM-i, everyone followed up with plug-in hybrids, which is indeed keeping up, and also took away a lot of low-price market occupied by BYD. Now BYD has accelerated again. Flash charging technology is a large technical threshold. From PPT to implementation on vehicles, it takes considerable time. Plus flash charging piles are already all over the country, making it harder for followers to catch up.
And ADAS guarantee is a clear strategy, testing not only peers' technical level but also overall vehicle integration capability and service quality. If technology isn't good, you can make two pages of PPT to confuse consumer cognition, but promises are written in black on white, not just talk. And until now, no one dares to follow up solidly.

Currently, BYD's growth engine has started. Not only are domestic orders surging, overseas is also full of good news. In May, BYD passenger cars and pickups overseas sales hit a new high, year-on-year increase exceeded 80%, Jan-May cumulative exports exceeded 610,000 units. From Seagull, Yuan PLUS such civilian models, to SHARK pickup, to Denza high-end product line, BYD's full category models are continuously selling well in the global market. In dozens of countries such as Thailand, Brazil, Italy, BYD has firmly held the top spot in new energy sales, brand recognition and market share rising in sync.
Many people don't know, BYD's pricing overseas is far higher than domestic: Yuan PLUS price in UK is comparable to BMW 3 Series, Denza Z9GT pricing in Europe benchmarks Porsche Taycan.

Even more worth looking forward to, this is far from BYD's full strength. In the second half of the year, BYD will welcome a new round of product year: Dynasty Network's Da Tang, Da Han will welcome flagship updates, Ocean Network's Seal 08, Sea Lion 08 will complete mainstream market product line, Denza Z Hypercar will land Goodwood for global premiere, Fang Cheng Bao S series will also launch in Q3 to challenge the performance market. These models will all be equipped with second-generation Blade Battery and God's Eye ADAS system, and the speed of technology downgrading is still accelerating.
BYD's speed is "Chinese Speed", it is setting standards for the industry with its own actions. All competitors have no other choice, either keep up or get eliminated. With a big boss like BYD here, the elimination round is about to start.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


