

HomeFood

Search History
Popular Searches
Dealer Login / Sign Up
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿 Honda HR-V 同 Mazda CX-5 嚟做比較。這兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一個詳細對比,幫你省咗做功課嘅時間。
Honda HR-V 喺馬來西亞嘅 OTR 售價係 RM 115,900 - 143,900,一共有 4 個版本,包括 2026 e:HEV 1.5L RS(RM 143,900)、2026 1.5T V(RM 137,900)、2026 1.5T E(RM 130,900) 等。
Mazda CX-5 喺馬來西亞嘅 OTR 售價係 RM 135,469 - 166,760,一共有 3 個版本,包括 2025 2.0L AT 35th Anniversary(RM 316,154)、2025 2.0L AT(RM 296,154)、2025 2.0L MT(RM 294,154) 等。
從價錢睇落,Honda HR-V 嘅起步價確實比 Mazda CX-5 平咗 RM 19,569。如果你預算有限,Honda 嘅入門版已經可以滿足日常需要。但都要注意,平嗰幾千蚊,可能喺配備上會有取舍,具體要看你嘅需要。

Honda HR-V 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
Mazda CX-5 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
兩款車用緊同一套動力系統,日常行車嘅感覺基本冇乜分別。油耗方面都幾接近,唔使太糾結這一點。

Honda HR-V 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 Honda SENSING (ACC, CMBS, LKAS, RDM)。
Mazda CX-5 嘅安全評級係 5★ (ASEAN NCAP),主動安全系統包括 。
兩款車嘅安全評級一樣,喺呢個級別入面安全配備都算畀得好齊全。而家嘅新車安全性都唔差,唔使太擔心這一點。

Honda HR-V 車身長 4500 mm,行李箱 450 L。
Mazda CX-5 車身長 4500 mm,行李箱 450 L。
兩款車嘅尺寸幾近一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。

Honda HR-V 保養保修 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。
Mazda CX-5 保養保修 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。

總嚟講,Honda HR-V 同 Mazda CX-5 都係馬來西亞市場幾唔錯嘅車型。揀邊一輛,關鍵始終係睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花點時間做功課絕對唔會錯。

在馬來西亞嘅 SUV 市場,好多買家揀車嗰陣都會拿本田 HR-V 同馬自達 CX-5 嚟做比較。呢兩款車喺價位同定位上都幾相近,今日我哋就從多個角度做個詳細對比,幫你省返做功課嘅時間。
本田 HR-V 喺馬來西亞嘅 OTR 售價係 RM 115,900 - 143,900,合共有 4 個版本,包括 2026 e:HEV 1.5L RS(RM 143,900)、2026 1.5T V(RM 137,900)、2026 1.5T E(RM 130,900)等。
馬自達 CX-5 喺馬來西亞嘅 OTR 售價係 RM 135,469 - 166,760,合共有 3 個版本,包括 2025 2.0L AT 35th Anniversary(RM 316,154)、2025 2.0L AT(RM 296,154)、2025 2.0L MT(RM 294,154)等。
由價錢睇落,本田 HR-V 嘅起步價確實比馬自達 CX-5 平咗 RM 19,569。如果你預算有限,本田嘅入門版已經可以滿足日常需要。但都要注意,平嗰幾千蚊,喺配備上可能會有所取捨,具體睇返你需要。
本田 HR-V 配備 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
馬自達 CX-5 配備 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
兩款車用咗同一套動力系統,日常開起嚟嘅感受基本冇乜分別。油耗方面都差不多,唔使太糾結呢一點。
本田 HR-V 車身長 4500 mm,行李廂 450 L。
馬自達 CX-5 車身長 4500 mm,行李廂 450 L。
兩款車嘅尺寸幾乎一樣,車內空間差別唔大。呢個級別嘅車,日常使用完全夠用。
本田 HR-V 採用 FWD 驅動方式。
馬自達 CX-5 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
本田 HR-V 保養 5 年/無限制里程,保養間隔 每 10,000km 或 6 個月。
馬自達 CX-5 保養 5 年/150,000km,保養間隔 每 10,000km 或 6 個月。
總括嚟講,本田 HR-V 同馬自達 CX-5 都係馬來西亞市場好唔錯嘅車款。揀邊部,關鍵都要睇返你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,先至去試駕做最後決定。買車係件大事,花少少時間做功課絕對唔會錯。
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿本田 HR-V 同馬自達 CX-5 嚟做比較。呢兩款車喺價位同定位上都幾接近,今日我哋就從多個方面做一個詳細嘅比較,幫你慳返做功課嘅時間。
本田 HR-V 喺馬來西亞嘅 OTR 售價係 RM 115,900 - 143,900,一共有 4 個版本,包括 2026 e:HEV 1.5L RS(RM 143,900)、2026 1.5T V(RM 137,900)、2026 1.5T E(RM 130,900)等。
馬自達 CX-5 喺馬來西亞嘅 OTR 售價係 RM 135,469 - 166,760,一共有 3 個版本,包括 2025 2.0L AT 35th Anniversary(RM 316,154)、2025 2.0L AT(RM 296,154)、2025 2.0L MT(RM 294,154)等。
由價錢睇,本田 HR-V 嘅起價確實比馬自達 CX-5 平咗 RM 19,569。如果你預算有限,本田嘅入門版已經可以滿足日常需要。不過都要注意,平啲錢,可能喺配備上會有取舍,具體要睇你嘅需要。
本田 HR-V 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
馬自達 CX-5 搭載 1.5L Turbo,馬力 140 hp。官方油耗 7.0 L/100km。
兩款車用緊同一套動力系統,日常開嘅感覺基本無分別。油耗方面都差唔多,唔使太糾結呢一點。
本田 HR-V 車身長 4500 mm,行李廂 450 L。
馬自達 CX-5 車身長 4500 mm,行李廂 450 L。
兩款車嘅尺寸幾乎一樣,車內空間分別唔大。呢個級別嘅車,日常使用完全夠用。
本田 HR-V 採用 FWD 驅動方式。
馬自達 CX-5 採用 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感覺唔會有太大分別。
本田 HR-V 同馬自達 CX-5 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰款;如果你更在意性價比同配備,那就揀配備更豐富嗰款。最後始終建議兩款都去試駕,親身試過先至最重要。
總體嚟講,本田 HR-V 同馬自達 CX-5 都係馬來西亞市場幾唔錯嘅車型。揀邊部車,關鍵都要睇你嘅個人需要同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花啲時間做功課絕對錯唔過。
In the Malaysian SUV market, many buyers compare Honda HR-V and Mazda CX-5 when selecting a car. These two models are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
The OTR price for Honda HR-V in Malaysia is RM 115,900 - 143,900, with a total of 4 versions, including 2026 e:HEV 1.5L RS (RM 143,900), 2026 1.5T V (RM 137,900), 2026 1.5T E (RM 130,900), etc.
The OTR price for Mazda CX-5 in Malaysia is RM 135,469 - 166,760, with a total of 3 versions, including 2025 2.0L AT 35th Anniversary (RM 316,154), 2025 2.0L AT (RM 296,154), 2025 2.0L MT (RM 294,154), etc.
From a price perspective, the starting price of Honda HR-V is indeed RM 19,569 cheaper than Mazda CX-5. If your budget is limited, Honda's entry-level version can already meet daily needs. However, note that the few thousand cheaper might involve trade-offs in features, depending on your specific needs.
Honda HR-V body length 4500 mm, trunk capacity 450 L.
Mazda CX-5 body length 4500 mm, trunk capacity 450 L.
The dimensions of both cars are almost identical, with little difference in interior space. For this class of vehicles, it is completely sufficient for daily use.
Honda HR-V adopts FWD drive method.
Mazda CX-5 adopts FWD drive method.
The drive method of both cars is the same, both are FWD, so there won't be much difference in daily driving feel.
Honda HR-V and Mazda CX-5 are both mainstream choices in the Malaysia market, suitable for family use and daily commuting. If you value brand reputation and resale value more, you can prioritize the one with better reputation; if you care more about value for money and features, then choose the one with richer configuration. Ultimately, it is recommended to test drive both models, as personal experience is the most important.
Overall, Honda HR-V and Mazda CX-5 are both very good car models in the Malaysia market. Which one to choose depends on your personal needs and budget. We suggest doing research, comparing quotes from multiple dealerships, and then test driving to make the final decision. Buying a car is a major matter, spending time on research will definitely not be wrong.
In Malaysia's SUV market, many buyers compare Honda HR-V and Mazda CX-30 when selecting a car. These two models are quite close in price and positioning. Today we will make a detailed comparison from multiple aspects to help you save time on research.
The OTR price of Honda HR-V in Malaysia is RM 115,900 - 143,900, with a total of 4 versions, including 2026 e:HEV 1.5L RS (RM 143,900), 2026 1.5T V (RM 137,900), 2026 1.5T E (RM 130,900), etc.
The OTR price of Mazda CX-30 in Malaysia is RM 122,409 - 146,409, with a total of 4 versions, including 2025 2.0L High+ Premium (RM 146,409), 2025 2.0L High+ (RM 138,409), 2025 2.0L High (RM 130,409), etc.
From the price perspective, the starting price of Honda HR-V is indeed RM 6,509 cheaper than Mazda CX-30. If your budget is limited, Honda's entry-level version can already meet daily needs. But note that the price difference of a few thousand might involve trade-offs in features, depending on your specific needs.
Honda HR-V is equipped with 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
Mazda CX-30 is equipped with 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
Both cars use the same powertrain, and the driving experience feels basically the same. Fuel economy is also similar, so no need to worry too much about this point.
Honda HR-V safety rating is 5★ (ASEAN NCAP), active safety systems include Honda SENSING (ACC, CMBS, LKAS, RDM).
Mazda CX-30 safety rating is 5★ (ASEAN NCAP), active safety systems include i-Activsense.
Both cars have the same safety rating, safety features are quite comprehensive for this class. New car safety is generally good these days, no need to worry too much about this.
Honda HR-V uses FWD drive system.
Mazda CX-30 uses FWD drive system.
Both cars have the same drive system, both are FWD, daily driving experience won't differ much.

Overall, Honda HR-V and Mazda CX-30 are both very good models in the Malaysian market. Which one to choose depends on your personal needs and budget. It is recommended to do thorough research, compare quotes from several dealerships, and then test drive to make the final decision. Buying a car is a major matter, spending some time on research will never be wrong.
In Malaysia's SUV market, many buyers compare the Honda HR-V and Toyota Corolla Cross when choosing a car. These two models are quite close in price and positioning. Today we will make a detailed comparison from multiple aspects to help you save time on research.
Honda HR-V has an OTR price in Malaysia of RM 115,900 - 143,900, with a total of 4 versions, including 2026 e:HEV 1.5L RS (RM 143,900), 2026 1.5T V (RM 137,900), 2026 1.5T E (RM 130,900), etc.
Toyota Corolla Cross has an OTR price in Malaysia of RM 133,800 - 148,800, with a total of 3 versions, including 2026 HEV 1.8L GR Sport (RM 148,800), 2026 HEV 1.8L Standard (RM 140,800), 2026 1.8L Standard (RM 133,800), etc.
In terms of price, the starting price of the Honda HR-V is indeed RM 17,900 cheaper than the Toyota Corolla Cross. If your budget is limited, Honda's entry-level version can already meet daily needs. However, also note that the few thousand cheaper might involve trade-offs in features, depending on your specific needs.
Honda HR-V is equipped with 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
Toyota Corolla Cross is equipped with 1.5L Turbo, 140 hp. Official fuel consumption 7.0 L/100km.
Both cars use the same powertrain, the driving feel is basically the same in daily use. Fuel consumption is also about the same, no need to worry too much about this point.
Honda HR-V body length 4500 mm, trunk 450 L.
Toyota Corolla Cross body length 4400 mm, trunk 400 L.
In terms of space, the Honda HR-V's body is 100 mm longer than the Toyota Corolla Cross, making the interior seating space slightly more spacious, especially the rear legroom. If you frequently carry family or need to fit a stroller, the larger body is indeed more practical.
Honda HR-V adopts FWD drive configuration.
Toyota Corolla Cross adopts FWD drive configuration.
Both cars have the same drive configuration, both FWD, no significant difference in daily driving feel.

Honda HR-V warranty 5 years/unlimited mileage, service interval every 10,000km or 6 months.
Toyota Corolla Cross warranty 5 years/unlimited mileage, service interval every 10,000km or 6 months.
Both cars have the same warranty conditions, no need to worry about this aspect. Actual maintenance costs also depend on the brand's service network and parts prices, it is recommended to ask real car owners in car owner groups for their experiences.

In general, Honda HR-V and Toyota Corolla Cross are both excellent models in the Malaysian market. Which one to choose depends mainly on your personal needs and budget. It is recommended to do your research, compare quotes from several car dealerships, and test drive to make the final decision. Buying a car is a big matter, spending some time on research will definitely not be wrong.
Dalam pasaran SUV di Malaysia, ramai pembeli semasa memilih kereta akan membandingkan Honda HR-V dan Mazda CX-30. Kedua-dua kereta ini mempunyai harga dan posisi yang sangat hampir, hari ini kita akan membuat perbandingan terperinci dari pelbagai aspek, membantu anda menjimatkan masa untuk mengkaji.
Harga OTR Honda HR-V di Malaysia adalah RM 115,900 - 143,900, terdapat 4 varian, termasuk 2026 e:HEV 1.5L RS (RM 143,900), 2026 1.5T V (RM 137,900), 2026 1.5T E (RM 130,900) dan lain-lain.
Harga OTR Mazda CX-30 di Malaysia adalah RM 122,409 - 146,409, terdapat 4 varian, termasuk 2025 2.0L High+ Premium (RM 146,409), 2025 2.0L High+ (RM 138,409), 2025 2.0L High (RM 130,409) dan lain-lain.
Dari segi harga, harga permulaan Honda HR-V memang lebih murah sebanyak RM 6,509 berbanding Mazda CX-30. Jika bajet anda terhad, varian asas Honda sudah boleh memenuhi keperluan harian. Tetapi perlu diingat, ribuan ringgit yang lebih murah itu, mungkin ada pengurangan pada kelengkapan, bergantung pada keperluan anda.
Penarafan keselamatan Honda HR-V ialah 5★ (ASEAN NCAP), sistem keselamatan aktif termasuk Honda SENSING (ACC, CMBS, LKAS, RDM).
Penarafan keselamatan Mazda CX-30 ialah 5★ (ASEAN NCAP), sistem keselamatan aktif termasuk i-Activsense.
Penarafan keselamatan kedua-dua kereta adalah sama, kelengkapan keselamatan dalam kelas ini dianggap cukup lengkap. Keselamatan kereta baru sekarang tidak buruk, tiada perlu bimbang tentang hal ini.
Honda HR-V menggunakan konfigurasi penggerak FWD.
Mazda CX-30 menggunakan konfigurasi penggerak FWD.
Konfigurasi penggerak kedua-dua kereta adalah sama, iaitu FWD, pengalaman memandu harian tidak akan berbeza banyak.
Honda HR-V mempunyai waranti 5 tahun/tanpa had jarak, selang penyelenggaraan setiap 10,000km atau 6 bulan.
Mazda CX-30 mempunyai waranti 5 tahun/150,000km, selang penyelenggaraan setiap 10,000km atau 6 bulan.
Honda HR-V dan Mazda CX-30 adalah pilihan utama pasaran Malaysia, sesuai untuk kegunaan keluarga dan perjalanan harian. Jika anda lebih mengutamakan reputasi jenama dan harga jual semula, boleh pertimbangkan model yang lebih mempunyai reputasi; jika anda lebih mementingkan nilai harga dan kelengkapan, pilih model yang kelengkapannya lebih lengkap. Akhir sekali, disarankan untuk mencuba kedua-dua model untuk uji jalan, pengalaman sendiri adalah yang paling penting.
Secara keseluruhannya, Honda HR-V dan Mazda CX-30 adalah model kereta yang sangat bagus di pasaran Malaysia. Memilih yang mana, penting bergantung kepada keperluan peribadi dan bajet anda. Kami menasihatkan anda untuk mempelajari dengan rapi, bandingkan banyak tawaran harga daripada pengedar kereta, kemudian uji jalan untuk membuat keputusan akhir. Membeli kereta adalah perkara besar, meluangkan masa untuk mempelajari tidak akan salah.
There is a simple yet brutal formula in the tire industry: sales growth does not necessarily lead to profit growth.
When raw material prices rise, product prices are pressured, and trade barriers increase, the more companies sell, the greater the cost and financial pressure they may even bear. Therefore, what deserves more attention than revenue growth is whether profits grow synchronously, and whether the growth comes from price hikes, capacity expansion, or improvements in operational efficiency and product structure.
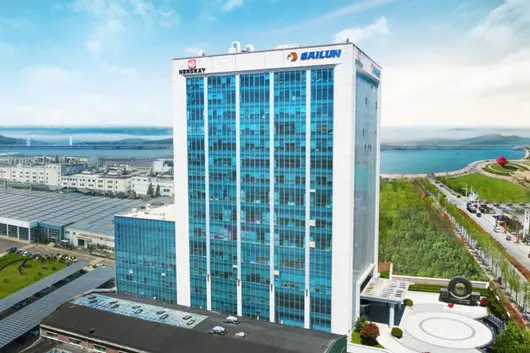
On the evening of August 30, Sailun Group disclosed its semi-annual report for 2026. In the first half of the year, the company realized revenue of 20.027 billion yuan, up 13.88% year-on-year; net profit attributable to shareholders of the listed company was 2.16 billion yuan, up 17.97% year-on-year. Tire production reached 46.97 million units, up 15.70% year-on-year; sales reached 45.01 million units, up 14.99% year-on-year, with both production and sales hitting historical highs for the same period.
Calculated based on semi-annual and first-quarter report data, Sailun realized revenue of 10.57 billion yuan in the second quarter, up 15.16% year-on-year; net profit attributable to shareholders was 1.10 billion yuan, up 39.26% year-on-year. The profit growth rate was significantly higher than the revenue growth rate, becoming the most noteworthy signal in this semi-annual report.

Sales grew by nearly 15%, but Sailun is not making money by raising prices
If looking only at production and sales volumes, this is a typical answer sheet for scale growth. But when price and cost data are placed together, the quality of the growth becomes apparent.
Operating data for the second quarter disclosed by Sailun shows that the comprehensive procurement prices of the company's four main raw materials, natural rubber, synthetic rubber, carbon black, and steel cord, increased by 6.81% year-on-year and 15.85% quarter-on-quarter; meanwhile, the average price of self-produced and self-sold tires decreased by 2.54% year-on-year. This means that Sailun's profit growth in the first half of the year was not built on a general price increase for products, but was achieved in the cracks of "rising raw material prices and pressured average tire prices".
Calculated by operating revenue and operating cost, Sailun's gross margin in the first half of the year was approximately 26.99%, an increase of about 2.45 percentage points compared to the same period last year; net profit margin was approximately 10.79%, an increase of about 0.38 percentage points compared to the same period last year. Net cash flow from operating activities reached 1.03 billion yuan, up 16.89% year-on-year.
The simultaneous improvement in sales volume, gross margin, net profit, and operating cash flow indicates that Sailun is converting new capacity and market orders into higher-quality growth, rather than just trading low prices for scale.

Overseas factories are not just "replicating capacity," but are restructuring trade routes
In the past, the globalization of Chinese tire companies mainly relied on exports: producing domestically and then shipping products overseas. It brought scale, but was also easily affected by tariffs, shipping prices, and changes in regional trade policies. Sailun is trying another path: moving production bases, supply chains, channels, and services closer to major consumer markets together.
Currently, Sailun's Vietnam and Cambodia factories have entered a stable high-production period, Indonesia and Mexico factories continue to increase capacity, and the Egypt project is advancing. According to the plan disclosed by the company, Sailun overseas has a total annual production plan of 12.75 million all-steel radial tires, 89 million passenger car radial tires, and 130,000 tons of off-road tires.

From a layout logic perspective, Sailun's overseas factories are no longer simple replication of domestic capacity, but are separately undertaking regional supply functions for the North American, European, Southeast Asian, Middle Eastern, and African markets. When trade barriers increase, multi-regional manufacturing can reorganize orders, capacity, and delivery routes; when shipping prices fluctuate, localized production helps shorten delivery distances for some markets; when Chinese automobile brands accelerate going global, Sailun also has the foundation to follow vehicle manufacturers to carry out overseas matching.
Globalization is thus no longer just "selling more tires," but gradually becoming a set of infrastructure for Sailun to resist external fluctuations and undertake global orders.
What truly determines the profit ceiling is still the product structure
Scale can determine how fast a tire company can go, while products determine how far it can go.
In the first half of the year, Sailun continued to cover segmented working conditions such as new energy commercial vehicles, long-haul lines, heavy-duty transport, and mining areas in the all-steel tire field; in the passenger car radial tire field, the high-end summer sports UHP product US61 achieved production, and multiple winter tires obtained European TÜV Mark certification; off-road tires continued to upgrade around giant engineering radial tires, wear resistance, and anti-cutting technology.

Sailun US61 Successfully Matched with FAW Hongqi 2026 Model H7 PHEV
These products mostly target markets with higher technical requirements and more segmented usage scenarios. For tire companies, relying solely on production expansion is easily affected by price competition and cost fluctuations. Improving added value through high-end and differentiated products is more helpful in enhancing profitability stability. Sailun's profit growth rate in the first half of the year was higher than its revenue growth rate, at least indicating that its scale expansion did not come at the obvious expense of profitability.
The more factories, the more digitalization is not just "icing on the cake"
After the number of global factories increased, what enterprises face is not just more capacity, but also the complexity of procurement, production scheduling, inventory, quality standards, and cross-regional delivery.
Sailun is advancing AI visual quality inspection, AGV automatic logistics, and APS intelligent scheduling on the production side, and promoting the replication of process standards between different factories through the MTD system; on the supply chain and channel side, it is building domestic dealer B2B, store service systems, overseas B2B portals, and container logistics visualization platforms.
These systems have not yet disclosed separate cost-saving amounts, and profit growth cannot be simply attributed entirely to digitalization. But they solve a very real problem in global expansion: how to make an increasing number of factories operate according to similar efficiency, quality, and delivery standards.
If overseas bases solve "where to produce," then digitalization solves "how to turn global factories into a network." This is also the important capability foundation that allows Sailun to maintain profit and operating cash flow improvement while production and sales volume grow.
From Selling Products to Building Global Credit
Tires are a product that highly depends on safety trust and long-term reputation. The higher the level of original equipment matching and overseas markets an enterprise enters, the more important brand, compliance, and sustainable development capabilities become.
In 2026, Sailun ranked 10th in the Brand Finance Global Most Valuable Tire Brands list, the highest-ranking Chinese tire brand; in the "China Top 500 Most Valuable Brands" list released by the World Brand Laboratory, it ranked 97th with a brand value of 125.19 billion yuan, entering the top 100 for the first time; and was selected for the Fortune China 500 Strong list for two consecutive years.

In the ESG field, Sailun became the first Chinese tire industry enterprise to pass SBTi Science-Based Targets official verification, with an MSCI ESG rating reaching AA level. According to the semi-annual report disclosure, after verification by relevant institutions, the full lifecycle carbon emissions per 1000 kilometers driven for Liquid Gold truck and bus tires and passenger car tires decreased by 39% and 27% respectively compared to ordinary material tires of the same specification.
These ratings and data will not directly become current period profits, but may affect whether an enterprise can enter international customer supply chains, obtain high-end matching projects, and maintain market access in an environment where overseas regulations are constantly tightening.
Industry Comment: What Signal Does Sailun's "Double Increase" Release?
Sailun's performance in the first half of the year indicates that in the stage where the profit space in the tire industry is squeezed, advantages in a single dimension are difficult to sustain continuous growth. The increase in production and sales volume constitutes the direct basis for Sailun's performance growth. At the same time, overseas bases enhance global supply capabilities, product upgrades improve growth structure, and digitalization and ESG construction support the long-term stability of globalization operations.
However, there is still uncertainty in raw material prices, international trade policies, overseas project ramp-up, and digestion of new capacity. In the future, whether overseas factories can maintain a reasonable utilization rate, whether the proportion of high-value-added products can continue to increase, and whether brand and ESG investment can be further converted into market recognition and product premiums will determine the sustainability and quality of Sailun's growth.
From this semi-annual report, Sailun has begun to cross the most common "scale trap" of Chinese tire enterprises: no longer pursuing only capacity and sales, but attempting to combine global manufacturing, technological R&D, product structure, channel services, and brand credit into a set of systemic capabilities. Its growth logic is shifting further from "scale leadership" to "system capability leadership"—this may also be the watershed for the next stage of global competition for Chinese tire enterprises.
26 Ogos, dengan tema "Kebahagiaan yang Stabil" pelancaran Fulwin T7 diadakan seperti yang dijadualkan, SUV elektrik tulen berkualiti global asli ini rasmi diperkenalkan kepada pengguna. Kereta baru ini melancarkan tiga versi jarak 600km, harga panduan pelancaran 9.79‑11.89 puluh ribu Yuan, harga pertukaran awal 9.49‑11.59 puluh ribu Yuan, penghantaran dibuka serta-merta selepas pelancaran.

Pelantun Muzik Terkenal Wu Kequn sebagai Pakar Pengalaman Kebahagiaan menghadiri sendiri lokasi pelancaran, bersama Pengarah Urusan Eksekutif Kereta Chery Li Xueyong melaksanakan perbincangan mendalam mengenai "Kebahagiaan yang Stabil", kongsi pemahaman mengenai pengangkutan keluarga, kedua-dua pihak bersetuju dengan falsafah membina kereta baik melalui kesabaran, memulakan "Rancangan Penciptaan Kebahagiaan Bersama" Fulwin T7 di tempat, mengajak orang ramai menangkap detik kebahagiaan yang kecil dalam kehidupan seharian, membiarkan orang ramai melihat sebuah SUV elektrik keluarga, bagaimana mengubah rasa bahagia yang abstrak kepada kekuatan produk yang boleh dilihat dan disentuh.

sekarang persaingan pasaran kenderaan baharu elektrik semakin sengit, ramai model mengejar iterasi pantas, kemasukan pantas, menganut logik membina kereta yang "hanya cepat yang bertahan". Manakala Fulwin T7 mengambil jalan yang berbeza, memegang pemikiran jangka panjang "Kereta Global Tidak Boleh Laju", tidak mengambil jalan pintas membangunkan di dalam negara kemudian ubah suai mudah untuk eksport, dari fasa pembangunan, ia telah ditakrifkan produk untuk 210 negara dan wilayah di dunia, melakukan penyelidikan awal peraturan global dua tahun lebih awal, menyaing piawaian keselamatan 5 bintang versi 2026 E-NCAP, melaksanakan pembangunan kenderaan penuh, menyelesaikan lebih 5,000 tinjauan pengguna global, mengunjungi 15 negara tipikal, memasukkan keadaan jalan, iklim, tabiat penggunaan di wilayah berbeza ke dalam takrifan produk, kitaran penyelidikan dan pembangunan tiga tahun, 10 pusat reka bentuk utama di dunia, ratusan pereka menggabungkan usaha, digabungkan dengan lebih 5,000 penyertaan pengguna dalam penciptaan bersama, 81 kereta ujian ketahanan ke seluruh dunia, kenderaan penuh telah lengkap lebih 6 juta kilometer ujian, di mana jarak pengesahan ketahanan khusus mencapai 1.45 juta kilometer, melintasi tujuh kategori lingkungan terhad seperti suhu tinggi, sejuk melampau, lembap tinggi, garam tinggi, merekasi seluruh Brazil tinggi kelajuan bukit, jalan batu kerikil Mexico, belokan kelajuan tinggi Jerman, jalan tanah tidak bertembok Afrika Selatan dan sebahagian besar keadaan jalan tipikal di dunia, menyelesaikan ujian jalan sebenar di keadaan ekstrem seperti musim sejuk melampau Eropah Utara, panas terik Timur Tengah, banjir hujan Asia Tenggara, semua risiko seperti bunyi bising, kebolehpercayaan, keupayaan adaptasi alam, diselesaikan secara tertutup semasa fasa penyelidikan dan pengesahan.

Chery mempunyai dasar terulung sebagai pengeluar kenderaan penumpang jenama China nombor satu dalam eksport berturut-turut 23 tahun, skala pengguna global melebihi 20 juta, produk dieksport ke lebih 130 pasaran luar negara, model asal Fulwin T7, Lepas L6 sudah memasuki pasaran Afrika Selatan, Thailand, susulan akan memasuki Indonesia, EU, Australia, New Zealand, UK, Israel, Malaysia, dll. dan tampil di Minggu Reka Bentuk Milan mendapat好评 luar negara, sebelum dilancarkan rasmi di dalam negara, Fulwin T7 sudah meninggalkan jejak ujian jalan di benua, menerima perhatian dan pengiktirafan daripada media luar negara termasuk Associated Press, jurutera penyelidikan dan pembangunan luar negara menyokong di lokasi pelancaran, pemilik pertama juga termasuk pengguna asing yang tinggal di dalam negara, peringatan penghantaran serta-masa selepas pelancaran, juga mengesahkan kereta global ini sudah menyelesaikan ujian global, kembali stabil ke pasaran domestik, melayani pengguna keluarga domestik.

pada tahap jarak yang paling dikhuatiri pengguna, Fulwin T7 menolak taktik pembezaan jarak biasa dalam industri, setiap model dilengkapi bateri Rhinoceros 65.05kWh, jarak CLTC mencapai 600km, ujian sebenar mencapai 681.6km, realisasi penandaan silang, cas pantas 30%-80% hanya perlu 20 minit, dalam masa minum secawan kopi, boleh cas 300km, kitaran hayat bateri melebihi 2500 kali, kitaran penggunaan kenderaan penuh tidak perlu menukar bateri, setiap model dilengkapi AC pam haba dua sumber luas teras suhu ditambah PTC voltan tinggi, dilengkapi dengan gril udara pintar AGS, beroperasi stabil dalam lingkungan suhu besar -30℃ hingga 55℃, pada keadaan -10℃, jarak boleh meningkat 15%-20%, sama ada musim sejuk Utara, atau panas Selatan, boleh menekan perubahan besar jarak, benar-benar membuat bandar besar jauh, bandar kecil kurangkan cas, mengurangkan kebimbangan jarak. 178kW kuasa puncak 12-in-1 Penghantaran Elektrun Kun Peng, kecekapan gabungan sehingga 90.8%, menyeimbangkan output kuasa dan prestasi penjimatan tenaga, kelajuan maksimum boleh mencapai 180km/h, stok kuasa cukup, untuk perjalanan harian, menyalak di lebuh raya semuanya cukup.

ruang dan keselesaan adalah fokus utama model keluarga, jarak roda 2700mm membawa 84% kadar ruang dalaman, ruang kepala dalaman, ruang kaki barisan belakang cukup, lantai rata sepenuhnya, perjalanan penuh tidak akan sesak, kerusi menggunakan struktur komposit awan 9 lapisan, menyokong fungsi pemanasan dan pengudaraan, musim sejuk naik panas cepat, musim panas pengudaraan, penggunaan lama tidak mudah letih, kerusi belakang menyokong pelipat 4/6 nisbah, boleh meluaskan mod katil rata 1955mm x 1310mm, berkemah rehat tengah hari, berhenti perjalanan jauh sangat praktikal, volim bonet belakang biasa 450L, punya ruang storan lapisan, terbenam, volim maksimum meluas 1550L, peralatan perjalanan besar kecil boleh disusun rapi, dalaman penuh dengan kotak storan, tempat payung, pengecasan pelbagai antara muka, reka bentuk terperinci cukup menjaga pelbagai keperluan kecil penggunaan harian keluarga.

reka bentuk luaran menyatukan estetika Timur dan estetika global, badan kereta 0.286Cd rintangan angin rendah melampau, hadapan bawa angin digabungkan dengan lampu pisau angin, garisan lancar. menyediakan 6 warna kenderaan khusus, di mana warna Oren Api Membara menggunakan teknologi cat 3 lapisan Tri-coat kelas mewah, menunjukkan perubahan warna kaya di bawah cahaya berbeza, kabin Sayap Awan memeluk menghubungkan garisan pusat kawalan dan panel pintu secara semula jadi, digabungkan dengan pembesar suara terapung bentuk batu kerikil, teknologi sulaman belah, memiliki 2 paduan dalaman Hitam Coklat Hangat, Hitam Obsidian Malam, menyeimbangkan kualiti kelas atas dan ketahanan penggunaan keluarga, sama ada pengguna domestik atau pengguna luar negara, boleh cari gaya kegemaran.

keselamatan adalah garis dasar "Kebahagiaan yang Stabil", Fulwin T7 membuatkan lapisan keselamatan cukup lebihan, badan Batu Karang menggunakan struktur sangkar 9 melintang 5 menegak, keluli kekuatan tinggi 80%, struktur Shotgun unik di kelas, memperkenalkan rak bingkai ganda bersama balingan pakej, berbagai laluan pemindahan daya menyebarkan impak perlanggaran, diselaras dengan batang pengukuang ambang, membina ruang tinggal kabin penumpang yang kukuh, konfigurasi beg udara keselamatan 9 paling banyak di kelas, mencangkumi beg udara jauh 48L dan tirai sisi panjang satu badan, semasa perlanggaran memberi perlindungan lengkap untuk semua, Bateri Rhinoceros membawa struktur perlindungan 31 lapisan 6D Armor, tahap kalis air IP68 mencapai 96 kali piawaian negara, keupayaan tahan rempuk sisi dua kali piawaian negara, mengalami uji kabus garam seribu jam, uji api lebih piawaian negara, dari tahan rempush, anti tikaman, tahan kakisan, tahan panas, pelbagai dimensi elak risiko terma, chassis disetel oleh pasukan pakar antarabangsa, capai nisbah beban gandar 50.8:49.2 emas, suspensi bebas 4 roda, dengan bushing 70mm, rod stabilizer depan 26mm, uji eland 80km/h, keterusan air 500mm, hadapi jalan bergelombang, air terkumpul, chassis ada cukup margin prestasi, kelajuan tinggi badan stabil tidak terapung, sistem brek One-Box line respon brek pantas, semasa mengumpul tenaga kinetik efisien, menyeimbangkan keupayaan elak bahaya dan prestasi jimat tenaga.

pada pengalaman pintar, Fulwin T7 menggunakan cip 8775 integrasi kabin-pemanduan 4nm teknologi peringkat pertama di kelas, daya pengiraan 72 TOPS, respons sistem sehingga 80ms, koordinasi integrasi kabin-pemanduan lancar, skrin besar 2.5K kecerahan tinggi 15.6 inci, dilengkapi dengan Kabin Pintar Lingxi 2.0 dan model besar Doubao, melaksanakan interaksi suara tidak rasmi semula jadi, punya pelbagai mod perbualan menarik, rehat kecil, bangun, bayi, berkemah, dll. mod skenario tukar satu butang, 22 perkakas pengesan ketepatan tinggi, menyangkut 300+ parkir automatik semua skenario, menyokong parkir merentasi tingkat, 100 meter undur ikut laluan, hadapi tempat parkir sempit, tempat parkir tidak menentu tidak lagi sukar, bantuan pemanduan lebuh raya boleh ramal keadaan jalan, perjalanan jauh lebuh raya kurangkan beban pemandu, CarPlay, HiCar, sambungan telefon langsung utama disokong semua, sesuai dengan lebih banyak tabiat pengguna.

sokong pelancaran, Chery keluar dasar pembelian ikhlas, sebelum 30 September pesanan, boleh nikmati pakek faedah 8 kali, warna kenderaan terhad percuma terhad masa, berbagai skim kewangan, tanpa kira jenama dapat menerima subsidi pertukaran. khususnya menarik perhatian 2 faedah perlindungan, bateri kuasa jika berlaku terma meletup kerana diri sendiri rosak, boleh ganti sama model atau kereta baru setara, parkir, mod panduan pintar jika disabit sistem bantu pemanduan pintar punca kemalangan, pampasan kerugian pihak ketiga sehingga 5 juta. serentak pemilik pertama boleh dapat jaminan seumur hidup kenderaan penuh termasuk 3 kuasa utama, hanya 666 Yuan boleh beli pakej penjagaan asas seumur hidup nilai 3999 Yuan, data asas percuma seumur hidup, data hiburan 3 tahun percuma, tempoh pra-jualan 1000 deposit tolak 2000 kereta, hadiah bengkong tamat 31 Ogos 24:00.

pada pasaran SUV elektrik kelas 100,000, ramai model akan buat pertimbangan pada keselamatan, jarak, pintar, Fulwin T7 dengan asas kereta global asli, menggunakan enam lebihan merosakkan peraturan industri bawah tanah, bawa jarak panjang, keselamatan tinggi, perkakasan pintar spesifikasi tinggi terus berikan kepada pengguna versi pemula, buat harga kelas 100,000, nilai produk kelas 200,000. ia tidak mengejar hiasan, tetapi kembali kepada permintaan paling sederhana pengangkutan keluarga, bawa kebolehpercayaan, keamanan, keselesaan jatuh ke setiap tempat. apabila banyak kereta baharu masih bersaing pada parameter kertas, Fulwin T7 sudah lalu jalan ujian jalan sebenar satu juta kilometer global, menggunakan kerja lambat membina sebuah SUV elektrik untuk keluarga global.
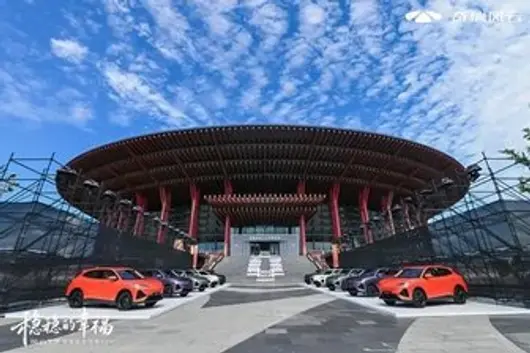
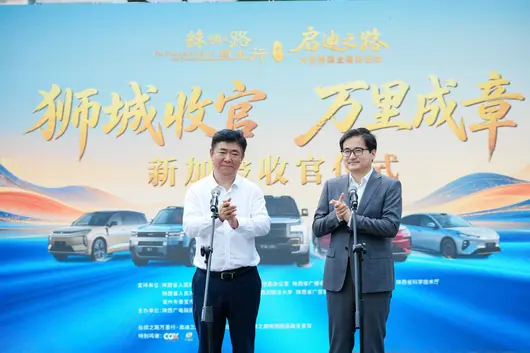
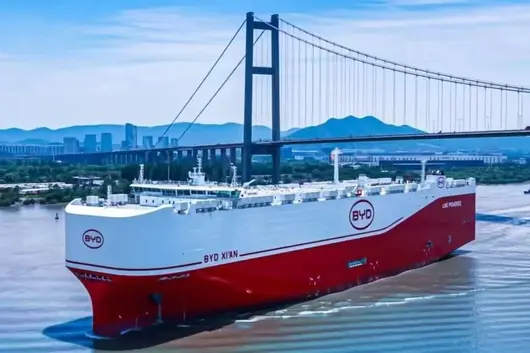
8 月 25 日,比亞迪全程護航嘅「2026 絲綢之路萬裏行·啟迪之路」喺新加坡正式收官。
33 日,上萬公里,從西安一路開到獅城。香藥、瓷器、絲綢、茶葉四大絲綢之路信物,亦頭一回喺海外集齊亮相。
點解揀新加坡收官?因為比亞迪喺嗰度已经连续 19 個月拿下乘用車全品牌銷冠,市場佔有率 24.7%,純電份額超 40%。全世界擁有車輛成本最高嘅市場之一,唔靠平價,靠產品硬撐。
而呢場萬裏遠征本身就係一次硬核實測。王朝、海洋、騰勢、方程豹、仰望五網四品牌組成嘅車隊經歷高速、山區、城市擁堵多重考驗閃充「5 分鐘充好、9 分鐘充飽」,天神之眼智駕全程喺線。 絲路遠行綠能相伴,千年前駝隊馱住絲綢瓷器行完呢條路,今天車輪載住新能源技術同中國智造重新行咗一遍。

從物產流通到技術共建,呢個大概就係「一帶一路」最生動嘅註腳。
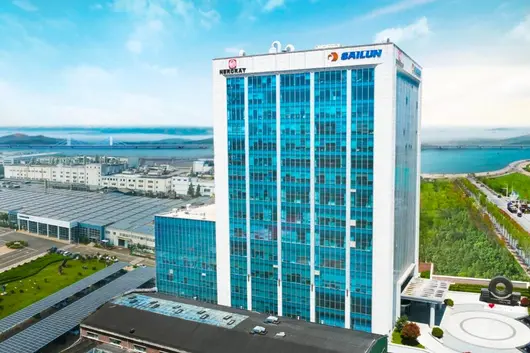
Pada petang 30 Ogos, Kumpulan Sailun mendedahkan Laporan Semester 2026, menyajikan laporan kewangan yang cemerlang di mana kuantiti dan keuntungan meningkat bersama: Pendapatan pada enam bulan pertama mencapai 20.027 bilion yuan, peningkatan setahunan sebanyak 13.88%; Keuntungan bersih yang boleh diperuntukkan kepada pemilik ekuiti syarikat 2.16 bilion yuan, peningkatan setahunan 17.97%——purata keuntungan harian melebihi 10 juta. Pada 30 Jun, jumlah aset syarikat 51.359 bilion yuan, bersih yang boleh diperuntukkan kepada pemilik ekuiti syarikat 22.662 bilion yuan.
Trend pertumbuhan Suku Kedua semakin dipercepatkan: Pendapatan tunggal suku 105.66 bilion yuan, peningkatan setahunan 15.16%, peningkatan berbanding suku sebelumnya 11.68%; Keuntungan bersih 11.03 bilion yuan, peningkatan ketara setahunan 39.26%. Kumpulan secara serentak memperkenalkan rancangan dividen semester, cadangan membayarkan tunai 0.15 yuan setiap saham (termasuk cukai), dijangka membayarkan 493 juta yuan, telah melaksanakan dividen pertengahan tahun selama tiga tahun berturut-turut.

Keluaran dan Penjualan Pecah Rekod, Keupayaan Global Dilepaskan Secara Dipercepat
Bersama dengan pelepasan keupayaan global secara beransur-ansur, keluaran dan penjualan Sailun pada setengah tahun pertama masing-masing memecahkan paras tempoh sejarah: Jumlah pengeluaran tayar 46.9749 juta helai, peningkatan setahunan 15.70%; Penjualan 45.0135 juta helai, peningkatan setahunan 14.99%, pasaran dalam dan luar negara meningkat secara serentak.
Sekarang, kilang Vietnam, Kemboja telah memasuki fasa penghasilan stabil tinggi, kilang Indonesia, Mexico keupayaan sentiasa meningkat, pembinaan tapak Mesir dipromosikan secara berperingkat. Rancangan tapak luar negara bersama-sama mempunyai keupayaan tahunan 12.75 juta helai tayar subang keluli penuh, 89 juta helai tayar subang keluli separuh dan 130,000 tan tayar bukan jalan raya. Tahun 2025 dan setengah tahun pertama 2026, jumlah penghantaran tayar subang eksport Kumpulan, keluaran dan penjualan kilang luar negara masing-masing menduduki tempat pertama industri tayar China. Dalam keadaan penghalang perdagangan kerap berlaku, pelaksanaan globalisasi berpandangan ke hadapan kini menjadi parit pertahanan utama Sailun untuk melalui kitaran.

Implementasi Iterasi Penyelidikan dan Pembangunan, Digitalisasi Memimpin Industri
Kumpulan menempatkan 4 pusat penyelidikan dan pembangunan di seluruh dunia, Pada Ogos usaha gabungan "Penyelidikan dan Penggunaan Peralatan Pembuatan Pintar Tanpa Manusia untuk Tayar Kelas Atas" menerima Anugerah Kemajuan Sains dan Teknologi Shandong Darjah Pertama. Di bahagian produk, tayar subang keluli penuh mengeluarkan produk baru khas tenaga baharu, beban berat, keadaan loji perlombongan; tayar subang keluli separuh produk UHP kelas tinggi US61 dimulakan pengeluaran, beberapa model tayar musim sejuk lulus pensijilan TÜV Eropah; pendapatan tayar bukan jalan raya menduduki tempat pertama dalam senarai syarikat tayar kejuruteraan dalam negara tahun 2026.
Dari aspek digitalisasi, Kumpulan melaksanakan sistem pemeriksaan kualiti penglihatan AI, logistik automatik AGV, perancangan pengeluaran pintar APS, dan membina model raksasa industri Rantai Getah Awan, Agen Lobster Sailun, Agen Perlumbaan Kuda Sailun dan matriks AI pembangunan sendiri, dinilai sebagai syarikat peringkat 5 kematangan transformasi digital pertama dalam industri, dipilih ke dalam senarai syarikat pemimpin digital Kementerian Perindustrian dan Informasi.

Peningkatan Nilai Jenama, ESG Menegakkan Piawaian Industri
Tahun 2026, Sailun dalam senarai Jenama Tayar Paling Berharga di Dunia Brand Finance menduduki tempat ke-10 di dunia, jenama tayar China dengan ranking tertinggi; dengan nilai jenama 125.189 bilion yuan pertama kali masuk 100 besar "500 Jenama Paling Berharga China", muncul dalam senarai 500 Kuasa China "Fortune" selama dua tahun berturut-turut.
Dari aspek ESG, Kumpulan adalah syarikat tayar pertama dalam negara yang lulus pengesahan Sasaran Karbon Saintifik SBTi, penilaian MSCI ESG mencapai tahap AA, tahap tertinggi industri tayar China. Tayar Emas Cecair keberkesanan pengurangan karbon menonjol, Trak dan Bas, Tayar Kereta Penumpang setiap seribu kilometer pelepasan karbon sepanjang kitaran hayat berbanding tayar biasa masing-masing menurun 39%, 27%.
Dalam kesulitan umum industri tayar global "pendapatan meningkat tetapi keuntungan tidak", laporan setengah tahun ini "pendapatan dan keuntungan meningkat" Sailun amat bernilai. Masa depan, Kumpulan akan berterusan dengan "membuat satu tayar yang baik" sebagai misi, melalui pelaksanaan globalisasi dan penyelidikan teknologi mengukuhkan daya saing teras, menyerahkan jawapan yang lebih baik kepada pengguna global.
封面|比亚迪
作者|陈濯
编辑|韩永昌
8月29日,比亚迪披露了一份并不好看的半年报。
上半年,比亚迪实现营业收入3448.15亿元,同比下降7.13%;归母净利润123.25亿元,同比下降20.54%。主要财务指标基本都处于同比下滑状态,账上现金及现金等价物更是只剩556.19亿元,较去年同期减少了约一半。
这样的成绩,其实并不算意外。在一个每天上市3.3款新车的市场里,几乎没有哪家车企能够交出一份足够漂亮的半年报。
今年上半年,理想由盈转亏,净亏损39.81亿元;小鹏净亏损31.2亿元。即便是上半年风头正盛、单月销量突破10万辆的零跑,实现了净利润同比增长530.97%,但也只有2.08亿元。
因此,在这样的市场环境下,单纯分析比亚迪上半年营收、利润等财务指标的涨跌,意义并不算大。这既有公司自身经营层面的原因,更有整个市场环境变化带来的影响。
所以,这篇短文不打算把重点放在财报的数字涨跌上,而是想聊两个数据:
第一个数据是比亚迪海外营收占比首次超过一半,达到52.57%;第二个数据是其上半年研发投入出现了2020年以来首次同比下滑。
01
—
海外营收占比52.57%
先看海外营收。比亚迪真正大规模出海,是从2024年之后开始的。
2024年四季度,比亚迪连续三个月月销量超过50万辆,国内月销量超过45万辆,这是迄今为止的月销量顶峰。2024年,比亚迪也成功卖出去了420万辆新能源车,国内市场的增长触碰到了天花板。
此时开始,比亚迪明显加快了海外市场扩张。
2025年,比亚迪全年海外销量首次突破100万辆,海外营收占总营收的比例也从2024年的28.55%提升至38.65%。
到了今年,这个趋势进一步加速。
2026年前六个月,比亚迪总销量为180.85万辆,其中海外销量达到79.23万辆,国内销量101.63万辆。也就是说,海外销量已经占到比亚迪总销量的43.8%。

更值得注意的是,海外销量的增长,已经开始直接反映在收入端。今年上半年,比亚迪境外收入达到1812.68亿元,占总营收的52.57%。
这是比亚迪历史上第一次海外营收占比超过一半。

比亚迪已经不只是在出海,而是在变成一家越来越依赖海外市场的车企。而海外市场对于比亚迪的意义,还不只是提供增量销量。
财报显示,今年上半年比亚迪境外业务毛利率达到21.71%,而国内业务毛利率仅为15.67%。
结合比亚迪上半年国内、海外销量,可以粗略计算出,海外业务对应的单车毛利约为4.97万元,国内则约为2.52万元,前者接近后者的两倍。
当然,这个数字不能简单理解为“比亚迪在海外每卖一辆车就赚4.97万元”。比亚迪的业务结构与很多车企不同,动力电池、储能等业务的利润也包含在整体业务中,国内外产品结构也存在差异。
但至少有一点非常明确:海外市场对于比亚迪或是任何中国车企来说,不只是新的销量增速来源,也是利润更好的市场。
所以,比亚迪还在继续加速出海。
财报显示,目前比亚迪新能源汽车业务已经覆盖全球六大洲、121个国家和地区。今年上半年,在英国、意大利、西班牙、巴西、泰国、印尼、沙特、阿联酋等主要出海市场,比亚迪都是新能源销量冠军。
如果未来比亚迪能够保持海外销量增长,同时让海外收入长期维持在总营收的一半以上,那么它的身份也会发生一个很明显的变化,它不再只是中国最大的新能源汽车公司,而会越来越像一家全球汽车公司。
02
—
研发投入同比下降6.54%
研发,一直是比亚迪最重要的标签之一。
过去几年,比亚迪几乎每年都会强调研发投入。从技术鱼池,到工程师文化,再到不断增加的研发人员和研发费用,研发投入一直是比亚迪区别于其他车企的重要标签。
但今年,这个指标发生了一些变化。
2026年上半年,比亚迪研发投入288.61亿元,同比下降6.54%。这是比亚迪自2020年以来,首次出现半年度研发投入同比下降。

而且,不只是研发投入总额下降,研发费用的结构也发生了变化。
今年上半年,比亚迪资本化研发费用达到55.54亿元,占研发投入的19.24%;而去年同期,这一比例仅为4.16%。
这里需要简单解释一下什么叫研发资本化。
A股上市公司研发投入,可以选择费用化,也可以在满足条件后进行资本化。费用化意味着研发支出直接计入当期损益;资本化则意味着符合条件的研发支出先计入资产,之后再通过折旧、摊销等方式逐步计入成本。
通俗点说,研发费用的资本化比重越高,当期扣除的金额就越少,这些金额可以放到利润栏目中,使账面利润更高。
按照今年上半年的数据,比亚迪资本化研发费用为55.54亿元。
如果假设资本化比例仍然维持去年同期4.16%的水平,那么今年上半年资本化的研发费用大约只有12亿元。简单测算,在其他条件不变的情况下,比亚迪当期利润可能会受到约43亿元的影响,只剩下不到80亿元。
但这里也需要强调,研发资本化本身并不意味着财务造假或者利润操纵。只要研发项目符合会计准则规定的资本化条件,企业进行资本化处理就是正常的会计行为,有些车企研发费用的资本化比例甚至会达到80%。
真正值得关注的,其实是两个数字同时发生了变化:研发投入下降了,资本化比例也提高了。这和过去几年的比亚迪,形成了明显反差。
过去几年,处于高速增长期的比亚迪一直标榜研发投入,连续两年位居A股上市公司第一,公司目前拥有超过12万名研发人员,截至2026年上半年累计研发投入已经超过2700亿元。
今年上半年研发投入下降,本身并不是一件需要苛责的事情,但却是一个很值得关注的信号。
尤其是在比亚迪国内市场承压、利润下滑的背景下,这意味着这家过去持续加码研发的公司,开始更加关注投入和产出之间的关系。
03
—
写在最后
过去几年,比亚迪最擅长的事情,是不断做大。2021年至2025年,比亚迪销量从73万辆做到460万辆,增长约6.3倍。
对于一家供应链高度垂直整合的公司来说,这不只是整车产能要扩大6.3倍,电池、电机等大量自供零部件的产能,也要同步扩张。那是一个典型的高速增长阶段,比亚迪员工人数最高一度达到97万人。
但当国内新能源市场从增量竞争进入存量竞争,比亚迪也开始进入调整期。
国内市场单纯依靠降价和堆料换增长的时代正在过去,而海外市场给了比亚迪新的增长空间。今年上半年的销量、营收和利润率甚至证明,出海已经不只是第二增长曲线,甚至可能成为未来比亚迪最重要的增长来源。
与此同时,研发投入首次下降,也意味着比亚迪开始重新面对投入、产出与利润之间的关系。这并不意味着比亚迪不再重视研发,而是高速增长之后的一次调整。
所以,与其说这是一份不好看的半年报,不如说它更像是一份处于转折期的半年报。而这个转折能否顺利完成,也将决定比亚迪能否真正成为一家全球性车企。
- END-
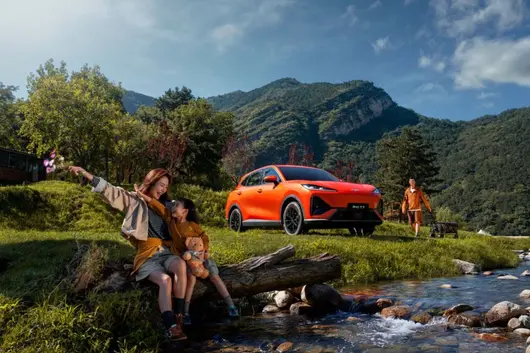
家庭纯电 SUV 市场再添新选手。8 月 26 日,奇瑞风云 T7 正式迎来上市,这款主打全球品质的纯电 SUV,以 “稳稳的幸福” 为产品内核,面向追求务实、安心出行的普通家庭推出三款配置版本。新车上市指导价 9.79 万‑11.89 万元,抢先置换价 9.49 万‑11.59 万元。

发布会现场,音乐人吴克群以 “幸福体验官” 身份出席,与奇瑞汽车执行副总裁李学用围绕 “稳稳的幸福” 展开交流,结合家庭出行场景分享用车感悟,双方共同开启「幸福共创计划」,邀请用户记录生活里的幸福点滴。

面对行业快速迭代的市场环境,风云 T7 秉持 “慢功造好车” 的长期主义理念,属于原生全球车型,并非国内车型简单改款出海。车辆研发对标 2026 版 E‑NCAP 安全标准,依托全球 1+7+N 研发体系,完成 145 万公里耐久验证,经历高温、高寒、高湿等多类极限环境测试,适配全球多样路况与气候条件,同源车型 Lepas L6 已陆续在南非、泰国等市场投放,后续还将登陆欧盟、澳新等地区。

产品层面,风云 T7 围绕超能跑、美全球、更安全、好智慧四大核心价值打造,同时具备六大冗余产品实力。全系标配 65.05kWh 犀牛电池,CLTC 续航 600km,30%-80% 快充仅 20 分钟,做到续航平权,避免入门版本续航缩水的行业常见问题。车身高强度钢占比达到 80%,配备 9 安全气囊,电池拥有多层防护结构,在碰撞、电池安全方面留有充足冗余。智能方面搭载 8775 舱驾一体芯片,结合灵犀智舱 2.0 与豆包大模型,支持 300 + 全场景自动泊车、高速领航辅助等功能,兼顾家用出行的舒适与便捷。

在十万级纯电赛道,不少消费者既在意价格,也看重车辆的安全、续航与长期可靠性。基于奇瑞多年海外市场积累,风云 T7 将全球研发验证成果落地国内市场,希望用均衡的产品表现与实在的购车政策,为广大家庭用户提供一个务实的纯电出行选择,守护日常通勤、周末出游途中的每一份踏实与安心。
2026年8月26日,奇瑞风云T7正式上市,官方指导价9.79‑11.89万元,抢先置换价9.49万元起,上市即交付。在国内新能源市场“快迭代、重堆料、入门减配”的内卷浪潮之下,风云T7走出一条与众不 同的路线:原生全球车,先出海验证,再回归国内市场,用三年研发周期、全球严苛验证,主打家用家庭用户的真实用车诉求,试图重塑十万级纯电SUV的价值标尺。
反向出海:一台为全世界造的家用纯电SUV
当下绝大多数中国新能源车型的逻辑是:国内完成研发上市,市场验证之后,再做局部修改适配海外法规,实现出口。风云T7则选择反向路径:同源车型Lepas L6已经率先登陆南非、泰国,后续将进入欧盟、英国、澳大利亚、以色列等市场,先经受全球市场检验,再面向国内消费者开售。

风云T7依托奇瑞全球1+7+N研发体系打造,研发周期长达三年,对标2026版E‑NCAP五星安全标准,适配全球210个国家和地区用车环境。研发阶段投入81台耐久试验车,累计完成145万公里耐久验证、600万公里全球路试,足迹遍布21个国家,覆盖全球绝大多数典型路况;同时邀请5000多名海内外用户参与共创,兼顾不同地区的审美与用车习惯。

奇瑞提出的“全球车,快不了一点”,正是风云T7的产品底色。它不追求快速上新,而是把安全、耐久、可靠性放在优先级首位,把海外严苛标准直接平移到国内版本,这也是它区别于同价位很多车型的核心差异点。
产品力解析:续航平权,把核心硬件给到每一位用户
风云T7定位紧凑型纯电SUV,车身尺寸4570×1852×1694mm,轴距2700mm,五座布局,车身尺寸兼顾城市好开好停,同时满足三口之家日常出行空间需求。
三电系统:全系600km,拒绝入门版续航缩水
十万级纯电市场一个普遍现象:入门版本缩减电池、降低续航,用低价吸引用户,长续航版本需要大幅加价。风云T7直接实现续航平权:三款配置全部搭载65.05kWh犀牛磷酸铁锂电池,CLTC续航统一600km,百公里电耗12.9度,30%‑80%直流快充仅需20分钟,支持6.6kW对外放电,满足露营户外场景。

动力采用12合1鲲鹏超能电驱,前置单电机最大功率178kW,峰值扭矩275N·m,最高车速180km/h,兼顾城市通勤与高速超车能力。底盘为前麦弗逊+后多连杆独立悬架,由海外底盘专家团队调校,560mm低重心设计,带来不错的行驶稳定性;整车拥有500mm涉水深度,电池包具备完善的液冷、PTC预加热、宽温域热泵空调,兼顾低温环境续航表现。
外观与座舱:家用取向,实用配置不吝啬
风云T7采用东方驭风美学家族设计,封闭式前脸搭配L型日行灯,整车线条简洁稳重,兼顾全球市场审美。全系标配AGS智能主动进气格栅,全车14项低风阻优化,有效降低风噪、提升续航表现;车尾贯穿式尾灯,全系标配电动尾门,在同价位属于非常实在的配置。

市场格局:十万级纯电SUV,务实路线的新挑战者
当前10‑12万纯电SUV赛道竞争白热化,埃安、零跑、名爵等多款产品同台竞技。这个细分市场的用户,大多是家庭第一台车,诉求非常现实:稳定续航、靠谱安全、够用的配置、低用车成本,对花哨的噱头配置并不感冒。

风云T7和风云T9L定位形成区隔:T7是城市家用纯电SUV,适合日常通勤为主,充电条件方便的家庭;T9L是插混大五座,适合经常长途出行、没有固定充电条件的用户,两者互补,完善风云品牌的家用新能源矩阵。

风云T7的上市,代表奇瑞风云品牌的一种产品思路:不盲目堆砌参数,不做入门减配,把全球标准落地到家用车型,用质保和安全兜底,服务普通家庭真实用车场景。
在很多车型一味追求加速、大屏、花哨功能的时候,风云T7回归家用本质:续航够用、安全靠谱、底盘扎实、售后省心。“先出海再回家”的开发模式,也给国内新能源行业提供一种参考:好车不止服务国内市场,更要经得起全球市场的检验。
对于普通消费者而言,如果预算落在9‑12万,想要一台600km续航、有终身质保、兼顾城市通勤与短途出游的纯电SUV,风云T7是值得重点考量的务实选择。
8% is like a door; most people cannot push it open, but among every 100 people, there are always 8 who can push it open.
How big is the 8% probability?
If the probability of rain tomorrow is 8%, I believe most people would not bring an umbrella. But if the probability of winning a prize is 8%, I believe many would participate. After all, compared to the probability of less than 1% for Pop Mart blind box hidden figures, 8% is still worth participating in.
The current domestic automotive market is also like this. Countless car manufacturers seek to break through in the market, only to compete for this 8% success probability.

According to incomplete statistics, there are currently about 700 models of new energy vehicles on sale in the domestic market, but only 56 products have a monthly sales volume of over 5,000 units, and the overall product success rate of the industry is only 8%.
Creating a hot-selling product is already the top priority for car manufacturers. After creating a hit, how to continuously maintain high sales has become the focus. Bloom for a night is the fate of most new cars. Once the three-month flowering period is over, they become nothing special.
Faced with the pressure of market competition, the transformation difficulty for traditional car manufacturers is harder than for the well-funded new forces. In the sales month approaching "Golden September and Silver October", the mid-year financial reports of car manufacturers have also been released. The answer to transformation is written in the reports.
Exports and Going Upmarket
First is BYD's semi-annual report. Cumulative sales of new energy vehicles in the first half of the year were about 1.8085 million units, down 15.72% year-on-year. Revenue from the automotive business was about 275.341 billion yuan, down 8.98% year-on-year.
At first glance, many people only see the decline in revenue and net profit attributable to the parent company, and then directly label this top dog of the new energy industry as "declining".
But if you carefully analyze BYD's financial report, you can understand the changes of this industry leader.
In the semi-annual report, BYD showed unprecedented supply chain strength, with a gross margin of 18.85%, and the gross margin in the second quarter even rose to 18.88%, up 2.61% year-on-year.
It is worth knowing that in the first half of 2026, the domestic automotive industry faced triple pressure of raw material price hikes, exchange rate fluctuations, and price wars. The average profit margin in the vehicle manufacturing link dropped to 1.5%, setting a new low in nearly ten years. However, BYD presented an upward mid-term answer.

Behind this lies BYD's transformation. According to sales data, Fang Cheng Bao, Denza, and Yangwang brands combined sales of 228,000 units, up 61% year-on-year. Their share of total sales rose to 12.6%. Moreover, the domestic full brand ASP (Average Selling Price per vehicle) rose from 133,100 yuan in March to 148,700 yuan in June.
In the domestic market, wanting to raise the price per vehicle basically means providing users with more configurations. BYD relies on technology to make consumers pay for this value add.
Only in the first half of the year, BYD showcased multiple new technologies. From the 2nd gen Blade Battery and Megawatt Supercharge at the beginning of the year to the self-developed 4nm smart driving chip Xuanji A3 and the Sky-Eye 5.0 ADAS system support, BYD demonstrated the R&D confidence and technical support capability a big factory should have.
Especially the 2nd gen Blade Battery and Megawatt Supercharge allowed BYD to achieve an upward price adjustment per vehicle. At the previous financial report meeting, Chairman Wang Chuanfu stated that currently the 2nd gen Blade Battery is in short supply, and this year's sales are fully limited by battery capacity.

On the other hand, the construction of BYD's Supercharge stations is extremely rapid. On August 28, they completed the construction of the 10,000th Supercharge station. Although compared to the 20,000 stations target set at the beginning of the year, it looks slightly slow in time, BYD guarantees to definitely complete the target this year.
From batteries to energy storage, BYD relied on lithium battery technology to achieve breakthroughs in new energy vehicles. Relying on self-developed and self-produced batteries, BYD achieved a gross margin rise despite the negative impact of upstream raw material price hikes. Furthermore, BYD's self-production covers not only batteries but a series of components like chips that are also rising in price. The core component self-supply rate exceeds 80%, which is difficult for general car manufacturers to learn quickly.
Behind these technologies, there are no other shortcuts. They are all investments BYD made with real money. Financial reports show that BYD invested 28.9 billion yuan in R&D in the first half of the year, and cumulative R&D investment exceeded 270 billion yuan. They earn 1 yuan and spend more than 2 yuan on R&D.

Of course, this is not a muddled account. Behind this is BYD's long-term investment, and now these investments have achieved returns.
Besides being firmly the champion of domestic new energy retail sales with 21.1% market share, BYD also took the first position in new energy exports with an export scale of 792,000 units.
Export growth is the main contributor to BYD's sales this year. Export sales share exceeds 40%, with a growth rate exceeding 60%. Meanwhile, revenue share exceeded half, reaching 52.7%. It can be said that more than half of the money BYD earns comes from overseas markets.
According to data, BYD's overseas vehicle profit is three times that of domestic, meaning 2 yuan of R&D earns back 3 yuan overseas.

As for BYD's overseas scale, the growth speed is as fast as the Supercharge stations. The business covers over 120 countries and regions. It topped the new energy brand sales champion in markets like the UK, Brazil, and Thailand. Inside BYD, there is even a plan to build stores in the Atlantic island nation Cape Verde this year which became popular due to the World Cup.
However, the overseas market also carries risks. In the semi-annual report, BYD attributed the main reason for profit decline to exchange losses generated by exchange rate fluctuations, losing about 4.7 billion yuan in profits. Such risks are an adjustment for global car manufacturers. Some lose on exchange rates, some profit. Japanese brands in recent years have achieved profit rises relying on exchange rates.
As a representative of domestic new energy vehicles, BYD proved with time and actions that domestic new energy can still profit in the market without price wars, whether domestic or overseas.
Pressure and Growing Pains
Changan Automobile's semi-annual report is more about changes. In the first half of 2026, the company achieved operating revenue of 65.634 billion yuan, down 9.71% year-on-year; net profit attributable to the parent company was 0.817 billion yuan, down 64.32% year-on-year, with a gross margin of 14.50%.
Different from BYD, Changan Automobile's financial report better represents the status quo of domestic car manufacturers' transformation. In the process of shifting from fuel cars to new energy, Changan Automobile faces far more difficulties than BYD. BYD can build its own new energy supply chain from scratch, but Changan Automobile needs to consider the transformation of the supply chain from the fuel car era with hundreds of upstream suppliers.
If excluding the fuel car sector, Changan Automobile's performance in new energy is still quite good. In the first half of 2026, new energy vehicle sales reached 414,000 units, down 8.3% year-on-year. However, after excluding entry-level models like Lumin, the total new energy sales in the first half of 2026 grew 11% year-on-year. Among which, new energy vehicle sales in the second quarter were 245,600 units, up 45.64% quarter-on-quarter.

Changan Qiyuan Q05 ranked number 1 in compact pure electric SUV sales for consecutive 3 months. Deepal S05 ranked champion in the niche field (120,000-180,000 pure electric compact SUV) for consecutive 4 months. Behind this is Changan's breakthrough in niche models. Rather than grandly covering all models, it is better to focus efforts at a point and find your own track.
Changan Qiyuan is exactly like this. Not exchanging price for volume, Qiyuan average price per vehicle rose 12,000 yuan year-on-year. Cumulative sales in the first 7 months of this year exceeded 210,000 units, and July single month sales also exceeded 30,000 units. And it achieved single quarter profit in Q2, taking the first step of new energy startup.
Besides the domestic market, overseas business is also Changan's main profit source. Deliveries in overseas markets in the first half were 402,000 units, up 35.1% year-on-year. Overseas business revenue was 21.942 billion yuan, up 78.77% year-on-year. Overseas gross margin remained above 20%.
Behind this is Changan Automobile adopting the "Local production + Systematic operation" strategy in overseas markets. Its Thailand Rayong factory has started production and operation, achieving localization production of hot-selling models like Deepal S05 and Changan Qiyuan Q05.

While playing well the new energy card, Changan also used "Blue Whale Super Hybrid" to provide a new solution for the fuel car market, especially to cope with lithium battery raw material price hikes and charging facility construction weak areas' vehicle usage demand.
But these advantages still cannot cover the difficulties Changan Automobile faces in transformation. Significant profit decline and negative operating cash flow all indicate that transformation costs are high and have not yet been converted into profit.
Now Changan Automobile's hopes are all bet on overseas business. 51.9% export growth and 78.8% overseas revenue growth became the only highlight in business difficulties.
Rely on Yourself
Different from BYD and Changan, GAC Group represents the transformation of more automotive SOEs. In 2025 sales, GAC was the SOE with the highest proportion of joint venture sales. 64.4% of sales were contributed by GAC Toyota and GAC Honda, with a reliance on joint ventures far higher than other SOEs.
But after fuel car sales continued to decline and the independent brand sales share broke 70%, GAC Group's situation became very subtle.
Financial reports show that GAC Group revenue grew 9.38% year-on-year to 46.121 billion yuan, but the gross margin was -2.51%, negative for two consecutive years. Among them, investment income from joint venture enterprises decreased by about 6 billion yuan year-on-year, becoming the biggest drag on performance.
From the sales data perspective, GAC's performance is not as poor as the financial report suggests. New energy vehicle sales were 260,200 units, up 68.80% year-on-year, with a growth rate significantly higher than the industry. Among which, the independent brand new energy sales share reached 62.82%, up about 14 percentage points year-on-year.

GAC Toyota sales grew 3.29%. The Zhizhi series monthly sales continuously broke 10,000. Zhizhi 3X ranked joint venture new energy sales champion for consecutive 10 months.
However, GAC Honda sales plummeted 55.82% to 68,300 units. New energy vehicle sales were only 3,276 units, becoming the biggest drag on GAC Group performance.
When joint venture brands lost combat power, GAC needs to fill the gap with independent brands. The cost of catching up is not small. Money is needed in all aspects. Expenses like R&D and marketing need to increase. R&D expense up 39%, financial expense up 243%, sales expense up 17%. Overall, this led to a situation of revenue growth but profit loss increase.
Especially the R&D investment. The 4.8 billion investment in the second quarter kept the gross margin still maintained at negative 1.28%. As for channel construction, GAC chose to sink and focus on the county economy, planning to complete 1,000 county authorized stores this year.

At the same time to achieve efficient transformation, GAC Group introduced IPD process reform. Officially stated independent brand R&D, production, supply, sales, finance integrated control, making product planning efficiency up 30%, project approval efficiency up 67%, demand decision efficiency up 85%. New car development cycle shortened to 18-21 months, and R&D cost reduced by over 10%.
But these are hard to show in financial reports in the short term. Currently the only thing visible is still export growth.
Semi-annual report shows, GAC independent brand exported 121,500 units in the first half of the year, a surge of 132% year-on-year, close to the 2025 full year export volume. Overseas business revenue was 14.013 billion yuan, up 109.27% year-on-year.

In the global layout, 7 KD factories were built, adding two factories in Cambodia and Kazakhstan. At the same time, the first overseas independent battery PACK factory is being built in Thailand, perfecting overseas power battery localization supply, achieving supply chain synchronous overseas go.
Like BYD, GAC's layout in new energy also first focuses on the power battery which has the largest cost share. Ensuring supply chain autonomy and control, no longer working for battery manufacturers, makes it possible to achieve a positive gross margin.
As a representative of transitioning from relying on joint ventures to relying on independents, GAC Group is still in the transformation difficulty period. Transformation investment surged, leading to expanded losses, and it will still be difficult to achieve change in the short term.

Overall, under the background of the domestic market first half year-on-year decline over 20%, it can better see the urgency of traditional car manufacturers' transformation. On one hand, the battlefield has already spread from domestic to overseas. Overseas markets have become the core of car manufacturers' profit, but at the same time exchange rate fluctuations have also brought uncertainty.
On the other hand, R&D investment is becoming the core to measure car manufacturers' long-term profit. BYD relies on years accumulated R&D investment, now has already formed technical advantages and converted them into profitability. Like Changan and GAC need to catch up in R&D, investing greater costs to achieve self-research.
Overall, under the first half domestic car market "cool inside hot outside" pattern, whoever can more quickly shift growth focus to overseas and premiumization can walk out of the profit valley earlier. BYD has already verified the effectiveness of this path first. Changan and GAC are still in the transformation climbing phase.
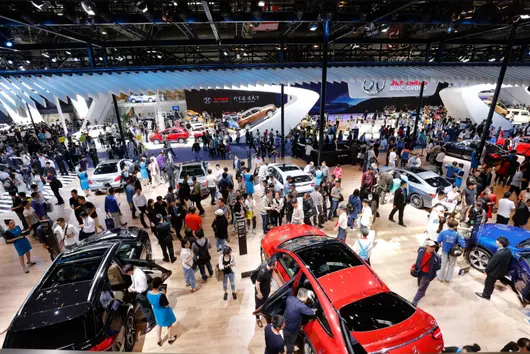
In the Malaysian SUV market, many buyers compare the Honda HR-V and Toyota Yaris Cross when choosing a car.
The Honda HR-V OTR price in Malaysia is RM 115,900 - 143,900, with a total of 4 versions, including the 2026 e:HEV 1.5L RS (RM 143,900), 2026 1.5T V (RM 137,900), 2026 1.5T E (RM 130,900), etc.
The Toyota Yaris Cross OTR price in Malaysia is RM 99,900 - 109,900, with a total of 2 versions, including the 2026 1.5L Standard (RM 99,900), 2026 HEV 1.5L Standard (RM 109,900), etc.
Looking at the price, the Toyota Yaris Cross starting price is RM 16,000 cheaper than the Honda HR-V. Honestly, at this price range, the difference of a few thousand is not actually significant; the key is to look at the overall value for money and long-term usage costs.
The Honda HR-V safety rating is 5★ (ASEAN NCAP), active safety systems include Honda SENSING (ACC, CMBS, LKAS, RDM).
The Toyota Yaris Cross safety rating is 5★ (ASEAN NCAP), active safety systems include TSS.
The safety ratings for both cars are the same, and safety features are quite comprehensive within this class. New cars nowadays have decent safety, so there is no need to worry too much about this point.
Honda HR-V body length is 4500 mm, trunk 450 L.
Toyota Yaris Cross body length is 4400 mm, trunk 400 L.
In terms of space, the Honda HR-V body is 100 mm longer than the Toyota Yaris Cross, so the interior seating space is slightly more spacious, especially rear legroom. If you often carry family members or need to fit a stroller, a slightly larger body is indeed more practical.
The Honda HR-V adopts FWD drive system.
The Toyota Yaris Cross adopts FWD drive system.
The drive systems for both cars are the same, both are FWD, so there won't be much difference in daily driving feel.

In summary, both the Honda HR-V and Toyota Yaris Cross are very good models in the Malaysian market. Choosing which one depends mainly on your personal needs and budget. It is recommended to do your homework, compare quotes from several dealerships, and then test drive to make a final decision. Buying a car is a major matter, spending time on homework will never be wrong.
喺馬來西亞嘅 SUV 市場,好多買家喺揀車嘅時候都會拿本田 HR-V 同豐田 Fortuner 嚟比較。呢兩部車喺價錢同定位上都好好接近,今日我哋就由多個角度做一個詳細對比,幫你省返做功課嘅時間。
本田 HR-V 喺馬來西亞嘅 OTR 售價係 RM 115,900 - 143,900,合共有 4 個版本,包括 2026 e:HEV 1.5L RS(RM 143,900)、2026 1.5T V(RM 137,900)、2026 1.5T E(RM 130,900) 等。
豐田 Fortuner 喺馬來西亞嘅 OTR 售價係 RM 195,880 - 241,880,合共有 3 個版本,包括 2024 2.8T VRZ Diesel(RM 241,880)、2024 2.7L SRZ Petrol(RM 202,880)、2024 2.4L Standard Diesel(RM 195,880) 等。
由價錢睇,本田 HR-V 嘅起步價真係比豐田 Fortuner 平咗 RM 79,980。如果你預算有限,本田嘅入門版已經可以滿足日常需求。但都要注意,平嗰幾千蚊,喺配備上可能有取捨,具體就要睇你嘅需求。
本田 HR-V 車身長 4500 mm,後備箱 450 L。
豐田 Fortuner 車身長 4400 mm,後備箱 400 L。
空間方面,本田 HR-V 嘅車身比豐田 Fortuner 長咗 100 mm,車內乘坐空間會寬鬆啲,尤其係後排腿部空間。如果你經常載家人或者需要放嬰兒車,車身大少少真係更實用。
本田 HR-V 採納 FWD 驅動方式。
豐田 Fortuner 採納 FWD 驅動方式。
兩款車嘅驅動方式一樣,都係 FWD,日常駕駛感受唔會有太大分別。
本田 HR-V 同豐田 Fortuner 都係馬來西亞市場嘅主流選擇,適合家庭使用、日常通勤。如果你更睇重品牌口碑同二手價,可以優先考慮口碑更好嗰一款;如果你更在意性價比同配備,就揀配備更豐富嗰款。最尾都建議兩款都去試駕,親身體驗先至最重要。

總括嚟講,本田 HR-V 同豐田 Fortuner 都係馬來西亞市場好唔錯嘅車款。揀邊部,關鍵係要睇你嘅個人需求同預算。建議大家做好功課,多比較幾間車行嘅報價,再去試駕做最終決定。買車係件大事,花少少時間做功課絕對唔會錯。
In Malaysia's SUV market, many buyers compare the Honda WR-V and Subaru Forester when choosing a vehicle. These two models are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time doing research.
The Honda WR-V's OTR price in Malaysia is RM 89,900 - 107,900, with a total of 4 versions, including 2023 1.5L V (RM 99,900), 2023 1.5L E (RM 95,900), 2023 1.5L S (RM 89,900), etc.
The Subaru Forester's OTR price in Malaysia is RM 174,000 - 197,000, with a total of 3 versions, including 2024 2.0L S EyeSight GT Edition (RM 189,538), 2024 2.0L S EyeSight (RM 177,538), 2024 2.0L L EyeSight (RM 167,538), etc.
In terms of price, the Honda WR-V's starting price is indeed RM 84,100 cheaper than the Subaru Forester. If your budget is limited, Honda's entry-level version can already meet daily needs. However, keep in mind that saving that few thousand might involve trade-offs in features, depending on your specific requirements.

Honda WR-V's safety rating is 5★ (ASEAN NCAP), with active safety systems including Honda SENSING.
Subaru Forester's safety rating is 5★ (Euro NCAP), with active safety systems including EyeSight.
Regarding safety features, both cars received good ratings. However, there are some differences in functionality between Honda WR-V's Honda SENSING and Subaru Forester's EyeSight. If you prioritize active safety, you can compare their feature lists carefully.

The Honda WR-V uses a FWD drivetrain.
The Subaru Forester uses a FWD drivetrain.
Both cars use the same drivetrain, FWD, so there won't be much difference in the daily driving experience.

Honda WR-V warranty 5 years/unlimited mileage, service interval every 10,000km or 6 months.
Subaru Forester warranty 3 years/100,000km, service interval every 10,000km or 6 months.

Both the Honda WR-V and Subaru Forester are mainstream choices in the Malaysian market, suitable for family use and daily commuting. If you value brand reputation and resale value more, you can prioritize the one with a better reputation; if you care more about cost-performance and features, choose the one with richer configurations. Ultimately, it is recommended to test drive both; experiencing it firsthand is the most important.

Overall, both the Honda WR-V and Subaru Forester are very good models in the Malaysian market. Which one to choose ultimately depends on your personal needs and budget. It is recommended to do your research, compare quotes from multiple dealerships, and then test drive to make a final decision. Buying a car is a big matter; spending time doing research will definitely not be wrong.

In the Malaysian SUV market, many buyers compare the Honda WR-V and Subaru Forester when choosing a car. These two models are quite close in price and positioning. Today, we will make a detailed comparison from multiple aspects to help you save time on research.
The OTR price of the Honda WR-V in Malaysia is RM 89,900 - 107,900, with a total of 4 versions, including 2023 1.5L V (RM 99,900), 2023 1.5L E (RM 95,900), 2023 1.5L S (RM 89,900), etc.
The OTR price of the Subaru Forester in Malaysia is RM 174,000 - 197,000, with a total of 3 versions, including 2024 2.0L S EyeSight GT Edition (RM 189,538), 2024 2.0L S EyeSight (RM 177,538), 2024 2.0L L EyeSight (RM 167,538), etc.
From a price perspective, the Honda WR-V's starting price is indeed RM 84,100 cheaper than the Subaru Forester. If your budget is limited, Honda's entry-level version can already meet daily needs. However, keep in mind that the few thousand difference in price may involve compromises in features, specifically depending on your needs.
The safety rating of the Honda WR-V is 5★ (ASEAN NCAP), active safety systems include Honda SENSING.
The safety rating of the Subaru Forester is 5★ (Euro NCAP), active safety systems include EyeSight.
Regarding safety features, both cars have received good ratings. However, there are some differences in function between the Honda WR-V's Honda SENSING and the Subaru Forester's EyeSight. If you value active safety, you can compare the feature lists of both in detail.
The Honda WR-V body length is 4400 mm, trunk 400 L.
The Subaru Forester body length is 4400 mm, trunk 400 L.
The dimensions of both cars are almost the same, and the interior space difference is not significant. For cars of this class, it is more than enough for daily use.
Honda WR-V warranty 5 years/unlimited mileage, service interval every 10,000km or 6 months.
Subaru Forester warranty 3 years/100,000km, service interval every 10,000km or 6 months.
Overall, the Honda WR-V and Subaru Forester are both very good models in the Malaysian market. Which one to choose mainly depends on your personal needs and budget. We suggest doing your homework, comparing quotes from multiple dealerships, and then test driving to make a final decision. Buying a car is a big matter, spending some time on research will definitely not go wrong.
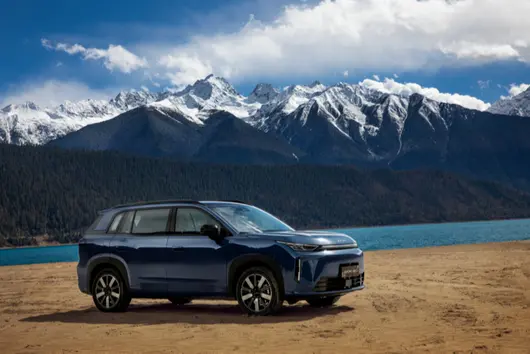
Berita Auto Elektrik, pada 26 Ogos, jenama Chery Fengyun menganjurkan pelancaran kenderaan baharu dengan tema "Kehidupan Tenang & Bahagia",SUV Elektrik Murni Berkualiti Global Fengyun T7 Dilancarkan Secara Rasmi. Kenderaan baharu telah dikeluarkan dalam tiga varian, iaitu Varian Nikmat 600km, Varian Selesa 600km, Varian Pintar 600km, harga panduan pelancaran97,900—118,900 Yuan, selepas menambah subsidi penukaran 3,000 Yuan/sebuah,Harga Penukaran Awal Serendah 94,900—115,900 Yuan, secara rasmi memasukkan SUV Elektrik Murni dengan jarak pemanduan CLTC 600km ke dalam bawah 100,000 Yuan.

Fengyun T7 diklasifikasikan sebagai SUV Elektrik Murni Kompak, saiz badan 4570×1852×1694mm, paksi 2700mm. Di bawah latar pasaran SUV Elektrik Kelas 100,000 Yuan yang umum 'Spesifikasi Rendah Jarak Pendek, Jarak Panjang Tambahan Harga', Fengyun T7 melakukan sebaliknya—Tiga varian kenderaan sama-sama dilengkapkan dengan bateri Litium Fosfat Chery Rhinoceros 65.05kWh, jarak CLTC semuanya 600km, cas pantas 30%—80% hanya mengambil masa 20 minit. Dari segi kuasa, kenderaan baharu menggunakan motor tunggal depan, kuasa maksimum 178kW, tork puncak 275N·m, kelajuan maksimum 180km/j.
Dari segi kecerdasan, varian tinggi dilengkapkan dengan cip integrasi kabin-pemanduan Qualcomm 8775 dan sistem pemanduan bantu Falcon 500, dilengkapi 22 pengesan keamatan tinggi, menyokong pemanduan bantu NOA laju dan parkir automatik 300+ senario. Dari segi keselamatan, bahagian keluli kuat 80% keseluruhan kenderaan, 9 beg udara keseluruhan, pek bateri mempunyai tahap perlindungan IP68. Yang patut diperhatikan,Semua konfigurasi utama di atas adalah sama pada ketiga-tiga varian kenderaan, perbezaan terutamanya terletak pada fungsi keselesaan dan kepraktisan.

Menurut laporan, Fengyun T7 adalah kenderaan global asli, melalui tiga tahun penyelidikan dan pembangunan, kumulatif berjaya memintas pengesahan kenderaan sebenar berjuta kilometer, model asing asal Lepas L6 telah memasuki pasaran Thailand, Afrika Selatan dan lain-lain. Di tempat pelancaran juga dikeluarkan pelbagai hak pembelian kenderaan, termasuk subsidi penukaran, faedah faedah kewangan, warna kenderaan unik percuma dan lain-lain faedah, seterusnya menurunkan ambang pembelian. Di trek SUV Elektrik Kelas 100,000 Yuan, Fengyun T7 dengan jarak panjang seragam, piawaian pembuatan kenderaan global, spesifikasi tinggi, membawa pembolehubah persaingan baru kepada pasaran rumah tangga elektrik murni, juga melengkapi matriks produk SUV elektrik murni siri Chery Fengyun.
Sah dari hari ini sehingga 30 September memesan, pengguna menikmati pakej lapan lapisan: Warna kenderaan unik Api Merah, Ungu Asap Gunung pilihan percuma terhad masa; Pakej kewangan 2 tahun 60,000 tanpa faedah atau 5 tahun 100,000 3 tahun bebas faedah; Subsidi penukaran 3,000 Yuan/buah tanpa mengira jenama; Pemilik pertama bukan komersial menikmati jaminan jangka panjang keseluruhan kenderaan (termasuk tiga sistem elektrik utama);Ganti rugi jika bateri kuasa berlaku lari panas model baru sama, insiden pemanduan pintar ganti rugi maksimum 5 Juta Yuandua hak perlindungan asas; dan pakej penyelenggaraan asas sepanjang hayat 666 Yuan dan lain-lain.

© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


