

HomeLeapmotor C10

Search History
Popular Searches
Dealer Login / Sign Up
Leapmotor's monthly sales broke 100,000 again. It's not that the data lacks impact, but "100,000" is now as routine for them as refueling at a gas station. Meanwhile, the European registration volume sees pure electric models in the top three in France, Germany, Italy, and Spain. This number is more worth discussing than domestic monthly sales.

100,000 monthly sales have become a cost threshold rather than a performance benchmark
July, August, and September consecutively reached 100,000. September hit 105,656 units, a 59% year-over-year increase, ranking top four among global new energy brands, still number one among new forces. Two years ago this was big news; now it's just the baseline.
The underlying logic is still that proprietary cost accounting. The LEAP5.0 architecture was just explained at the September Technology Day, integrating CTC3.0 batteries, LWM assisted driving, and MM-i hybrid electric drive onto the same chassis platform. After raising architecture commonality, the more electric drives, wiring harnesses, and domain controllers shared between SUVs and sedans, the thinner the R&D cost per unit becomes.
 Top three in European registration volume is worth ten times more than exporting 150,000 units
September alone exported over 27,000 units, with cumulative exports over 150,000 units from January to September, submitting the 2026 export goal early. France, Germany, Italy, and Spain, the four core European markets, all saw pure electric registration volumes enter the top three.
Export volume is the number on the ship; registration volume is the number on the street. The former can be achieved by pressing inventory, while the latter requires users to truly pay, outlets to truly deliver, and after-sales to truly support. Leapmotor leveraged Stellantis channels to deploy over 1,000 European outlets, and localized assembly in Malaysia and Spain has also started, bypassing the most capital-intensive phase of new forces building their own channels.
 Taking the D19 to Paris is not showing off muscles, but probing the water level
At the October Paris Motor Show, Leapmotor will enter with the D19 and A05. A05 is easy to understand, 510 km range plus LiDAR compressed under 100,000, sticking to the tech accessibility approach, going to Europe as a cost-performance sample. D19 is different, a 5.2-meter flagship SUV, offering both pure electric and extended range, responsible for raising the average price domestically, while Paris is responsible for establishing the brand persona.
Foreign media are more concerned about whether a Chinese brand that grew volumes through cost strategies can stand the two words "high-end" at the doorstep of established car manufacturers. To put it bluntly, this trip for D19 is not to pick up orders, but to probe the European acceptance level for Leapmotor brand premium.
 Don't rush to hype it into a global brand
Writing to this point, I need to pour a cup of cold water. Monthly sales stabilizing at 100,000, European registration entering the top three, having a flagship standing at Paris, Leapmotor is indeed in the forefront among new forces, but it's not time to relax yet.
The fourth quarter looks at three things: Can monthly deliveries reach 110,000 without falling back? Can European registrations expand from top three in four countries to Northern Europe and the UK? After LEAP5.0 lands, can vehicles like D19 truly pull up the average price per unit? After passing these three hurdles, Leapmotor will not be just the brand best at saving money, but a Chinese automaker qualified to talk system competition with global players.
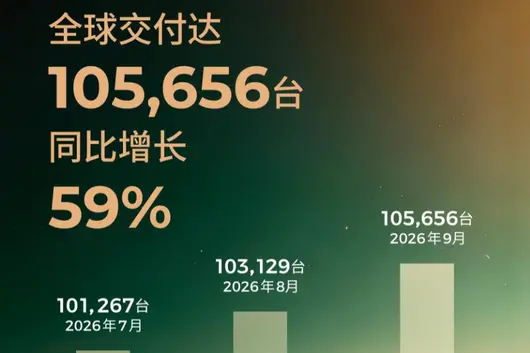
Jualan bulanan Leapmotor sekali lagi memecahkan 100,000 unit, bukan data yang tidak menarik, tetapi '100,000' sudah menjadi perkara harian baginya seperti mengisi bahan api di stesen minyak. Sementara itu, kuantiti pendaftaran Eropah, top 3 kenderaan elektrik sepenuhnya di Perancis, Jerman, Itali, Sepanyol, angka ini lebih bernilai untuk dibincangkan berbanding jualan bulanan dalam negeri.
Jualan bulanan 100,000, telah menjadi garis kos bukan lagi garis prestasi
Julai, Ogos, September berturut-turut berjaya capai 100,000, September 105,656 unit, naik 59% berbanding tahun sebelumnya, top 4 jenama teknologi global, pemain baharu masih nombor satu. Dua tahun lalu ini berita besar, sekarang hanya garis asas.
Asas masih menggunakan pengiraan penyelidikan sendiri itu. Arsitekur LEAP5.0 baru saja dibentangkan pada hari teknologi September, bateri CTC3.0, pemanduan bantuan LWM, MM-i hibrid elektrik semuanya dipasang pada satu kerangka. Selepas kadar penggunaan umum arkitektur dinaikkan, semakin banyak sistem kuasa, kabel, dan kawalan kawasan perkongsian antara SUV dan sedan, semakin nipis kos penyelidikan per unit.
Kuantiti pendaftaran Eropah top 3, lebih bernilai sepuluh kali ganda daripada eksport 150,000 unit
Eksport tunggal September 27,000 unit +, Januari-September terkumpul melebihi 150,000 unit, menyerahkan laporan matlamat eksport 2026 lebih awal. Perancis, Jerman, Itali, Sepanyol, empat pasaran teras Eropah, jumlah pendaftaran sepenuhnya elektrik masuk top tiga.
Jumlah eksport adalah angka di atas kapal, jumlah pendaftaran adalah angka di jalan. Yang pertama boleh dibuat dengan menekan stok, yang kedua memerlukan pengguna benar-benar membayar, loket benar-benar menghantar, pemeliharaan benar-benar menerima. Leapmotor memanfaatkan saluran Stellantis untuk meletakkan lebih daripada 1,000 lokasi di Eropah, perakitan tempatan Malaysia dan Sepanyol juga telah berjalan, mengelak bahagian paling mahal dalam membina saluran pemain baharu.
Bawa D19 ke Paris, bukan untuk pamer otot, tetapi untuk menguji paras
Pameran Kereta Paris Oktober, Leapmotor akan membawa D19 dan A05 masuk. A05 mudah difahami, 510km jangkauan ditambah radar laser ditekan ke bawah 100,000, masih teknologi untuk semua, pergi ke Eropah menjadi sampel kos efektif. D19 berbeza, SUV 5 meter 2 kelas flagship, elektrik sepenuhnya dan range extender, domestik bertanggungjawab menaikkan harga purata, Paris bertanggungjawab membina imej.
Media asing lebih peduli, adakah jenama China yang naik berdasarkan strategi kos, boleh berdiri teguh di pintu syarikat kereta lama dengan perkataan 'premium'. Malah D19 ini bukan untuk menerima pesanan, tetapi untuk menguji tahap penerimaan premium Eropah terhadap jenama Leapmotor.
Jangan tergesa-gesa mengangkatnya menjadi jenama global
Menulis sehingga sini perlu menyejukkan sedikit, jualan bulanan stabil 100,000, pendaftaran Eropah masuk top 3, Paris ada flagship, Leapmotor memang sudah ke posisi paling depan pemain baharu, tetapi belum masa untuk menarik nafas lega.
Suku keempat lihat tiga perkara, bolehkah penghantaran bulanan capai 110,000 tanpa kembali; pendaftaran Eropah bolehkah berkembang dari 4 negara top 3 ke Eropah Utara dan United Kingdom; adakah selepas LEAP5.0 turun D19 jenis kereta boleh menaikkan harga purata per unit dengan sebenar. Ketiga-tiga halangan ini dilalui, Leapmotor bukan lagi jenama paling cekap menjimatkan, tetapi syarikat automotif China yang mempunyai hak untuk bernegosiasi sistem dengan pemain global.

September 16, Leapmotor held a Tech Day with the theme "Confidence". On the same day, this company just reached a new milestone: July global deliveries 101,300 vehicles, year-on-year increase 102%, becoming the first domestic new force brand to break 100,000 vehicles in a single month delivery; August reached a new high. In 2025, Leapmotor annual deliveries 596,600 vehicles, sales doubled for two consecutive years; January to August 2026, global sales over 560,000 vehicles, year-on-year increase 70%, ranking top three among China's new energy passenger car brands. Just at a time when most new forces are still struggling near the break-even point and the price war continues relentlessly, this report stands out.
More striking is the expansion overseas. In the first half of the year, Leapmotor exported 96,300 vehicles, a year-on-year surge of 372.6%, exceeding the total export volume for the full year of 2025; Leapmotor International has built over 1,000 sales and service outlets in 45 markets, with pure electric market share in Italy exceeding 25%, and in June became the highest selling Chinese EV brand in the German market; T03, C10 have become popular choices in the European affordable pure electric market, and the Malaysia knock-down assembly plant has also started production. When most peers are still fighting closely domestically, this company has moved a considerable portion of its growth overseas.
Sales on the rise, global expansion accelerating, what does it rely on? The answer given by the Tech Day is the systematic capability accumulated over 11 years.

First, let's look at the cost structure. Leapmotor has built 18 parts factories, self-developed and self-produced covers 65% of total vehicle cost, and platform commonality reaches 90%. This explains why "Good technology should be accessible to everyone" is not just a slogan: Advanced intelligent driving goes down to the 100,000 yuan class; CTC 3.0 eliminates independent low-voltage batteries, saving 2,000 yuan per vehicle; for the earliest batch of LiDAR users upgrading to World Model Intelligent Driving, it requires an investment of 50 million yuan, but Leapmotor chose a free upgrade and free usage for life. Self-development squeezes costs to places others cannot, so cross-tier configurations can possibly become standard configurations.
Second, look at the technology system. Leapmotor released not just one highlight, but a set of architecture plus three major systems plus multiple reserves: LEAP 5.0 vehicle architecture achieves over 100% utilization rate; LWM World Model Intelligent Driving allows vehicles to go from "remembering road conditions" to "understanding road conditions"; long-tail scenarios encountered by a vehicle are learned via the cloud, allowing the fleet to collaboratively evolve; MM-i Multi-mode Hybrid Electric Drive completes the PHEV puzzle, completing "Pure Electric + Extended Range + PHEV" full power layout, with power 28% higher than peer vehicles and weight 40% lighter; CTC 3.0 eliminates independent low-voltage batteries, increasing energy capacity 7 times, with related patents open-sourced to the entire industry — and this generation of batteries is built upon verification from over 1 million vehicles installed. From architecture to batteries, from intelligent driving to robots, every item points to mass production and implementation. Zhu Jiangming said Leapmotor does not innovate for the sake of showing off skills — behind this statement is the industry stuck in stock competition on screens, computing power, and configurations.

The root of growth against the trend may lie in this kind of "hard work": not chasing short-term concepts, but sinking resources into underlying R&D and product experience. Embodied AI robot concepts are hot, but Leapmotor said "Only robots that can make money are worth showing off"; Direct-drive PHEV is viewed bearishly by some, but Leapmotor judges it still has a 5 to 10-year lifecycle. Technological pragmatism eventually manifests as operational stability. Since the mass production of the first extended-range model in 2022, Leapmotor has launched 7 extended-range models, and every structure of the electric drive system comes from internal co-creation, rather than bought solutions.
Why do sales and the capital market succeed frequently? The underlying logic is consistent: the positive cycle of scale and profitability. In the first half of the year, Leapmotor revenue was 38.1 billion yuan, net profit 210 million yuan, profits for three consecutive half-years — at a time when the industry generally doesn't make money, this profit is scarce. Overseas markets contribute high gross margin growth, with more than half of new sales coming from overseas in the first half of the year. What the capital market values is this "profitable long-termism". Since HK stock listing, Leapmotor market cap once stood at 60 billion HKD, and brokers still give overweight ratings and higher target prices. Of course, the market does have doubts: the year-start 5 billion yuan profit guidance was lowered to around 3 billion yuan, and the stock price still has corrections within the year. The quality of profits still needs time to test.
For China's automotive industry, Leapmotor's significance may not lie in the sales figures themselves. When price wars put pressure on the entire industry, it proves a different path: relying on full-domain self-research to keep both costs and experience in its own hands, going from "competing on price" to "competing on technology"; when whole vehicle export encounters resistance, it uses technology output, localization, and patent open-sourcing to turn "product export" into "capability export". As Zhu Jiangming said, technology and innovation are the confidence of enterprises facing the future. A car enterprise that can sustain profits and export systems overseas may well be the footnote most needed for China's automotive industry to become from big to strong.
16 September, Leapmotor menganjurkan Hari Teknologi dengan tema "Keyakinan". Pada hari yang sama, syarikat ini baru sahaja mencapai tonggak baharu: Pada Julai, serahan global mencecah 101,300 kenderaan, meningkat 102% berbanding tahun lalu, menjadi jenama Pembuat Baharu pertama di dalam negara yang mencapai serahan bulanan melebihi 100,000 kenderaan; Ogos menyaksikan rekod baharu sekali lagi. Pada tahun 2025, serahan tahunan Leapmotor mencecah 596,600 kenderaan, dengan jualan berlipat ganda selama dua tahun berturut-turut; Januari hingga Ogos 2026, jualan global melebihi 560,000 kenderaan, meningkat 70% berbanding tahun lalu, menduduki tiga teratas dalam jenama kenderaan penumpang baharu di China. Pada masa ini, apabila majoriti Pembuat Baharu lain masih bergelut di sekitar garis keuntungan dan rugi serta perang harga yang tidak berkesudahan, rekod prestasi ini nampak sangat ketara.
Yang lebih menarik perhatian ialah ekspatriasi keluar luar. Paruh pertama tahun ini, Leapmotor mengeksport 96,300 kenderaan, melonjak 372.6% berbanding tempoh sama, melebihi jumlah eksport keseluruhan tahun 2025; Leapmotor International telah membina lebih daripada 1,000 rangkaian perkhidmatan jualan di 45 pasaran, dengan pasaran kenderaan elektrik tulen di Itali melebihi 25%, pada Jun menjadi jenama kenderaan elektrik China dengan jualan tertinggi di pasaran Jerman; T03, C10 menjadi pilihan popular dalam pasaran kenderaan elektrik tulen harga mampu milik Eropah, kilang pemasangan KD di Malaysia juga telah mula beroperasi. Apabila kebanyakan rakan sekerja masih bergelut rapat di dalam negara, syarikat ini telah memindahkan sebahagian besar peningkatan, ke luar negara.
Jualan meningkat, ekspatriasi semakin laju, kepada apakah kepercayaannya? Jawapan yang diberikan oleh Hari Teknologi adalah keupayaan berstruktur yang dikumpul selama 11 tahun.
Pertama, lihat struktur kos. Leapmotor telah membina 18 kilang komponen, penyelidikan dan pembuatan sendiri merangkumi 65% kos keseluruhan kenderaan, tahap umum platform mencecah 90%. Ini menjelaskan mengapa "Teknologi baik boleh diakses semua orang" bukan sekadar slogan: Pemanduan pintar tahap tinggi diturunkan ke tahap 100,000 Yuan; CTC3.0 membatalkan bateri rendah voltan bebas, menjimatkan 2,000 Yuan setiap kenderaan; Pengguna LiDAR paling awal menaik taraf ke pemanduan pintar model dunia perlu melabur 50 juta Yuan, Leapmotor memilih untuk menaik taraf percuma, penggunaan percuma seumur hidup. Penyelidikan sendiri menekan kos ke lokasi yang tidak boleh dicapai orang lain, konfigurasi peringkat lebih tinggi sahaja mungkin berubah menjadi konfigurasi standard.
Kedua, lihat sistem teknologi. Apa yang dilancarkan oleh Leapmotor bukan sekadar satu titik panas, tetapi satu set struktur ditambah tiga sistem utama ditambah pelbagai rizab: Struktur keseluruhan kenderaan LEAP5.0 menghasilkan kadar bilik lebih daripada 100%; Pemanduan pintar model dunia LWM membolehkan kenderaan bergerak dari "mengingati keadaan jalan" menuju "memahami keadaan jalan", satu kenderaan menemui senario ekor panjang yang melalui pembelajaran awan, pasukan kenderaan boleh berevolusi secara sama rata; MM-i electric drive hibrid pelbagai mod melengkapkan teka-teki plug-in hybrid, menyelesaikan susunan daya penuh "eletrik tulen + pelanjutan julat + plug-in hybrid", kuasa lebih tinggi 28% berbanding kelas yang sama, berat lebih ringan 40%; CTC3.0 membatalkan bateri rendah voltan bebas, keupayaan bateri meningkat 7 kali ganda, paten berkaitan dibuka secara sumber terbuka kepada keseluruhan industri — dan bateri generasi ini, dibina di atas pengesahan pemasangan melebihi satu juta kenderaan. Dari struktur ke bateri, dari pemanduan pintar ke robot, setiap satu menunjukkan kepada pengeluaran jisim, pelaksanaan yang boleh dilaksanakan. Zhu Jiangming berkata, Leapmotor tidak berinovasi untuk memamerkan kemahiran — di belakang ayat ini, industri sedang terperangkap dalam persaingan stok skrin, pengiraan kuasa dan konfigurasi.
Punca pertumbuhan menentang arus, mungkin terpendam dalam "usaha bodoh" jenis ini: tidak mengejar konsep jangka pendek, menenggelamkan sumber ke penyelidikan peringkat asas dan pengalaman produk. Konsep robot pintar berbadan fizikal sangat panas, tetapi Leapmotor berkata "hanya robot yang boleh menghasilkan wang yang boleh dipamerkan"; Plug-in hybrid teras langsung dilihat rendah oleh sesetengah orang, Leapmotor menilai ia masih mempunyai tempoh hayat 5 hingga 10 tahun. Kelewatan dalam teknologi, pada akhirnya diwujudkan sebagai pengurusan yang mantap. Sejak model pelanjutan julat pertama memasuki pengeluaran jisim pada tahun 2022 sehingga kini, Leapmotor telah melancarkan 7 model pelanjutan julat, setiap struktur sistem elektrik berasal daripada kerjasama dalaman, bukan pembelian cadangan.
Mengapa jualan dan pasaran modal sering berjaya? Logik asas sama: kitaran positif skala dan keuntungan. Paruh pertama tahun ini, pendapatan Leapmotor 38.1 bilion Yuan, keuntungan bersih 210 juta Yuan, untung selama tiga tempoh setengah tahun berturut-turut — pada masa ini industri secara umum tidak menghasilkan wang, keuntungan ini adalah unik. Pasaran luar negara menyumbang peningkatan margin tinggi, lebih separuh daripada jualan baharu paruh pertama tahun ini berasal dari luar negara. Apa yang dilihat pasaran modal ialah "penganut jangka panjang yang pandai mengira bil" ini. Sejak disenaraikan di bursa saham Hong Kong, pasaran nilai Leapmotor pernah mencapai 60 bilion HKD, broker masih memberikan penilaian overweight dan harga sasaran yang lebih tinggi. Tentu saja, pasaran tidak sepenuhnya bebas keraguan: bimbingan keuntungan 5 bilion Yuan pada awal tahun diturunkan kepada sekitar 3 bilion Yuan, harga saham masih mempunyai pelarasan dalam tahun ini. Keaslian keuntungan, masih memerlukan masa untuk diuji.
Bagi industri automotif China, makna Leapmotor mungkin bukan pada nombor jualan itu sendiri. Apabila perang harga membuat industri menghadapi tekanan, ia membuktikan jalan yang berbeza: bergantung pada penyelidikan sendiri serantau, memegang kos dan pengalaman dalam tangan sendiri, dari "berlumba harga" menuju "berlumba teknologi"; Apabila eksport kenderaan keseluruhan menghadapi rintangan, ia menggunakan output teknologi, tempatan dan paten sumber terbuka, mengubah "produk keluar laut" menjadi "keupayaan keluar laut". Seperti yang dikatakan Zhu Jiangming, teknologi dan inovasi adalah kepercayaan industri yang menghadap masa depan. Sebuah syarikat kenderaan yang boleh untung berterusan, boleh mengeksport sistem ke luar negara, mungkin tepatlah catatan yang paling diperlukan oleh industri automotif China untuk menjadi besar menjadi kuat.
Monthly sales of 100,000, yet market cap only half of competitors: Why can't Leapmotor's scale earn valuation?

Evening of August 24, Leapmotor released an interim performance report with almost flawless data: First half deliveries 356,487 units, YoY growth 60.8%, ranking first among New EV makers; Revenue 38.11 billion yuan, growth 57.2%; Net profit attributable 208 million yuan, achieving profitability for two consecutive half-years. July single-month deliveries 101,267 units, becoming the first domestic New EV maker to break 100,000 monthly sales. Established for 11 years, cumulative deliveries exceeded 1.6 million units.

Leapmotor displayed its full series of models at a promotion event | Source: Leapmotor official website
But the reaction from the capital market was quite interesting. As of the August 26 market close, Leapmotor's HK stock market cap was approximately HKD 45.36 billion; on the same day, Nio was about HKD 85.5 billion, XPeng about HKD 88.4 billion, and Li Auto about HKD 97.7 billion. The one selling the most, its market cap is less than half of Li Auto. More importantly, Li Auto's second-quarter net loss was 1.705 billion yuan, XPeng's second-quarter net loss was 1.34 billion yuan — they are making losses, yet the market is willing to give them higher prices.
Being the sales champion doesn't beat the market cap, this is not just a problem for Leapmotor, but it is Leapmotor's most prominent issue. This deep dive wants to clearly break down three things: how exactly these 200 million in profit was squeezed out; why that overseas report is Leapmotor's real trump card; and what evidence the market is waiting for before re-pricing this company.
01 How the 200 Million in Profit was "Squeezed" OutFirst, let's look at the profit structure. First half revenue of 38.11 billion yuan and 11.7% comprehensive gross margin, corresponds to gross profit of approximately 4.45 billion yuan. After deducting R&D, sales, administrative and other period expenses and taxes, final operating profit was 128 million yuan, with net profit attributable to shareholders of 208 million yuan.
Converted to per unit: 356,487 vehicles, with an average profit of only about 585 yuan per car. A 100,000 yuan level car, profit isn't enough for a decent meal. Net margin 0.55%, thin as a blade.

Leapmotor 2026 Semi-Annual Report · Performance Highlights | Source: Leapmotor official website
These 208 million are pieced together from several parts. The first part is selling cars itself. Management gave whole vehicle gross margin guidance of 10~11 percentage points at the conference call — meaning selling cars is low profit high volume, the bulk of gross margin depends on scale rolling. The second part is carbon credits, contributing 800 to 900 million yuan in the first half, about 500 million yuan in the second quarter. This is the profit's "plug-in", and its unit price is declining, management original words: "Carbon credit sales unit price fell compared to last year", "Just like the path our country walked back then". The third part is R&D service revenue, contributed in the first half but not much; the fourth part is Leapmotor International, slightly profitable but with a small loss in the first half due to exchange rates, management expects to recover in the second half.
The trend of gross margin also hides structure: First half comprehensive gross margin 11.7%, YoY decline of 2.4 percentage points, but second quarter single quarter recovered to 12.6%, QoQ improvement 3.2 percentage points. Full year guidance is 13%~14%. Management attributed the improvement to scale effect and raw material price stabilization — to translate: volume growth is diluting per-unit cost, but carbon credit decline is pulling profit margin back from the other side.
Compare with peers, the irony is stronger. Li Auto second-quarter net loss 1.705 billion yuan, deliveries 98,330 units, YoY still declined 11.5%; XPeng second-quarter net loss 1.34 billion yuan. Full market only Leapmotor, the only New EV maker stable in making money, market cap yet bottomed out. In Tech Jungle's view, the market is not that it doesn't recognize profit, but doesn't recognize "profit of doubtful gold content" and "profit that hasn't proven sustainable scaling".
02 Going Overseas: The Real Profit Pool is FormingLeapmotor interim report's most eye-catching numbers are actually not in the domestic market. First half exports 96,294 units, YoY growth 372.6%, already exceeded 2025 full year export total, accounting for 27% of total sales; July single month exports 17,569 units. European market revenue 8.875 billion yuan, YoY surge 379.7%, accounting for about 23% of total revenue.

Leapmotor exceeded 900,000 global deliveries in June | Source: Leapmotor official website
Overseas per-unit gold content is far higher than domestic: Same platform models selling price in Europe is several times that of domestic, even after incurring freight, tariffs and channel costs, per-unit gross margin is clearly better than the involution of domestic market. This is the real meaning of "Second growth curve" — not selling tens of thousands more cars, but selling a market with higher profit margin.
Local assembly map also unfolds simultaneously: Malaysia relies on Stellantis Kedah plant, C10 already mass production, B10 planned Q3 mass production launch; European Spain Zaragoza plant completed retrofit, B10 Q3 start production, B05 trial production within the year, 2027 formal mass production, supporting battery plant Q3 start mass production; South America selected Brazil Goiania plant, B10 planned 2027 second half start production. Management stance is: This year overseas expected around 200,000 units (start of year target 100,000~150,000 units), next year target 350,000~400,000 units, internal challenge 400,000 units.
But management also said two sentences worth noting truths. First is local production gross margin indeed better than whole vehicle export has improvement, "but improvement not as obvious as imagined", profit margin's real improvement needs to wait for "policy changes" — simply put, wait for EU tariff and local procurement rules to clear. Second is RoRo ship capacity tight, company has reached cooperation with Shipping Group, "Full year 200,000 units is guaranteed". Going overseas doesn't lack orders, lacks capacity and policy window.
There is also a detail ignored by most interpretations: Leapmotor International is Leapmotor 49%, Stellantis 51% joint venture, when established agreed on previous three years lower gross margin split. Management explicitly said at conference call, both parties "3-year agreement period" gradually approaching, will sit down to re-communicate. This is both an area where first half comprehensive gross margin was "structurally suppressed" dark corner, also potential option for gross margin upward repair in future one to two years — Stellantis sells every car, after re-pricing may contribute more profit.
03 Balance Sheet: Where Did Money and Goods GoSeveral numbers on the interim report balance sheet explain Leapmotor's current strategy better than income statement.

Leapmotor 2026 Semi-Annual Report · Financial Performance | Source: Leapmotor official website
Cash and equivalents 38.59 billion yuan, borrowing only 2.39 billion yuan, net cash over 36 billion yuan. A car company with annual sales of hundreds of thousands of units holding such scale of cash, at least on cash flow there is no danger signal.
What is truly worth pondering is inventory: 9.27 billion yuan, QoQ increase 103.7%, approximately equal to 1.65 months cost of sales. Why prepare so much inventory? Two months ago this number was not even half. The answer is written in the timeline: A05 launched on August 11, A10 enter ramp-up, D19 and C series volume, second half delivery target obviously is to go high; plus exports in transit whole vehicles and parts all floating at sea, inventory double more like intentional "ammo".
More ruthless is accounts payable: 47.08 billion yuan, is 5.1 times inventory. This shows in supply chain system, upstream suppliers are advancing funds for Leapmotor. Use suppliers' goods first, then pay money, account period dragged longer, Leapmotor cash more abundant. This is an invisible low cost financing, also realization of scale effect — only when your procurement volume large enough no one dares easily cut supply, this chain then can move. Huawei-style "V-formation supply chain" in auto industry replicate difficulty compared to consumer electronics is much bigger, but Leapmotor is trying to run with same logic.
Future two years still need to spend a big sum: As of end of June, company for purchase of properties, factory and equipment capital commitments were 7.76 billion yuan, first half capital expenditure 2.03 billion yuan, mainly used for new factory equipment and new car production line introduction. Where do these money go? Answer is 2027 — management's words "very big product big year": D series brand new models, C series existing brand new and also replacement, B series new products. 2026 profit, largely is for 2027 product matrix storing water.
04 FAW and Stellantis: Two "Technology for Market" AccountsAugust 24, same day financial report release, Leapmotor and China FAW signed deepening cooperation framework, listed ten major synergy fields: Battery, Electric Drive, Chassis, Intelligent Cockpit, Intelligent Driving, Auto Electronics, Whole Vehicle Design Manufacturing, Export, Supply Chain, and Embodied AI Robot. Time line extended look, March 3, 2025 both parties signed strategic cooperation MOU, December 28, 2025 FAW subscribed about 5% domestic shares with 3.744 billion yuan (per share 50.03 yuan) — this investment's book floating loss, according to Chegulu Media calculation already exceeded 1 billion yuan (Aug 19); and concurrently, founder Zhu Jiangming was reported multiple announcements increase holdings.

Leapmotor and China FAW signed deepening strategic cooperation agreement | Source: Leapmotor official website
A state-owned giant floating loss, founder investing against trend, both parties again on financial report day announced ten major synergy — this set of signals put together, reads like a "Long-termist mutual confirmation" agreement. Leapmotor wants one FAW R&D synergy and policy resources, FAW wants Leapmotor full domain self-developed powertrain ready-made capability, use money and technology double binding.
Another line is Stellantis. 2023 shareholding, May 2024 established Leapmotor International, May 2026 both parties announced cooperation upgrade (Opel etc brand dedicated production line and technical support, according to public reports). Conference call management revealed, cooperation direction with Stellantis is "Empowerment based on mature powertrain component supply capability", and "Recent very likely there will be further good news"; With FAW, Stellantis R&D service cooperation, "Very soon everyone will receive external announcement".
This words actually already fulfilled half: FAW framework agreement is announcement day hammered. Leapmotor is upgrading "Selling cars" into "Selling cars + Selling technology + Selling supply chain capability" three parts income. This is also Zhu Jiangming repeatedly publicly expressing "Market cap undervalued" confidence source — market gives Leapmotor valuation according to whole vehicle manufacturer, but its financial statements are growing into technology exporter shape.
05 Robots: Second Curve Waiting Behind AnnouncementAnd FAW's ten synergy list appeared "Embodied AI Robot", this is official level first time writing robot into cooperation framework. Accompanying public business information (Leapmotor power subsidiary business scope newly added robot related content), and conference call management "Company has robot related planning, very soon will formal announcement" statement, Leapmotor's robot business has entered "Night before official announcement" from "Rumors".
But to speak rigorous: Robot currently still is expectation, not profit. Before announcement landing, it is just valuation imagination option. Management at conference call also confirmed, September 16 will hold technology launch conference in Huzhou, Zhejiang, heavyweight content concentrated on Intelligent Driving, Battery and Electric Drive — this is future few weeks most immediately visible catalyst, Robot is farther that "Easter egg".
Risks also need to be mentionedOutside bullish, a few risks worth listing on table.
First is carbon credit decline. First half 80~900 million points income pushed net profit to 200 million, but unit price is returning towards "Country back then path". If next year points income shrinks, and whole vehicle gross margin not substantially stand at 13%~14%, profit statement will be hit back to original form. Leapmotor needs to use real material scale effect, to fill points decline dug hole.
Second is customer concentration. Financial report disclosed single largest customer contribution accounted for about 23.3% revenue ratio — combine European revenue scale and joint relationship, overseas big customers are double-edged sword: It supports growth, also handed over fate's much part into others hands.
Third is policy window. EU localization procurement proportion requirement is rising, anti-subsidy tax and price commitment "Soft landing" whether continue, directly decides 2027 400,000 units overseas target whether can fulfill; and localization profit margin improvement, management also said "Needs policy changes".
Fourth is execution difficulty. Next year overseas 350,000~400,000 units, means need to on this year about 200,000 units basis close to double, capacity, channel, localization capacity three lines parallel, any link fail chain will transmit to report.
Conclusion: Monthly Sales of 100,000 is Just an Entry Ticket
Leapmotor full series of models lineup | Source: Leapmotor official website
In Tech Jungle's view, market cap repair not rely on shouting, market wants three verifiable evidence: Whole vehicle gross margin whether can stabilize 13%~14% and continue upward, prove "Selling cars itself can make money"; Carbon credits decline after profit not empty, prove "Profit is real"; Overseas 350,000~400,000 units and robot announcement quality, prove "Second curve is not an empty promise".
This half year, Leapmotor proved itself can use extremely low per-unit profit roll up scale, also can hold cash firmly in hand — Net cash over 36 billion, Accounts payable leverage 470 billion supply chain account period, this is not every New EV maker can do. But capital market not pay for "Amazing", only pay for "Proven sustainability".
Monthly sales of 100,000 is just an entry ticket, net profit of 200 million is a passing score, and dozens of times market cap gap, need to rely on next one or two years' report page by page to fill.
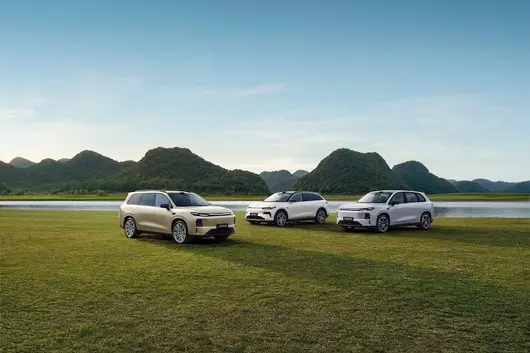
Jualan Bulanan 100,000, Nilai Pasaran Hanya Setengah Pesaing: Mengapa Skala Leapmotor Tidak Mendapat Penilaian Yang Setimpal?
Malam 24 Ogos, Leapmotor menyerahkan skor pertengahan tahun yang hampir tiada cela dari segi data: Paruh pertama tahun ini menghantar 356,487 unit, meningkat 60.8% berbanding tahun lalu, berada di tangga teratas jualan syarikat automotif baharu; pendapatan 38.11 bilion Yuan, meningkat 57.2%; untung bersih yang diwakili 208 juta Yuan, mencatatkan keuntungan selama dua sesi setengah tahun berturut-turut. Pada bulan Julai sahaja, serahan mencapai 101,267 unit, menjadi syarikat automotif baharu pertama di China yang melampaui jualan 100,000 unit sebulan. Telah genap 11 tahun ditubuhkan, jumlah serahan terkumpul telah mencapai lebih 1.6 juta unit.
Kereta Leapmotor mempamerkan semua model di bawah naungannya dalam acara promosi | Sumber gambar: Tapak rasmi Leapmotor
Tetapi reaksi pasaran modal agak menarik perhatian. Sehingga penutupan pada 26 Ogos, nilai pasaran saham Leapmotor di Hong Kong adalah kira-kira 45.36 bilion Dolar Hong Kong; pada hari yang sama, Nio adalah 85.5 bilion, Xpeng 88.4 bilion, Li Auto 97.7 bilion Dolar Hong Kong. Yang menjual paling banyak, nilai pasarnya kurang daripada separuh daripada Li Auto. Lebih membezakan, Li Auto mencatat kerugian bersih 1.705 bilion Yuan pada suku kedua, Xpeng kerugian bersih 1.34 bilion Yuan pada suku kedua — mereka rugi, tetapi pasaran masih mahu memberikan harga yang lebih tinggi.
Jualan juara tidak menang dalam nilai pasaran, bukan masalah hanya untuk Leapmotor, tetapi masalah paling ketara bagi Leapmotor. Kajian mendalam ini ingin membongkar tiga perkara: bagaimana untung sebanyak 200 juta itu dipijit; mengapa laporan kewangan luar negara adalah kad terakhir sebenar Leapmotor; dan bukti apa yang menunggu pasaran, sebelum mereka menetapkan semula harga untuk syarikat ini.
01 Untung Sebanyak 200 Juta, Bagaimana Dipijit?Lihat dahulu struktur keuntungan. Pendapatan 38.11 bilion Yuan pada paruh pertama, dengan marjin kasar komposit 11.7%, sepadan dengan marjin kasar kira-kira 4.45 bilion Yuan. Tolak kos tempoh seperti penyelidikan, jualan, pentadbiran dan cukai, akhirnya keuntungan operasi 128 juta Yuan, untung bersih yang diwakili kepada pemegang saham sebanyak 208 juta Yuan.
Dipercikkan kepada setiap unit: 356,487 unit kereta, purata keuntungan setiap unit hanya kira-kira 585 Yuan.Kereta peringkat 100,000 Yuan, keuntungan tidak cukup untuk makan malam makan bersama yang layak.Kadar keuntungan bersih 0.55%, nipis seperti pisau.
Laporan Kewangan Setengah Tahun Leapmotor 2026 · Poin Prestasi | Sumber gambar: Tapak rasmi Leapmotor
208 juta ini terdiri daripada beberapa bahagian. Bahagian pertama adalah menjual kereta itu sendiri. Pengurusan dalam panggilan telefon memberikan panduan marjin kasar kereta keseluruhan ialah 10~11 mata — dengan kata lain, menjual kereta adalah margin rendah, fokus pada kuantiti, marjin kasar besar-besaran bergantung pada skala berputar. Bahagian kedua adalah kredit karbon, menyumbang 8 hingga 9 bilion pada paruh pertama, kira-kira 5 bilion pada suku kedua. Ini adalah "ekstern" keuntungan, dan harga unitnya sedang menurun, perkataan pengurusan: "Harga jualan kredit karbon menurun berbanding tahun lalu, "Sama seperti jalan yang negara kita lalui dahulu". Bahagian ketiga adalah pendapatan perkhidmatan penyelidikan, menyumbang pada paruh pertama tetapi tidak besar; Bahagian keempat ialah Leapmotor Antarabangsa, sedikit untung tetapi pada paruh pertama rugi sedikit disebabkan kadar tukaran, pengurusan dijangka memulihkannya pada separuh kedua tahun.
Jalannya marjin kasar juga menyembunyikan struktur: Marjin kasar komposit paruh pertama 11.7%, menurun 2.4 mata berbanding tahun lalu, tetapi suku kedua kembali ke 12.6%, membaik pulih 3.2 mata secara berbanding suku lepas. Panduan tahunan ialah 13%~14%. Pengurusan mengaitkan penambahbaikan kepada efek skala dan penguncian harga bahan mentah — terjemah: Pertumbuhan kuantiti sedang mencairkan kos per unit, tetapi penurun kredit karbon sedang menarik marjin keuntungan kembali dari sebelah lain.
Bandingkan dengan pesaing, rasa sindiran lebih kuat. Li Auto kerugian bersih 1.705 bilion Yuan pada suku kedua, menghantar 98,330 unit, menurun 11.5% berbanding tahun lalu; Xpeng kerugian bersih 1.34 bilion Yuan pada suku kedua. Keseluruhan pasaran hanya ada satu syarikat automotif baharu Leapmotor yang untung stabil, nilai pasaran paling bawah. Dalam pandangan "Tech Jungle", pasaran bukan tidak mengenali keuntungan, tetapi tidak mengenali "keuntungan yang nilai kandungan diragui" dan "keuntungan yang belum membuktikan dapat membesarkan secara berterusan".
02 Penembusan Luar Negara: Kumpulan Keuntungan Sejati Sedang TerbentukAngka yang paling terang dalam laporan tengah tahun Leapmotor sebenarnya bukan di dalam negara. Pada paruh pertama, eksport 96,294 unit, meningkat 372.6%, telah melebihi jumlah eksport keseluruhan 2025, mewakili 27% daripada jumlah jualan; pada bulan Julai sahaja eksport 17,569 unit. Pendapatan pasaran Eropah 88.75 bilion Yuan, meningkat 379.7% secara tahunan, mewakili kira-kira 23% daripada jumlah pendapatan.
Leapmotor menghantar lebih 90,000 unit di seluruh dunia pada Jun | Sumber gambar: Tapak rasmi Leapmotor
Kandungan nilai setiap unit kereta di luar negara jauh lebih tinggi daripada di dalam negara: Harga kereta platform yang sama di Eropah adalah beberapa kali ganda harga di dalam negara, walaupun menanggung kos pengangkutan, cukai pintu dan kos saluran, marjin kasar per unit jelas lebih baik daripada pasaran domestik yang bersaing sengit. Ini adalah makna sebenar "Lengkung Pertumbuhan Kedua" — bukan menjual beberapa puluh ribu unit kereta, tetapi menjual pasaran dengan marjin keuntungan lebih tinggi.
Peta pemasangan tempatan juga sedang bertabur: Malaysia bergantung pada kilang Stellantis di Negeri Kedah, C10 telah menghasilkan secara besar-besaran, B10 dijadualkan menghasilkan pada suku ketiga; Kilang Zaragoza, Sepanyol di Eropah telah siap diubahsuai, B10 akan memulakan pengeluaran pada suku ketiga, B05 akan melakukan percubaan pengeluaran pada tahun ini, 2027 akan memulakan pengeluaran secara besar-besaran, kilang bateri penyertaan akan memulakan pengeluaran pada suku ketiga; Amerika Selatan memilih kilang Goiânia, Brazil, B10 dijadualkan memulakan pengeluaran pada separuh kedua 2027. Kalimat pengurusan ialah: Tahun ini eksport di luar negara dijangka sekitar 200,000 unit (sasaran awal 100,000~150,000 unit), sasaran tahun depan 350,000~400,000 unit, cabaran dalaman 400,000 unit.
Tetapi pengurusan juga berkata dua kenyataan yang perlu diambil perhatian. Pertama, marjin kasar pengeluaran tempatan memang lebih baik daripada eksport kereta keseluruhan, "Tetapi penambahbaikan tidak jelas seperti yang dijangka", peningkatan sebenar marjin keuntungan perlu menunggu "perubahan dasar" — secara mudahnya, tunggu ketelusan cukai Eropah dan peraturan pembelian tempatan. Kedua, kapasiti kapal roll-on/roll-off agak ketat, syarikat telah mencapai kerjasama dengan syarikat pelayaran, "200,000 unit setahun adalah terjamin". Eksport tidak kekurangan pesanan, kekurangan adalah kuasa angkut dan tingkap dasar.
Ada butiran yang diabaikan oleh kebanyakan interpretasi: Leapmotor Antarabangsa adalah syarikat patuh 49% Leapmotor, 51% Stellantis, ketika ditubuhkan, telah menetapkan bahagian marjin kasar yang lebih rendah untuk tiga tahun pertama. Pengurusan dalam panggilan telefon dengan jelas berkata,"Perjanjian tiga tahun antara kedua-dua pihak sedang mendekati, akan duduk bersama untuk berkomunikasi semula. Ini adalah salah satu sudut gelap di mana marjin kasar komposit paruh pertama "ditekan secara institusi", juga merupakan opten berpotensi untuk pembaikan marjin kasar ke atas dalam satu hingga dua tahun akan datang — setiap unit kereta yang dijual oleh Stellantis, setelah ditetapkan semula harga, mungkin menyumbang satu lagi bahagian keuntungan.
03 Neraca Kewangan: Ke mana pergi Wang dan Barang?Beberapa angka dalam Neraca Kewangan laporan tengah tahun, lebih menjelaskan strategi Leapmotor sekarang berbanding laporan untung rugi.
Laporan Kewangan Setengah Tahun Leapmotor 2026 · Prestasi Kewangan | Sumber gambar: Tapak rasmi Leapmotor
Tunai dan setara tunai 38.59 bilion Yuan, pinjaman hanya 2.39 bilion Yuan, tunai bersih melebihi 36 bilion Yuan. Sebuah syarikat automotif yang menjual beberapa ratus ribu unit setahun memegang tunai berskala sebegini, sekurang-kurangnya pada aliran tunai tiada sebarang isyarat bahaya.
Sesuatu yang perlu difikirkan ialah stok: 9.27 bilion Yuan, meningkat besar 103.7% secara berbanding suku lepas, kira-kira sama dengan 1.65 bulan kos jualan. Mengapa sediakan banyak barang? Dua bulan dahulu angka ini belum separuh. Jawapan ditulis dalam jadual masa: A05 pelancaran pada 11 Ogos, A10 masuk ke fasa peningkatan, D19 dan siri C meningkat kuantiti, sasaran serahan suku kedua jelas untuk mendaki puncak; ditambah dengan kereta keseluruhan dan komponen yang sedang dalam perjalanan eksport sedang melayang di laut, stok berlipat ganda lebih seperti "amunisi" yang disengajakan.
Lebih kejam ialah akaun belum dibayar: 47.08 bilion Yuan, 5.1 kali ganda daripada stok.Ini menunjukkan dalam sistem rantaian bekalan, pembekal hulu sedang "mendanai" bagi Leapmotor.Gunakan barang pembekal dahulu, bayar kemudian, semakin lama tempoh pembayaran, semakin lancar tunai Leapmotor. Ini adalah pembiayaan kos rendah secara tersembunyi, juga merupakan penunaian efek skala — hanya apabila saiz pembelian anda besar sehingga tiada siapa berani dengan mudah putus bekalan, rantaian ini baru boleh berputar. Rantaian bekalan "Barisan Angsa" gaya Huawei jauh lebih sukar untuk diulang dalam industri automotif berbanding elektronik pengguna, tetapi Leapmotor cuba menjalankan logik yang sama.
Dua tahun akan datang masih perlu belanjakan banyak wang: Sehingga akhir Jun, syarikat telah menanggung komitmen modal untuk aset hartanah, bangunan kilang dan peralatan sebanyak 7.76 bilion Yuan, perbelanjaan modal paruh pertama 2.03 bilion Yuan, terutamanya untuk peralatan kilang baharu dan pengenalan garis pengeluaran kereta baharu. Ke mana wang ini diarahkan? Jawapannya adalah 2027 — "Tahun Produk Besar" yang disebut pengurusan: Siri D model baharu, siri C ada yang baharu dan ada yang ganti, siri B produk baru. Keuntungan 2026, pada tahap besar sedang menyimpan air untuk matriks produk 2027.
04 FAW dan Stellantis: Dua Perkiraan "Teknologi Menukar Pasaran"24 Ogos, pada hari yang sama dengan penerbitan laporan kewangan, Leapmotor menandatangani rangka kerja kerjasama深化 dengan FAW China, menyenaraikan sepuluh bidang perangan: Bateri, pemacu elektrik, kerangka, kabin pintar, pemanduan pintar, elektronik automotif, reka bentuk dan pengeluaran kereta keseluruhan, eksport, rantaian bekalan, dan robot kecerdasan fizikal. Lihat dari garis masa, pada 3 Mac 2025 kedua-dua pihak menandatangani memorandum kerjasama strategik, pada 28 Disember 2025 FAW dengan 3.744 bilion Yuan membeli kira-kira 5% saham domestik (50.03 Yuan setiap saham) — kerugian buku pelaburan ini, kira-kira oleh media已超过 1 bilion Yuan (kata-kata kereta, 19 Ogos); manakala pada masa yang sama, pengasas Zhu Jiangming dilaporkan meningkatkan pegangan beberapa kali.
Leapmotor menandatangani perjanjian kerjasama深化 dengan FAW China | Sumber gambar: Tapak rasmi Leapmotor
Sebuah raksasa kewangan kerajaan rugi buku, pengasas menambah pegangan melawan arus, kedua-dua pihak sekali lagi mengumumkan sepuluh bidang perangan pada hari laporan kewangan — kumpulan isyarat ini apabila digabungkan, dibaca sebagai perjanjian "Penganut Jangka Panjang yang mengesahkan antara satu sama lain". Leapmotor yang FAW mahu sinergi penyelidikan dan sumber dasar, FAW mahu kemampuan sedia ada Leapmotor yang mengembangkan sepenuhnya tiga enjin, dengan wang dan teknologi ikatan ganda.
Garis lain ialah Stellantis. 2023 menyertai saham, Mei 2024 menubuhkan Leapmotor Antarabangsa, Mei 2026 kedua-dua pihak mengisytiharkan peningkatan kerjasama (garis pengeluaran khas untuk brand Opel dan sokongan teknologi, menurut laporan terbuka). Dalam panggilan telefon, pengurusan mendedahkan, arah kerja sama dengan Stellantis ialah "memberi kuasa berdasarkan keupayaan bekalan komponen tiga enjin matang", dan "baru-baru ini ada harapan untuk berita baik lebih lanjut"; dengan kerjasama perkhidmatan penyelidikan FAW dan Stellantis, "Segera anda semua akan menerima pengumuman luar".
Kata-kata ini sebenarnya sudah berlaku setengah: Rangka kerja FAW adalah palu yang ditolak pada hari pengumuman. Leapmotor sedang menaik taraf "menjual kereta" menjadi "menjual kereta + menjual teknologi + menjual kemampuan rantaian bekalan" tiga bahagian pendapatan. Ini juga sumber keyakinan Zhu Jiangming yang berulang kali menyatakan secara terbuka "nilai pasaran disangkal", pasaran menilai harga Leapmotor sebagai pengeluar kereta keseluruhan, tetapi dalam laporan kewangannya sedang tumbuh seperti penerbit teknologi.
05 Robot: Lengkung Kedua yang Menunggu Di Sebalik PengumumanDalam senarai sepuluh bidang perangan kerjasama dengan FAW, muncul "robot kecerdasan fizikal", ini adalah kali pertama di peringkat rasmi robot ditulis dalam rangka kerja kerjasama. Mematuhi maklumat perniagaan terbuka (skop perniagaan anak syarikat kuasa di bawah Leapmotor ditambah kandungan berkaitan robot), dan dalam panggilan telefon pengurusan menyatakan "syarikat mempunyai perancangan berkaitan robot, segera akan ada pengumuman rasmi", perniagaan robot Leapmotor sudah bergerak dari "khabar angin" masuk ke "malam sebelum pengumuman rasmi".
Tetapi katakan dengan tepat: Robot pada masa ini masih berupa harapan, bukan keuntungan. Sebelum pengumuman turun, ia hanyalah opten imaginasi penilaian. Pengurusan dalam panggilan telefon juga mengesahkan, pada 16 September akan diadakan persidangan teknologi di Hu Zhou, Zhejiang, kandungan utama tertumpu pada pemanduan pintar, bateri dan pemacu elektrik — ini adalah katalis yang paling boleh dilihat dalam beberapa minggu akan datang, robot adalah "easter egg" yang lebih jauh.
Risiko, Harus DinyatakanDi luar pandangan Bullish, beberapa risiko perlu disenaraikan di atas meja.
pertama ialah penurunan kredit karbon. Pendapatan kredit 800 juta~900 juta pada paruh pertama yang mendorong keuntungan bersih sehingga 200 juta, tetapi harga unit sedang kembali ke "jalan yang negara lalui dahulu". Jika pendapatan kredit tahun depan menyusut, dan marjin kasar kereta keseluruhan tidak berdiri secara实质 di 13%~14%, laporan keuntungan akan dipukul ke asal. Leapmotor perlu menggunakan efek skala bahan sebenar, untuk mengisi lubang yang digali oleh penurunan kredit.
Kedua ialah kepekatan pelanggan. Pengumuman laporan kewangan mendedahkan pelanggan tunggal terbesar menyumbang kira-kira 23.3% daripada bahagian pendapatan —结合规模和关系 kongsi, pelanggan besar luar negara adalah pedang berbilah dua: Ia menyangga pertumbuhan, juga menyerahkan sebahagian besar nasib ke tangan orang lain.
ketiga ialah tingkap dasar. Tuntutan kadar pembelian tempatan Eropah sedang meningkat, sama ada "pendaran lembut" cukai anti-subsidi dan janji harga diteruskan, secara langsung menentukan sama-sama sasaran 400,000 unit eksport 2027 boleh direalisasikan; dan peningkatan marjin keuntungan tempatan, pengurusan sendiri berkata "perlu perubahan dasar".
Keempat ialah kesukaran pelaksanaan. Tahun depan luar negara 350,000~400,000 unit, bermaksud perlu hampir berlipat ganda pada asas kira-kira 200,000 unit tahun ini, kuasa angkut, saluran, kapasiti tempatan tiga garis berjalan serentak, mana-mana langkah yang megalang akan menghantar ke laporan.
Penutup: Jualan 100,000 Bulanan Hanya Kad Masuk
Rangkaian model penuh Leapmotor | Sumber gambar: Tapak rasmi Leapmotor
Dalam pandangan "Tech Jungle", pembaikan nilai pasaran bukan靠 berseru, pasaran mahu tiga bukti yang boleh disahkan: Sama ada marjin kasar kereta keseluruhan boleh berdiri di 13%~14% dan terus naik ke atas, membuktikan "menjual kereta sendiri boleh untung"; selepas penurunan kredit karbon keuntungan tidak hampa, membuktikan "keuntungan adalah benar"; 350,000~400,000 unit luar negara dan kualiti pengumuman robot, membuktikan "lengkung kedua bukan janji kosong".
Separuh tahun ini, Leapmotor membuktikan dirinya boleh menggunakan keuntungan per unit kereta yang sangat rendah untuk memutar skala, dan masih memegang tunai dengan kuat — tunai bersih melebihi 36 bilion, akaun belum dibayar menggerakkan tempoh rantaian bekalan 47 bilion, bukan setiap syarikat automotif baharu yang boleh lakukan. Tetapi pasaran modal tidak membayar untuk "luar biasa", hanya membayar untuk "keberlanjutan yang boleh dibuktikan".
Jualan 100,000 bulanan hanyalah kad masuk, keuntungan bersih 200 juta adalah gred lulus, manakala jurang puluhan kali ganda nilai pasaran, perlu diisi satu demi satu dari laporan kewangan satu hingga dua tahun akan datang.
Leapmotor has released its 2026 mid-year performance report. Net profit of 210 million yuan, revenue of 38.11 billion yuan, gross margin of 11.7%, cash on hand of 38.59 billion yuan, global deliveries of 356,487 units — if looking only at these figures, you might feel this is a standard report card from a mainstream automaker.

But when viewed together, the story is different.
This is Leapmotor's third consecutive half-year of profitability. Among new force players, few have achieved this. Meanwhile, Leapmotor's deliveries grew 60.8% year-over-year, firmly holding the top spot in sales among Chinese new forces. In the first 5 months of 2026 with published data for comparable terminal registrations, Leapmotor ranked fourth among global new energy passenger car brands — only players like BYD, Tesla, and Geely are ahead.
Do you remember how the industry evaluated Leapmotor a few years ago? Outsiders, half-price Li Auto, price butcher. Looking back now, those labels didn't actually hit the key points. What Leapmotor truly did was find a path of its own: full-domain in-house research to control costs, precise product definition positioning, rapid channel penetration, and returning every saved penny to users. It doesn't seek attention in the busiest battlefield, but every step lands where others pay little attention.
This half-year report is worth breaking down.
Sales and Profitability, Leapmotor Wants Both
First, let's look at sales. 356,487 units, first among new forces, up 60.8% year-over-year. The value of this achievement lies not in the numbers themselves, but in its structure — it's not propped up by a single hit product, but the combined strength of the entire product matrix.

From 60,000 to 300,000, from sedans to SUVs to MPVs, from pure EV to range extender — the A series holds the 100,000 RMB essential market, the B series brings high-end configurations like 800V high-voltage fast charging and dual zero-gravity seats to young users, the C series covers the 120,000-180,000 RMB mainstream home interval, and the D series pulls the average price above 300,000 RMB, taking the brand upwards towards premium. Systematically covering all price points and categories, in the new force camp, Leapmotor is the first.
But the product matrix is just the surface, the real underlying capability is full-domain in-house research. Breaking it down, there are three layers of logic.
First, manufacturing core components in-house. Three-electric systems, domain control, and intelligent driving chip solutions are all self-developed, which means eating the supplier margin layer oneself. This logic is so simple it's almost boring, but it is the fundamental reason Leapmotor can still retain profit margins at the 100,000 level.
Second, one architecture supports a fleet of cars. LEAP 4.0 central domain control architecture launched on D19, dual Snapdragon 8797 chips, cabin-driving integration, one brain controlling all vehicle intelligence, and computing power can also be dynamically allocated between different scenarios. But more importantly, this capability is rolled down from top to bottom — urban pilot assist drive has been opened to full ABCD series and Lafa5, and in Q3, national urban pilot will be pushed to LEAP 3.0 models.
Translated into user language, it's one sentence: a 100,000 RMB car can also have flagship-level intelligent experience. For the enterprise, R&D investment of 2.317 billion yuan is one-time, spread across A10 and D19 is two separate accounts — R&D expenses are diluted by scale, this is the real friend of gross margin.
Third, the product matrix implemented a dual line of 'protect volume + protect price'. C10/C11/C16 hold the 120,000-180,000 RMB base, totaling over 30,000 in June. C11 cumulative sales 350,000 units, it's a perennial tree in the niche market. D19 and D99 lift the average price upwards. D19 launched, 15 days pre-orders broke 15,000, continued champion of large SUV sales within 400,000 RMB. D99 first batch order average price already broke 300,000 yuan. One end for volume, one end for price lift, gross margin structure is quietly pushed up this way.
This is exactly the underlying logic of Leapmotor: good but not expensive — not by sacrificing configurations to reduce costs, but by controlling costs through in-house research and turning saved money into configurations.
Next, look at profitability. Consecutive half-year profitability, gross margin 11.7%, revenue reached historical high — placed together, these numbers mean Leapmotor's business model has been validated. The most questioned aspect of new force car manufacturing these years is rising sales but no profit.
Leapmotor's answer is: combining scale, in-house research, and efficiency, making gross margin positive, then thickening cash flow. The 38.59 billion yuan cash on hand is its confidence to continue investing in R&D and globalization.
Going Global, Leapmotor is Serious
If sales and profitability are Leapmotor's domestic report card for this half year, the overseas market is the second chapter it quietly wrote, and the section is quite large.

First half overseas deliveries 96,294 units, continuing to grow quarter-over-quarter, nearly doubled. Italy pure EV market share over one-quarter, ranking first in local pure EV sales continuously. In the first half, sales leading among Chinese brand EVs in Germany. Ranked third in UK Chinese brand pure EV retail. Entered Mexico in Q2, opening the North American market. Globally covering over 45 international markets, establishing over 1000 sales and service outlets.
More noteworthy is the progress of localized production. In Malaysia, C10 is already mass-produced, B10 follows in Q3. In Spain, B10 starts production in Q3. In Brazil, Stellantis's Goiania plant is selected as the localized assembly base.
This is no longer just selling cars overseas, but rooting overseas. Deep cooperation with Stellantis gives Leapmotor ready-made channels, factories, and localized capabilities overseas. The performance of 96,294 units in overseas sales in the first half is evidence that this approach is working.
Leapmotor's global path is consistent with its logic for the domestic market: not seeking the loudest name, first finding that 'not yet fully competed' position, then standing firm with efficiency and cost advantages. Just like it found a gap in the 100,000-200,000 RMB market back then, today it found the same position in Europe's affordable EV market — where it happens to be the interval where European local car makers find it hardest to make money and most want to exit.
Leapmotor effectively translated the 'cost + efficiency' model verified domestically to the global scale.
At the end of the half-year report, an easter egg is buried: Leapmotor will hold an annual technical conference in September, releasing intelligent driving world models reaching the industry's top tier level and the latest achievements in the three-electric field. The story of full-domain in-house research is still being written downwards.
Looking back at this half year, what Leapmotor did right is actually very simple: control costs to the extreme, define products accurately, position channels fully, and put eyes on the global. No flashy marketing jargon, no earth-shattering price wars, just step-by-step solidifying the four characters 'Good and Not Expensive'.
Consecutive profitability, new force sales champion, global top four — behind these milestones is the same logic: when others are competing in the busiest battlefield, Leapmotor chooses to practice fundamentals to the extreme, then quietly wins on every underestimated track.
This might be the most worthy place for the industry to think about Leapmotor's half-year report.
Leapmotor telah mengeluarkan laporan prestasi pertengahan tahun 2026. Keuntungan bersih 210 juta Yuan, pendapatan 38.11 bilion Yuan, margin kasar 11.7%, tunai semasa 38.59 bilion Yuan, hantaran global 356,487 unit — jika hanya melihat angka-angka ini, anda akan rasa ini merupakan prestasi biasa sebuah pengeluar kereta utama.
Tetapi apabila dilihat bersama, ceritanya berbeza.
Ini merupakan keuntungan setengah tahun ketiga berturut-turut bagi Leapmotor. Dalam kalangan pengeluar baharu, hanya sedikit yang dapat melakukannya. Sementara itu pada tempoh sama, hantaran Leapmotor meningkat 60.8% dari tahun lalu, tetap menduduki puncak jualan pengeluar baharu China. Dalam bilangan pendaftaran kenderaan di terminal sebelum 5 bulan pertama 2026 yang data telah diumumkan, Leapmotor berada keempat di kalangan jenama kenderaan hijau global — di hadapan hanya pemain tahap seperti BYD, Tesla dan Geely.
Ingatkah anda bagaimana industri menilai Leapmotor beberapa tahun lalu? Pemula, harga separuh Li Auto, pembunuh harga. Sekarang jika disedut balik, label-label itu sebenarnya tidak menepai tumpuan. Apa yang benar-benar dilakukan Leapmotor ialah mencari jalan sendiri: R&D menyeluruh untuk mengawal kos, pengenalan produk yang tepat, saluran yang cepat merentasi pasaran, kemudian kembalikan setiap sen jimat kepada pengguna. Ia tidak mengejar sorakan di medan perang paling sibuk, tetapi setiap langkah di tempat yang tidak banyak diperhati oleh orang lain.
Laporan setengah tahun ini, bernilai untuk dikaji.
Jualan dan Keuntungan, Leapmotor mahu keduanya
Lihat jualan dahulu. 356,487 unit, pengeluar baharu pertama, meningkat 60.8% dari tahun lalu. Nilai sebenarnya prestasi ini, bukan pada angka itu sendiri, tetapi pada strukturnya — bukan disokong oleh produk tunggal, tetapi hasil gabungan keseluruhan matriks produk.
Dari 60,000 hingga 300,000, dari Sedan ke SUV ke MPV, dari elektrik sepenuhnya ke hibrid — Siri A mengekalkan pasaran keperluan dalam 100,000, Siri B menurunkan konfigurasi tinggi seperti cas pantas 800V, kerusi graviti sifar kepada pengguna muda, Siri C menangkapi julat 120,000-180,000 untuk penggunaan keluarga, Siri D menaikkan purata harga ke atas 300,000, membawa jenama ke tahap premium. Dengan menutupi semua harga dan jenis produk secara sistematik ini, dalam kalangan pengeluar baharu, Leapmotor yang pertama.
Tetapi matriks produk hanyalah wajah luar, keupayaan asas sebenar ialah R&D menyeluruh. Dipecahkan, ada tiga logik.
Pertama, komponen utama buatan sendiri. Tiga tenaga, kawalan domain, skema cip pintar semua direka sendiri, setara dengan mengambil margin penyedia itu sendiri. Logik ini ringkas hingga membosankan, tetapi ia sebab utama Leapmotor masih ada margin keuntungan pada tahap 100,000.
Kedua, satu struktur menyokong banyak kereta. Struktur domain terpusat LEAP 4.0 pertama kali di D19, Dual cip Qualcomm 8797, kapsul dan pemanduan satu unit, satu otak mengawal kecerdasan seluruh kereta, kuasa pemprosesan boleh diagihkan secara dinamik antara situasi. Tetapi yang lebih penting, keupayaan ini disalurkan dari atas ke bawah — bantuan pemanduan bandar bandar telah dibuka untuk semua siri ABCD dan Lafa5, suku ketiga akan dihantar ke model LEAP 3.0 untuk panduan bandar seluruh negara.
Diterjemahkan ke bahasa pengguna dalam satu ayat: Kereta 100,000, juga boleh ada pengalaman kecerdasan tahap flagship. Bagi syarikat, pelaburan penyelidikan 231.7 juta Yuan sekali sahaja, dibebankan pada A10 dan D19 sebagai dua buku — kos penyelidikan ditipiskan oleh skala, inilah kawan sebenar margin kasar.
Ketiga, matriks produk melaksanakan "Jaminan Kuantiti + Jaminan Harga" dua garis. C10/C11/C16 mengekalkan dasar 120,000-180,000, Jun jumlah melebihi 30,000, C11 terkumpul terjual 350,000 unit, adalah pokok hijau pasaran kecil; D19 dan D99 menaikkan purata harga, D19 keluar 15 hari tempahan besar melebihi 15,000, kembali menguasai naungan SUV besar bawah 400,000, purata pesanan pertama D99 melebihi 300,000 Yuan. Satu hujung untuk kuantiti, satu hujung untuk harga, struktur margin terangkat secara senyap.
Inilah logik asas yang menjadikan Leapmotor baik tetapi tidak mahal — bukan dengan mengorbankan konfigurasi untuk kos, tetapi dengan R&D mengawal kos, kemudian ubah wang jimat menjadi konfigurasi.
Lihat kembali keuntungan. Keuntungan setengah tahun berturut-turut, margin kasar 11.7%, pendapatan rekod tertinggi — angka ini digabungkan, bermaksud model bisnes Leapmotor telah berjaya. Satu perkara yang paling dipersoalkan bagi pengeluar baharu selama tahun-tahun kebelakangan ini, ialah jualan naik tetapi tidak untung.
Jawapan Leapmotor ialah: Skala, R&D, kecekapan digabungkan, membuat margin kasar positif, kemudian membuat aliran tunai tebal. Dana pegangan 38.59 bilion Yuan, ialah keyakinan ia untuk terus melabur penyelidikan dan globalisasi pada masa hadapan.
Meluas ke luar, Leapmotor bersungguh-sungguh
Jika jualan dan keuntungan adalah jawapan domestik yang Leapmotor berikan setengah tahun ini, maka pasaran luar negara adalah bab kedua yang ditulisnya secara senyap, dan isinya tidak kecil.
Semi tahun pertama hantaran luar 96,294 unit, bertambah secara berterusan, hampir dua ganda. Itali saham pasaran elektrik penuh melebihi satu per empat, terus menduduki puncak jualan elektrik tempatan; Semi tahun pertama di Jerman dalam EV jenama China jualan terkemuka; Di UK dalam retail EV jenama China排第三; Suku kedua masuk Mexico, buka pasaran Amerika Utara. Secara global telah meliputi lebih 45 pasaran antarabangsa, membina lebih 1,000 titik jualan dan servis.
Lebih penting ialah kemajuan pengeluaran tempatan. Di Malaysia, C10 sudah pengeluaran massal, B10 suku ketiga ikut; Di Sepanyol, B10 suku ketiga hasilkan; Di Brazil, kilang Stellantis Goiânia dipilih sebagai pangkasan tempatan.
Ini bukan lagi menjual kereta keluar, tetapi mengakar di luar negara. Kerjasama mendalam dengan Stellantis, menjadikan Leapmotor di luar negara ada saluran sedia ada, kilang dan keupayaan tempatan. Semi tahun pertama jualan luar 96,294 unit prestasi, adalah bukti cara ini berjaya.
Jalan globalisasi Leapmotor, dengan logik pasaran domestiknya sama asas: Tidak mengejar nama paling lantang, cari dahulu posisi "yang belum kompetitif sepenuhnya", kemudian pegang kuat dengan kelebihan kecekapan dan kos. Seperti dulu ia cari ruang dalam pasaran 100,000-200,000, hari ini di pasaran EV harga rendah Eropah, cari posisi sama — di situ sebenarnya kawasan paling sukar cari untung, paling ingin keluar oleh pengeluar kereta tempatan Eropah.
Leapmotor sama saja pindahkan model "Kos + Kecekapan" yang diuji di negara, ke global.
Di akhir laporan setengah tahun masih ada easter egg: Leapmotor akan anjur sidang teknologi tahunan pada September, papar model pemanduan pintar tahap teratas industri dan hasil terkini tiga tenaga. Kisah R&D menyeluruh, masih diteruskan.
Lihat balik setengah tahun ini, apa yang betul dilakukan Leapmotor sebenarnya sangat ringkas: Kos ke sempadan, definisi produk tepat, saluran lengkap, pandangan ke全球。Tiada kata-kata marketing hiasan, tiada perang harga mengejut, hanya langkah demi langkah buat "Baik tetapi tidak mahal" benar.
Keuntungan berterusan, juara jualan pengeluar baharu, global empat teratas — di sebalik pencapaian ini, satu logik sama: Apabila orang lain bergelut di medan sibuk, Leapmotor pilih latih asas ke sempadan, kemudian di setiap laluan yang direndahkan, menangi secara senyap.
Mungkin inilah yang paling bernilai buat industri fikirkan dalam laporan setengah tahun ini.
August 24, Leapmotor revealed its first-half 2026 financial report, presenting a answer showing synergistic growth in scale and efficiency: Operating revenue of 38.11 billion yuan, a year-on-year increase of 57.2%, setting a new historical record for the same period; Net profit of 210 million yuan, achieving profitability for three consecutive half-years. Sales also achieved steady growth, with global cumulative sales reaching 356,500 units in the first half, a year-on-year increase of 60.8%.
However, impressive performance is just the starting point of Leapmotor's new development journey. With continuous volume increase in new models, continuous breakthroughs in R&D technology, and steady progress in overseas localization production, Leapmotor's growth curve in the second half of the year is expected to continue rising, striving hard to achieve the million annual sales target.

Breakthroughs on Both Scale and Profitability Lines, Operating Quality Improves Quarter by Quarter
Financial reports show that in the first half of 2026, Leapmotor's operating revenue grew significantly year-on-year, and net profit maintained a profitable trend, having achieved profitability for three consecutive half-years, demonstrating a solid operational foundation. In the environment where new automotive manufacturers are generally struggling to seek profitability, Leapmotor is the only car company to have been profitable for the most recent three consecutive half-years, becoming a scarce sample of continuous profitability among new forces. At the same time, Leapmotor's gross margin for the second quarter increased quarter-on-quarter to 12.6%, showing a trend of improving operating quality quarter by quarter. As of the end of the reporting period, Leapmotor's available funds reached 38.59 billion yuan, and sufficient capital reserves safeguard the company's long-term development.
In terms of sales, Leapmotor's global cumulative sales reached 356,500 units in the first half of the year, a year-on-year increase of 60.8%. In July this year, its sales hit a new high, reaching 101,000 units, a year-on-year increase of 102%, becoming the first domestic new force brand to break through 100,000 units in single-month deliveries, ranking at the forefront of the new energy vehicle industry as a whole. Among the comparable terminal registration quantities for the first 5 months of this year for which data has been released, Leapmotor ranked fourth among global new energy passenger car brands.

Obviously, Leapmotor's current financial performance is robust, and sales continue to climb, which not only dilutes R&D and manufacturing costs but also jointly builds a solid foundation for scale expansion in the second half of the year.
Full Matrix Synergy Drives Volume Increase, Multi-Level Drive Accelerates Sprint to Million Annual Sales
Behind the excellent performance, it is inseparable from Leapmotor's important measures to continuously expand market coverage and layout sub-segments. Currently, Leapmotor has completed the full price band layout of the ABCD four major product matrices, comprehensively covering the mainstream price range from 60,000 yuan to 300,000 yuan, including:
The A series takes "fine small cars" as the strategic main line. The representative model A10 welcomed the 100,000th mass-produced vehicle off the line 135 days after launch, and ranked first in Chinese brand SUV sales for three consecutive months, becoming a phenomenon-level product for mainstream home pure electric SUVs. The A05 launched in August further completes the entry market puzzle and is an important key driver for achieving the annual sales target.

The two new models B01 and B10 of the B series officially launched in July adhere to the concept of technology inclusiveness. Priced at the 100,000 yuan level, they are equipped with high-end configurations such as global 800V, 3C fast charging, and dual zero-gravity front seats, directly addressing pain points in the 100,000 yuan pure electric market, such as configuration compromises, range shortages, and smart technology shrinkage.

The base users of the C series have already surpassed 850,000. After the three facelifted models C10, C11, and C16 completed their new launch, June sales exceeded 30,000 units, continuously solidifying the brand's scale foundation.
The D series with higher positioning continues to break upwards. D19 has steadily entered the ranks of monthly sales of 10,000 units, and D99's launch average price has surpassed 300,000 yuan, forming a dual flagship matrix of SUV and MPV, promoting the continuous upward movement of Leapmotor brand value and establishing a high-end benchmark for the brand.
Plus the exclusive sports coupe product line Lafa 5 series, Leapmotor's product matrix is becoming increasingly complete, forming a multi-level drive growth pattern. Each series model has clear division of labor and collaborative effort, providing sufficient support for sales growth in the third and fourth quarters. Leapmotor's annual million sales target is accelerating into the channel of realization.
Technology and Globalization Advance on Two Lines, Leapmotor Has Abundant Long-Term Development Momentum
Leapmotor has always maintained high-intensity investment in technology R&D, and the advantages of full-domain self-research are increasingly prominent. Currently, urban pilot-assisted driving covers all Leapmotor ABCD series models. In the third quarter of 2026, Leapmotor LEAP 3.0 architecture models will receive the nationwide urban pilot-assisted driving push. More significantly, Leapmotor will hold the 2026 annual technology launch event in September, at which time it will launch an intelligent assisted driving world model reaching the industry's first tier level, and bring a series of all-new technological achievements in the three-electric field. Continuously iterated intelligent technology will continuously improve the competitiveness of all Leapmotor products and promote further expansion of Leapmotor's market in the second half of the year.

At the same time, the overseas market has become the second growth curve that cannot be ignored for Leapmotor. In the first half of this year, Leapmotor cumulative exports reached 96,000 units, a year-on-year increase of 372.6%, exceeding the total export volume for the entire year of 2025, with the proportion of total sales rising to 27%. Since the fourth quarter of 2024, Leapmotor's cumulative exports have been about 200,000 units. In core European markets, Leapmotor occupies a leading position in the Italian pure electric market and took the championship of Chinese electric vehicle brand sales in the German market in June. On the channel side, Leapmotor International has already established over 1,000 sales and after-sales service outlets in more than 45 international markets.
Localization production layout is also accelerating. The Malaysia factory C10 has already achieved mass production, and B10 is planned to start production in the third quarter; The Zaragoza factory in Spain has completed renovation, and B10 is expected to start production in the third quarter; The South American Brazil factory has confirmed the site selection, planning to enter mass production in the second half of 2027. Leapmotor's globalization has gradually shifted from complete vehicle exports to local manufacturing, which can effectively reduce cross-border delivery costs and expand long-term growth space.

Relying on continuously realized profitability, a perfect product matrix covering mainstream markets, rapidly scaling global business, and heavy technology results that are about to land, Leapmotor has built a complete and sustainable growth system with abundant long-term development momentum. Looking forward to the second half of the year, Leapmotor is expected to continue the upward trend and steadily move towards the million annual sales target.
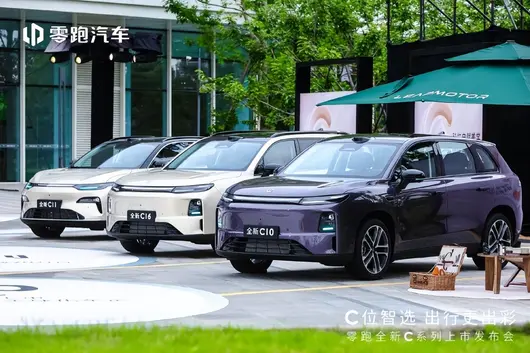
24 Ogos, Automotif Leapmotor mendedahkan laporan kewangan semi-tahunan 2026, mengemukakan satu laporan pertumbuhan serasi skala dan keuntungan: Pendapatan 38.11 bilion Yuan, meningkat 57.2% berbanding tahun sebelumnya, menetapkan rekod sejarah tempoh yang sama; Keuntungan bersih 2.1 bilion Yuan, keuntungan selama tiga sesi semi-tahunan berturut-turut. Dari segi jualan, juga mencapai pertumbuhan mantap, kumulatif jualan global selama 6 bulan pertama mencapai 356,500 unit, meningkat 60.8% berbanding tahun sebelumnya.
Walau bagaimanapun, prestasi yang cemerlang hanyalah titik permulaan perjalanan baharu Leapmotor. Dengan peningkatan kuantiti model baharu yang berterusan, penyusutan teknologi penyelidikan berterusan, dan pengeluaran tempatan luar negara yang berjalan lancar, lengkung pertumbuhan Leapmotor pada semi-tahun kedua dijangka terus meningkat, dengan penuh tenaga menuju sasaran jualan tahunan satu juta.
Pecahan Ganda Dalam Skala Dan Keuntungan, Kualiti Operasi Semakin Baik Setiap Suku
Laporan kewangan menunjukkan, pada semi-tahun pertama 2026, pendapatan Automotif Leapmotor meningkat secara besar-besaran berbanding tahun sebelumnya, keuntungan bersih terus mengekalkan trend keuntungan, sudah tiga sesi semi-tahunan berturut-turut mencapai keuntungan, mempamerkan fokus operasi yang mantap. Dalam persekitaran pembuat kereta baharu yang umum mencari keuntungan dengan susah payah, Automotif Leapmotor adalah satu-satunya syarikat automotif yang baru-baru ini tiga sesi semi-tahunan berturut-turut mencapai keuntungan, menjadi contoh keberlanjutan keuntungan yang langka dalam kalangan pembuat baharu. Pada masa yang sama, margin keuntungan kasar Automotif Leapmotor pada suku kedua meningkat secara siri kepada 12.6%, kualiti operasi menunjukkan trend penambahbaikan setiap suku. Pada masa hujung laporan, modal terkumpul Automotif Leapmotor mencapai 38.59 bilion Yuan, simpanan modal yang cukup menjamin perkembangan jangka panjang syarikat.
Dari segi jualan, kumulatif jualan global Automotif Leapmotor pada semi-tahun pertama 356,500 unit, meningkat 60.8% berbanding tahun sebelumnya, bulan Julai tahun ini, jualan lagi mencatatkan tinggi baru, mencapai 101,000 unit, meningkat 102%, menjadi jenama automotif baharu pertama di China yang jualan penghantaran satu bulan melebihi 100,000 unit, menempati barisan hadapan seluruh industri kereta penumpang tenaga baharu. Dalam jumlah pendaftaran hujung 5 bulan pertama tahun ini yang data yang dinyatakan, Leapmotor terletak keempat dalam kalangan jenama kereta penumpang tenaga baharu global.
Jelas, prestasi kewangan Automotif Leapmotor semasa ini mantap, jualan terus meningkat, ini bukan sahaja mengurangkan kos penyelidikan dan pembuatan, malah akan bersama-sama membina asas kukuh bagi pengembangan skala semi-tahun kedua.
Pembebasan Sinergi Seluruh Matriks, Pemacu Pelbagai Tahap Mempercepatkan Pecutan Sasaran Jualan Tahunan Satu Juta
Di sebalik prestasi cemerlang yang dicapai, tidak terpisahkan daripada langkah-langkah penting Automotif Leapmotor yang berterusan memperluas cakupan pasaran dan menyusun pasaran berspesifik. Kini, Automotif Leapmotor sudah siap menyusun penyusunan penuh julat harga empat matriks produk ABCD, merangkumi sepenuhnya julat harga utama 60,000 hingga 300,000 Yuan, di antaranya:
Siri A dengan "kereta kecil premium" sebagai garis strategi utama, model wakil A10 135 hari selepas dilancarkan sudah mencapai unit ke-100,000 tamat pengeluaran, dan meraih jualan SUV jenama China pertama selama tiga bulan berturut-turut, menjadi produk fenomena SUV elektrik rumah tangga utama, A05 yang dilancarkan pada Ogos lebih menyempurnakan puzzle pasaran pemula, adalah alat penting untuk mencapai sasaran jualan tahunan.
Siri B pada Julai dilancarkan rasmi dua model baharu sepenuhnya B01, B10, memegang falsafah teknologi yang bermanfaat untuk semua, dengan harga pada tahap 100,000 Yuan memuatkan 800V, pengisian pantas 3C, kerusi graviti nol ganda barisan depan dan lain-lain spesifikasi premium, menembusi masalah utama pasaran elektrik tahap 100,000 Yuan, seperti kompromi spesifikasi, kelemahan jarak lintasan, pengurangan kecerdasan dan lain-lain.
Pengguna asas Siri C sudah mencapai lebih 850,000, tiga model penambahbaikan sepenuhnya C10, C11, C16 selepas dilancarkan semula, jualan Jun melebihi 30,000 unit, terus memperkukuh asas skala jenama.
Siri D dengan penetapan lebih tinggi terus mencapai ketinggian, D19 dengan stabil memasuki kumpulan jualan bulanan 10,000 unit, D99 harga purata dilancarkan melebihi 300,000 Yuan, membentuk matriks dua model utama SUV dan MPV, mendorong nilai jenama Leapmotor terus meningkat, membentuk piawaian premium jenama.
Ditambah garis produk kereta lari sukan khusus Lafa 5, matriks produk Automotif Leapmotor semakin lengkap, membentuk corak pertumbuhan dengan pemacu pelbagai peringkat, setiap siri model peranan jelas, bekerjasama memecahkan masalah, memberikan sokongan mencukupi bagi pertumbuhan jualan suku ketiga dan keempat, sasaran jualan tahunan satu juta Automotif Leapmotor sedang memasuki saluran pemenuhan.
Teknologi Dan Globalisasi Jalan Selari, Tenaga Perkembangan Jangka Panjang Leapmotor Berlimpah
Leapmotor pada sisi penyelidikan dan pembangunan teknologi sentiasa mengekalkan pelaburan intensiti tinggi, keunggulan penyelidikan sendiri sepenuh skala semakin muncul. Kini, panduan bandar bantuan pemanduan sudah merangkumi semua model ABCD Leapmotor, pada suku ketiga 2026, model lengan LEAP3.0 akan menerima penghantaran panduan bandar bantuan pemanduan seluruh negara. Lebih bermakna secara simbolik adalah, Leapmotor akan menyelenggarakan konferensi teknologi tahunan 2026 pada September, semasa itu akan melancarkan model pemanduan bantuan pintar bertaraf dunia setaraf gred pertama industri, dan membawa Siri hasil teknologi baharu sepenuhnya dalam bidang sistem kuasa utama. Teknologi pintar pembaruan berterusan, akan terus meningkatkan kekuatan bersaing produk semua Siri Automotif Leapmotor, mendorong pengembangan pasaran Leapmotor semi-tahun kedua lebih lanjut.
Pada masa yang sama, pasaran luar negara sudah menjadi lengkung pertumbuhan kedua Leapmotor yang tidak boleh diabaikan, semi-tahun pertama tahun ini, Eksport Kumulatif Leapmotor 96,000 unit, meningkat 372.6% berbanding tahun sebelumnya, melebihi jumlah eksport keseluruhan seluruh tahun 2025, peratusan dalam jualan keseluruhan dinaikkan ke 27%. Sejak suku keempat 2024, Eksport Kumulatif Leapmotor kira-kira 200,000 unit. Di pasaran teras Eropah, Leapmotor menempati kedudukan terdepan dalam pasaran elektrik Itali, dan meraih juara jualan jenama kereta elektrik China dalam pasaran Jerman pada Jun. Dari sisi saluran, Leapmotor Antarabangsa sudah menyusun di lebih 45 pasaran antarabangsa lebih 1,000 pusat jualan dan perkhidmatan selepas jualan.
Penyusunan pengeluaran tempatan serentak meningkatkan kelajuan. Pabrik Malaysia C10 sudah mencapai pengeluaran berskala, rancangan B10 memasuki pengeluaran suku ketiga; Pengubahsuaian Pabrik Zaragoza Sepanyol selesai, B10 dijangkan memasuki pengeluaran suku ketiga; Pilihan Lokasi Pabrik Brazil Amerika Selatan ditentukan, rancangan memasuki pengeluaran berskala setengah tahun kedua 2027. Globalisasi Leapmotor, sudah secara perlahan beralih dari eksport kereta lengkap ke pembuatan tempatan, ini dapat secara berkesan menurunkan kos penghantaran silang sempadan, meluaskan ruang pertumbuhan jangka panjang.
Bergantung kepada prestasi keuntungan yang terus dicapai, matriks produk lengkap yang merangkumi pasaran utama, perniagaan global yang pantas mula naik, dan hasil teknologi penting yang akan diterapkan, Leapmotor sudah membina sistem pertumbuhan yang lengkap dan lestari, tenaga perkembangan jangka panjang berlimpah. Melihat ke arah semi-tahun kedua, Leapmotor berharap berterusan trend naik, menuju sasaran jualan tahunan satu juta dengan mantap.
Mid-August, Leapmotor released H1 2026 financial performance. Revenue 38.11 billion, YoY up 57.2%, Net Profit 210 million, YoY up 530%. For the first time achieved semi-annual profitability, on the surface looks like a beautiful report card. But capital market reaction was flat, stock price didn't move much. Why? Because industry insiders are all looking at another number — Gross Margin 11.7%, down 2.4 percentage points YoY. Made money, but not much, and the way of making money is a bit forced. Today let's open up Leapmotor's accounts to see, alongside Li Auto, Nio, Xpeng do a horizontal comparison, see exactly how is this 210 million's profit quality.

38.1 Billion Revenue Breakdown, Q1 Crash Q2 Recovery
First half 38.1 billion revenue, growth rate indeed bright, but breaking down shows huge gap between two quarters. Q1 revenue only 10.8 billion, net loss 390 million, gross margin only 9.4%, at that time outsiders once questioned if Leapmotor fell into a vicious cycle of "selling more losing more". Q2 suddenly turned around, revenue 27.29 billion, QoQ growth over 150%, single quarter net profit 600 million, gross margin rebounded to 12.6%. The problem is Q2 explosion mainly relied on volume pull of C16 and C10 two models, especially C16 this 150,000 class six-seat SUV directly sold explosively. But Leapmotor average selling price only around 110,000, bottoming among new EV makers. Same profit volume, Nio sells one equals Leapmotor sells nearly two, this is Leapmotor's core contradiction: sales went up, but single car profitability is weak. And first half overall gross margin 11.7% still 2.4 percentage points lower than last year, shows price promotion cost is showing.

210 Million Net Profit Quality, Horizontal Comparison of Four Companies
Put Leapmotor, Nio, Xpeng, Li Auto four new EV makers first half profit levels together look, very clear. Leapmotor first half net profit 210 million, only one profitable, but don't rush to clap — 210 million divided by 356,500 delivery volume, single car profit only around 590 yuan. Look at other three: Nio although still loss, but single car average price over 200,000, auto gross margin 19% (Q1), selling one loss amount also narrowing; Xpeng first half net loss 3.12 billion, but comprehensive gross margin 20.7%, auto gross margin 12.1%, key is service business contributed nearly half gross profit, profit margin as high as 75.1%, shows Xpeng found money making way outside selling cars; Li Auto most tragic, vehicle gross margin directly dropped to 6.1%, H1 net loss 2.29 billion, pure EV transformation pain much more violent than expected, i6 accounts for sales 62% but L Series completely crashed. Leapmotor is the only one making money among four for sure, but this profit quality, to be honest not high. Annual profit expectation already down from 5 billion to 3 billion, gross margin goal also from 13—14% lowered, management in earnings call said price reduction is active choice, to grab 100,000-150,000 class market share, but this price interval profit space originally thin as blade.

Going Overseas 96,000 Units, Is the Biggest Variable
Leapmotor first half another number worth attention is export 96,300 units, YoY up 372.6%, accounts for all delivery 27%. This proportion in new EV makers leads far. Leapmotor going overseas biggest backer is Stellantis Group cooperation, directly borrow its global channels, 45 overseas markets, over 1000 sales outlets, not paving from scratch. In Southeast Asia, South America, Europe etc markets, Leapmotor price advantage more obvious than domestic. And Leapmotor promoting Malaysia, Spain, Brazil three places localization production, avoiding tariff risk. Overseas car pricing usually higher than domestic by 30—50%, this means overseas profit contribution far exceeds sales proportion. If saying going abroad is Leapmotor biggest variable, then Stellantis is that leverage.

60.8 Billion Market Cap, Is It Expensive?
Leapmotor current market cap 60.8 billion HKD, TTM PE ratio over 70 times. Zhu Jiangming said Leapmotor worth at least 200 billion, but from financial view, according to 3 billion annual profit expectation, 70 times PE close to Tesla level — they have FSD and Robotaxi stories supporting, Leapmotor currently still relies on selling cars. From PS view, 60.8 billion HKD approximates 55 billion RMB, corresponding annual revenue about 76 billion, PS about 0.7 times, in new EV makers not expensive. Nio PS about 1.2 times, Xpeng about 1.5 times. So Leapmotor valuation logic is divergent: by profit looks expensive, by revenue scale has space. Key is see H2 C16 volume momentum can continue, and going overseas can keep each quarter 50,000 units growth rate. If can stabilize, profit elasticity still has large release space.
Summary: Leapmotor used half a year time proved low price strategy can swap for scale, but 210 million net profit also shows scale does not equal profit. Among four new EV makers, Leapmotor is only making money, but earning most hard. H2 real test is can scale advantage turn into profit advantage — going overseas growth rate and gross margin can rise synchronously, this will decide Leapmotor position in next elimination round.
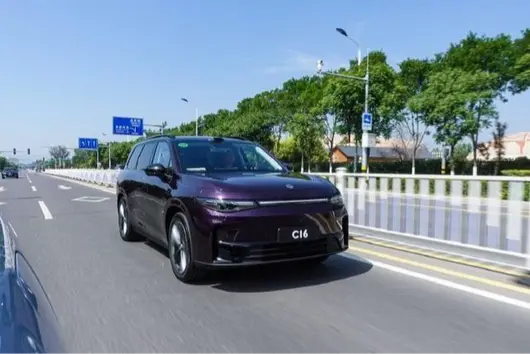
Pertengahan Ogos, Leapmotor telah mengumumkan prestasi separuh tahun 2026, pendapatan 38.11 bilion, peningkatan tahun-ke-tahun 57.2%, keuntungan bersih 210 juta, peningkatan tahun-ke-tahun 530%. Untuk pertama kali, keuntungan separuh tahun direalisasikan, kelihatan seperti rekod yang bagus di permukaan. Tetapi reaksi pasaran modal tenang, harga saham tidak banyak berubah. Mengapa? Kerana mereka yang berpengalaman melihat nombor lain—margin kasar 11.7%, menurun 2.4 peratus titik dari tahun lalu. Ada untung, tetapi tidak banyak, dan cara mendapatkannya agak dipaksa. Hari ini kita akan bedah akaun Leapmotor, serta buat perbandingan mendatar dengan Li Auto, NIO, dan XPeng, melihat sejauh mana kualiti 210 juta ini.
Bedah Pendapatan 38.1 Bilion, Q1 Gagal Q2 Pulih
Pendapatan 38.1 bilion separuh tahun, kadar pertumbuhan memang cemerlang, tetapi jika dipecahkan, jurang antara dua suku tahun sangat besar. Pendapatan Q1 hanya 10.8 bilion, rugi bersih 390 juta, margin kasar hanya 9.4%, pada masa itu pihak luar sekali lagi mempertikai sama ada Leapmotor terperangkap dalam kitaran negatif "semakin jualan semakin rugi". Q2 tiba-tiba berpusing semula, pendapatan 27.29 bilion, pertumbuhan berangka kuartal lebih 150%, keuntungan bersih kuartal tunggal 600 juta, margin kasar kembali ke 12.6%. Masalahnya letak letak ledakan Q2 bergantung kepada peningkatan jualan dua model C16 dan C10, terutamanya C16, SUV enam tempat duduk kelas 150,000 yang terus meledak. Tetapi harga purata Leapmotor hanya sekitar 110,000, terbawah dalam kalangan pemain baharu. Untuk skala keuntungan yang sama, NIO menjual satu unit sama dengan hampir dua unit Leapmotor, ini adalah kontradiksi utama Leapmotor: jualan naik, tetapi keupayaan keuntungan setiap kenderaan lemah. Selain itu margin kasar keseluruhan separuh tahun 11.7% masih 2.4 peratus titik lebih rendah dari tahun lalu, menunjukkan kos promosi harga sedang mula kelihatan.
Kualiti Keuntungan Bersih 210 Juta, Perbandingan Empat Pihak Secara Mendatar
Jika dilihat bersama tahap keuntungan empat pemain baharu ini, Leapmotor, NIO, XPeng, Li Auto pada separuh tahun, ia menjadi jelas. Keuntungan bersih Leapmotor separuh tahun 210 juta, satu-satunya yang untung, tetapi jangan segera tepuk tangan—210 juta dibahagi dengan penghantaran 356,500 kenderaan, keuntungan per kenderaan hanya sekitar 590 yuan. Lihat tiga lagi: NIO walaupun masih rugi, harga purata per kenderaan melebihi 200,000, margin kasar kereta 19% (Q1), jumlah kerugian per unit juga mengecil; XPeng separuh tahun rugi bersih 3.12 bilion, tetapi margin kasar keseluruhan 20.7%, margin kasar kereta 12.1%, yang penting perkhidmatan menyumbang hampir separuh margin kasar, nisbah keuntungan sehingga 75.1%, menunjukkan XPeng telah menemui jalan cari wang selain menjual kereta; Li Auto paling malang, margin kasar kenderaan terus jatuh ke 6.1%, H1 rugi bersih 2.29 bilion, kesakitan transformasi elektrik tulen lebih teruk dari jangkaan, i6 menguasai 62% jualan tetapi siri L jatuh merosot. Benar Leapmotor satu-satunya yang untung dalam empat ini, tetapi kualiti keuntungan ini, jujur tidak tinggi. Jangkaan keuntungan tahunan telah diturunkan dari 5 bilion kepada 3 bilion, sasaran margin kasar juga diturunkan dari 13—14%, pengurusan dalam mesyuarat prestasi berkata penurunan harga adalah pilihan aktif, untuk rebut pasaran kelas 100,000-150,000, tetapi ruang keuntungan dalam julat harga ini memang nipis seperti pisau.
Ekspor 96,000 Kenderaan, Merupakan Pemboleh Ubah Terbesar
Nombor lain yang perlu dipantau separuh tahun Leapmotor ialah ekspor 96,300 kenderaan, peningkatan tahun-ke-tahun 372.6%, mewakili 27% daripada jumlah penghantaran. Nisbah ini mendahului pemain baharu lain. Penyandaran terbesar Leapmotor ke luar negara ialah kerjasama dengan kumpulan Stellantis, terus memuatkan saluran globalnya, 45 pasaran antarabangsa, lebih 1,000 titik jualan, bukan dibina dari sifar. Di pasaran Asia Tenggara, Amerika Selatan, Eropah, kelebihan harga Leapmotor lebih ketara berbanding domestik. Leapmotor juga sedang memajukan pengeluaran tempatan di tiga lokasi Malaysia, Sepanyol, Brazil, mengelak risiko tarif. Harga model eksport biasanya 30—50% lebih tinggi dari domestik, ini bermakna sumbangan keuntungan luar negara jauh melebihi nisbah jualan. Jika keluar negara adalah pemboleh ubah terbesar Leapmotor, maka Stellantis adalah tuil itu.
Nilai Pasaran 6.08 Bilion, Mahal Tidak?
Nilai pasaran semasa Leapmotor 6.08 bilion dolar Hong Kong, nisbah P/E TTM melebihi 70 kali. Zhu Jiangming kata Leapmotor sekurang-kurangnya bernilai 20 bilion, tetapi dari sudut kewangan, mengikut jangkaan keuntungan tahunan 3 bilion, 70 kali ganda PE hampir dengan tahap Tesla—mereka mempunyai cerita FSD dan Robotaxi menyokong, Leapmotor kini masih bergantung pada jualan kereta. Dari segi PS, 6.08 bilion dolar Hong Kong dianggarkan kira-kira 5.5 bilion yuan, sepadan pendapatan tahunan kira-kira 7.6 bilion, PS kira-kira 0.7 kali ganda, tidak mahal dalam kalangan pemain baharu. PS NIO kira-kira 1.2 kali ganda, XPeng kira-kira 1.5 kali ganda. Maka logik penilaian Leapmotor adalah bercanggah: dilihat keuntungan agak mahal, dilihat skala pendapatan masih ada ruang. Penting untuk melihat sama ada momentum jualan C16 separuh tahun boleh diteruskan, dan sama ada ekspor boleh mengekalkan kadar pertumbuhan melebihi 50,000 kenderaan setiap kuartal. Jika boleh stabil, ruang pelepasan keuntungan masih besar.
Ringkasan: Leapmotor dalam setengah masa membuktikan strategi harga rendah boleh tukar skala, tetapi 210 juta keuntungan bersih juga menunjukkan skala tidak sama dengan keuntungan. Dalam empat pemain baharu, Leapmotor satu-satunya yang untung, tetapi paling sukar. Ujian sebenar separuh tahun adalah sama ada boleh ubah kelebihan skala kepada kelebihan keuntungan—sama ada kadar pertumbuhan ekspor dan margin kasar boleh naik serentak, ini akan menentukan kedudukan Leapmotor dalam pusingan eliman seterusnya.

After monthly deliveries broke 100,000 units, what does Leapmotor need to think about next:
How to convert sales volume into higher profits?
On August 24, Leapmotor released mid-year results for 2026, and the results were very outstanding. During the reporting period, the company achieved revenue of 38.11 billion yuan, a 57.2% year-on-year increase; net profit attributable to the Company's equity holders was 210 million yuan, marking three consecutive semi-annual profits. However, affected by rising raw material prices, changes in product mix, and other factors, the Company's gross margin in the first half of the year fell to 11.7%, a decrease of 2.4 percentage points compared to the same period last year.

In the earnings call, several pieces of information revealed by Leapmotor management are worth noting: The Company's expected full-year net profit was lowered from approximately 5 billion yuan at the beginning of the year to about 3 billion yuan; the full-year overall gross margin is expected to be 13% to 14%, with a gross margin for vehicle sales of approximately 10% to 11%; the overseas sales target for 2027 is 350,000–400,000 vehicles.
In addition, company executives revealed that the Company has clear plans for the embodied robotics business and will officially release related information subsequently.
01
Significant Sales Breakthrough
In the first half of 2026, Leapmotor deliveries reached 356,487 vehicles, a 60.8% year-on-year increase, ranking first in sales among new EV brands in China. After entering the second half of the year, the growth momentum accelerated further: July monthly deliveries were 101,267 vehicles, a 102% year-on-year increase, exceeding 100,000 units for the first time.

Leapmotor has currently completed its layout of the A, B, C, and D four-series product matrix, covering the mainstream price range of 60,000 yuan to 300,000 yuan. The A series undertakes volume sales tasks, the B and C series form the core sales base, and the D series undertakes brand premiuming and profit improvement functions.
Among them, the A10 went on the market and achieved the roll-off of the 100,000th mass-produced vehicle in 135 days; from May to July 2026, it ranked first in sales of Chinese Brand SUVs for three consecutive months; the D19 quickly broke through monthly sales of 10,000 units after launch, with July deliveries of 10,043 vehicles; C series facelift models exceeded 30,000 vehicles in sales in June, and the cumulative user base of the C series has exceeded 850,000.
From the perspective of product structure, Leapmotor has formed portfolio growth through different price segments and vehicle classes. This model helps reduce the volatility risk of a single vehicle model, and is also beneficial for spreading R&D, manufacturing, channel, and supply chain costs.
However, scale does not necessarily equal profit. Leapmotor's gross margin in the first half of the year fell from 14.1% to 11.7%, mainly due to raw material price fluctuations.
02
Gross Margin Decline, Full-year Profit Target Lowered
Leapmotor's significant growth in sales and revenue resulted in a decline in gross margin per vehicle.
Specifically, Leapmotor's gross profit in the first half of the year was 4.45 billion yuan, a 29.7% year-on-year increase, but the gross margin fell to 11.7%, a decrease of 2.4 percentage points compared to the same period last year.
Of course, the reason for the decline in gross margin per vehicle lies in raw material fluctuations.

At the same time, in terms of the full-year outlook, Leapmotor's expectations have been adjusted downwards. Management stated that achieving the full-year net profit target of approximately 5 billion yuan formulated at the beginning of the year will be difficult, and the current expected full-year net profit is about 3 billion yuan, with an overall gross margin expected to be 13%–14% and a vehicle sales gross margin of approximately 10%–11%.
Management judges that major raw material prices in the second half of the year, especially lithium carbonate prices, are expected to remain relatively stable; as sales increase, material procurement, manufacturing expenses, and fixed cost amortization will be further optimized, thereby promoting sequential gross margin improvements.
03
Going Overseas Prioritizes "Grabbing Share" Over Profit in Short Term
The overseas business is the segment with denser information released at this earnings meeting.
Data shows overseas growth is quite outstanding. In the first half of 2026, Leapmotor's exports reached 96,294 vehicles, a 372.6% year-on-year increase, accounting for 27% of total sales in the first half of the year. Cumulative exports from January to July 2026 were 113,863 vehicles, completing 75.9% of the annual challenge target. The Company expects full-year overseas sales to reach 200,000 vehicles.
For next year, Leapmotor management is also very optimistic, giving a sales expectation of 350,000–400,000 vehicles, with the target nearly doubling the estimated completion volume for 2026. In terms of regional structure, Europe will still be the largest market, while the share of markets such as South America, Southeast Asia, and Australia will further increase.
However, overseas sales growth and overseas profitability are not fully synchronized.
Management stated that this is because during the initial stage of the cooperation, the gross margin level for Leapmotor selling vehicles to Leapmotor International was agreed to be low, and the priority goal for the first three years was to rapidly expand the market and increase sales. Currently, Leapmotor International achieved profitability in 2025, but experienced a slight loss in the first half of 2026 due to operational factors; the Company expects to make up for losses in the second half of the year through operational adjustments to achieve stable annual profitability.

Leapmotor's overseas strategy remains "scale first, profit later".
For Leapmotor, Stellantis provides three important supports:
First, local channel resources, helping Leapmotor quickly enter Europe, South America, and other markets;
Second, manufacturing capability, reducing capital expenditure and time costs for building overseas local factories;
Third, supply chain and logistics resources, which are beneficial for alleviating ocean freight and local parts procurement pressure.
However, local production does not naturally mean a significant increase in profit margins. Management admitted that overseas local production can optimize tariff costs, but local parts procurement prices are higher than in China, so there is a need to rebalance between tariff savings and increased procurement costs, therefore the gross margin improvement brought by localization is not as obvious as the market imagines.
Leapmotor is promoting overseas localization production, mainly in Malaysia, Spain, and Brazil.
Regarding the Malaysia project, the C10 has completed SOP and entered the formal mass production stage, and the B10 is planned for mass production and launch in the third quarter of 2026.
Regarding the Spain Zaragoza project, factory supporting renovations have been completed; the B10 is expected to go into production in the third quarter of 2026, the B05 is planned for trial production within the year and formal mass production in 2027, and the supporting battery factory is also expected to start mass production in the third quarter.
Regarding South America, the Company has selected the Goiânia factory in Brazil as the localized assembly base, and the B10 is planned to go into production in the second half of 2027.
From the project progress, it can also be seen that the proportion of local production in the 2027 overseas sales target is not high. Management expects, the main model for overseas local production in 2027 will be the B10, with a production volume of about 50,000 vehicles, which will be flexibly increased subsequently based on policy changes and cooperation refinement progress.
Leapmotor has proved that it can sell cars well and has gained recognition in both domestic and overseas markets. Next, the Company needs to answer: while overseas sales grow rapidly, can it truly convert scale into stable and sustainable profits.
Selepas penghantaran bulanan melampaui 100,000 kenderaan, apakah yang perlu dipikirkan Leapmotor seterusnya:
Bagaimana menukar jualan kepada keuntungan yang lebih tinggi?
Pada 24 Ogos, Leapmotor Automobile melaporkan prestasi separuh tahun 2026, keputusan tersebut sangat cemerlang. Dalam tempoh laporan, syarikat menjana pendapatan 38.11 bilion yuan, meningkat 57.2% berbanding tahun lalu; keuntungan bersih pemegang ekuiti syarikat ialah 210 juta yuan, mencatat keuntungan untuk tiga setengah tahun berturut-turut. Walau bagaimanapun, terjejas oleh faktor seperti kenaikan harga bahan mentah dan perubahan struktur produk, margin kasar syarikat pada separuh tahun pertama menurun kepada 11.7%, turun 2.4 peratus berbanding tahun sebelumnya.
Dalam persidangan telefon prestasi, beberapa maklumat yang didedahkan oleh pengurusan Leapmotor menarik perhatian: jangkaan keuntungan bersih tahunan syarikat diturunkan daripada kira-kira 5 bilion yuan pada awal tahun kepada kira-kira 3 bilion yuan, margin kasar keseluruhan sepanjang tahun dijangka 13% hingga 14%, margin kasar jualan kenderaan lengkap kira-kira 10% hingga 11%; sasaran jualan luar negara 2027 ialah 350,000 hingga 400,000 unit.
Tambahan lagi, eksekutif syarikat juga mendedahkan bahawa syarikat telah mempunyai pelan yang jelas untuk perniagaan robot somatik, dan maklumat berkaitan akan dikeluarkan secara rasmi pada masa hadapan.
01
Lompatan besar dalam jualan
Sepada tahun pertama 2026, penghantaran kenderaan Leapmotor Automobile mencapai 356,487 unit, meningkat 60.8% tahun ke tahun, mendahului jualan jenama baharu China. Memasuki separuh tahun kedua, laju pertumbuhan semakin dipercepat: penghantaran tunggal Julai 101,267 unit, meningkat 102% tahun ke tahun, pertama kali melepasi 100,000 unit.
Leapmotor kini telah melengkapkan susun atur empat matriks produk utama A, B, C, D, meliputi julat harga utama 60,000 yuan hingga 300,000 yuan. Siri A menanggung tugas jualan volume, Siri B dan C membentuk asas jualan, Siri D menanggung fungsi peningkatan jenama dan penambahbaikan keuntungan.
Antaranya, A10 setelah 135 hari dilancarkan telah mencapai pengeluaran 100,000 unit kereta pengeluaran massal, Mei hingga Julai 2026 menduduki tempat pertama dalam jualan SUV jenama China selama tiga bulan berturut-turut; D19 dengan pantas melepasi jualan bulanan 10,000 unit selepas dilancarkan, penghantaran Julai 10,043 unit; model kemas kini Siri C pada Jun melebihi 30,000 unit jualan, pangkalan pengguna kumulatif Siri C telah melebihi 850,000.
Dari segi struktur produk, Leapmotor membentuk pertumbuhan berombak melalui julat harga berbeza dan tahap model berbeza. Model ini membantu mengurangkan risiko perubahan model tunggal, dan juga membantu mengurangkan kos penyelidikan dan pembangunan, pembuatan, saluran dan rantaian bekalan.
Walau bagaimanapun, skala tidak semestinya sama dengan keuntungan. Margin kasar Leapmotor separuh tahun pertama menurun daripada 14.1% kepada 11.7%, punca utama adalah disebabkan oleh fluktuasi harga bahan mentah.
02
Margin kasar menurun, sasaran keuntungan tahunan diturunkan
Pertumbuhan besar dalam jualan dan pendapatan Leapmotor, margin kasar setiap kenderaan sebaliknya telah menurun.
Secara khusus, margin kasar Leapmotor separuh tahun ialah 4.45 bilion yuan, meningkat 29.7% tahun ke tahun, tetapi margin kasar menurun kepada 11.7%, turun 2.4 peratus berbanding tahun yang sama tahun lalu.
Sememangnya, sebab margin kasar setiap kenderaan menurun adalah disebabkan oleh fluktuasi bahan mentah.
Serentak itu, dalam aspek prospek tahunan, jangkaan Leapmotor telah disesuaikan semula. Pengurusan menyatakan, sasaran keuntungan bersih tahunan kira-kira 5 bilion yuan yang ditetapkan pada awal tahun sukar dicapai, kini dijangkakan keuntungan bersih tahunan kira-kira 3 bilion yuan, margin kasar keseluruhan dijangka 13%-14%, margin kasar jualan kenderaan lengkap kira-kira 10%-11%.
Pengurusan menilai, harga bahan mentah besar pada separuh tahun kedua, terutamanya harga litium karbonat, dijangka kekal relatif stabil; seiring peningkatan jualan, pembelian bahan, kos pembuatan dan pembebanan kos tetap akan ditingkatkan, seterusnya menggerakkan margin kasar meningkat berbanding suku sebelumnya.
03
Penghantaran luar negara jangka pendek memberi keutamaan "merebut bahagian" bukan keuntungan
Perniagaan luar negara merupakan sektor yang agak padat maklumat yang dibebaskan dalam persidangan prestasi kali ini.
Dari segi data, pertumbuhan ekspor sangat memberangsangkan. Separuh tahun pertama 2026, jumlah eksport Leapmotor mencapai 96,294 unit, meningkat 372.6% tahun ke tahun, mewakili 27% daripada jumlah jualan separuh tahun. Eksport kumulatif Januari hingga Julai 2026 ialah 113,863 unit, menyelesaikan 75.9% daripada sasaran cabaran tahunan. Syarikat dijangkakan jumlah jualan luar negara sepanjang tahun berpotensi mencapai 200,000 unit.
Bagi tahun hadapan, pengurusan Leapmotor juga sangat optimis, memberikan jangkaan jualan 350,000-400,000 unit, sasaran hampir dua kali ganda daripada jumlah yang dijangka disiapkan 2026. Dari segi struktur wilayah, Eropah masih akan menjadi pasaran terbesar, persentase pasaran Amerika Selatan, Asia Tenggara, Australia akan terus ditingkatkan.
Namun pertumbuhan jualan luar negara dan keuntungan luar negara tidak sepenuhnya selaras.
Pengurusan menyatakan bahawa ini disebabkan pada awal kerjasama kedua belah pihak, tahap margin kasar model yang dijual Leapmotor ke Leapmotor International ditetap rendah, tiga tahun pertama sasaran utama adalah dengan pantas mengembangkan pasaran dan meningkatkan jualan. Sekarang, Leapmotor International sudah mencapai keuntungan pada 2025, tetapi pada separuh tahun pertama 2026 mengalami kerugian kecil kerana faktor operasi, syarikat dijangkakan memulihkan kerugian melalui penyesuaian operasi pada separuh tahun kedua, mencapai keuntungan stabil sepanjang tahun.
Strategi luar negara Leapmotor masih tetap "skala dahulu, keuntungan kemudian".
Bagi Leapmotor, Stellantis menyediakan tiga sokongan penting:
Satu, sumber saluran tempatan, membantu Leapmotor dengan pantas memasuki pasaran Eropah, Amerika Selatan dan lain-lain;
Dua, keupayaan pengeluaran, mengurangkan kos modal dan masa untuk membina kilang tempatan luar negara;
Tiga, sumber rantai bekalan dan logistik, berfaedah untuk mengurangkan tekanan pengangkutan laut dan pembelian komponen tempatan.
Walau bagaimanapun, pengeluaran tempatan tidak semestinya bermaksud peningkatan margin keuntungan yang ketara. Pengurusan mengakui, pengeluaran tempatan luar negara boleh mengoptimalkan kos duti, tetapi harga pembelian komponen tempatan lebih tinggi daripada China, perlu seimbang semula antara penjimatan duti dan peningkatan kos pembelian, oleh itu penambahbaikan margin kasar akibat tempatan semasa ini tidak begitu ketara seperti jangkaan pasaran.
Leapmotor sedang memacu pengeluaran tempatan luar negara, terutamanya di tiga lokasi Malaysia, Sepanyol dan Brazil.
Dari segi projek Malaysia, C10 telah menyelesaikan SOP dan memasuki fasa pengeluaran massal rasmi, B10 dirancang untuk pengeluaran massal dan pelancaran pada suku ketiga 2026.
Dari segi projek Zaragoza Sepanyol, pengubahsuaian pelengkap kilang telah selesai, B10 dijangka mula ditayangkan pada suku ketiga 2026, B05 dirancang untuk ujian pengeluaran tahun ini, pengeluaran massal rasmi 2027, kilang bateri pelengkap juga dijangka melancarkan pengeluaran massal pada suku ketiga.
Dari segi Amerika Selatan, syarikat telah memilih kilang Goiania Brazil sebagai tapak pemasangan tempatan, B10 dirancang untuk ditayangkan pada separuh tahun kedua 2027.
Dari perkembangan projek juga dapat dilihat, dalam sasaran jualan luar negara 2027, bahagian pengeluaran tempatan tidak tinggi. Pengurusan menjangkakan, 2027 model utama pengeluaran tempatan luar negara ialah B10, pengeluaran kira-kira 50,000 unit, seterusnya akan dinaikkan secara fleksibel mengikut perubahan dasar dan kemajuan ralat kerjasama.
Leapmotor telah membuktikan dirinya boleh menjual kereta dengan sangat baik, mendapat pengiktirafan di pasaran dalam dan luar negara. Langkah seterusnya, syarikat perlu menjawab: Semasa jualan luar negara berkembang pesat, adakah ia boleh menukar skala menjadi keuntungan yang stabil dan lestari.
Author | Zhang Rui
Editor | Zhi Hao
Leapmotor Executives: A Major Technology Release Will Happen in September, Overseas Sales Target for Next Year is 350,000 to 400,000 Units.
Carwest reported on August 24, that just now, Zhejiang Leapmotor Technology Co., Ltd. (hereinafter referred to as Leapmotor) held the 2026 Mid-Year Performance Conference Call.
Leapmotor CFO Li Tengfei, Leapmotor Co-President Wu Qiang, Leapmotor Board Secretary Shen Ke attended the Leapmotor 2026 First Half Performance Conference Call. On the conference call, Li Tengfei mainly answered around 16 related questions, among which there were 4 key questions:
1、New Product Planning: Leapmotor's new model launch quantity in 2027 will be greater than 2026, it is a very major product year.
2、Assisted Driving Progress: The assisted driving products released at the September technology launch event have a huge, leapfrogging improvement compared to Leapmotor's current assisted driving.
3、Overseas Sales: Estimated this year overseas sales can reach 200,000 units, next year overseas sales target is around 350,000 to 400,000 units.
4、Robotics Business: Leapmotor has its own plan, and will officially announce Leapmotor's specific information regarding robots in the near future.
According to the financial report, Leapmotor's first-half 2026 revenue was 38.11 billion yuan, up 57.2% year-over-year compared to 24.25 billion yuan in the first half of 2025, creating a historic high for the same period.

▲Leapmotor 2026 First Half Main Financial Data
In terms of net profit, in the first half of 2026, Leapmotor's net profit was 210 million yuan, while in the first half of 2025 it was 30 million yuan, representing a year-over-year growth of approximately 600%.
In terms of sales volume, in the first half of 2026, Leapmotor's total sales volume was 356,500 units, year-over-year growth of 60.8% compared to the same period in 2025, among which export volume was 96,300 units, year-over-year growth of 372.6%, accounting for 27.0% of Leapmotor's total sales volume in the first half of 2026.
Overall, Leapmotor showed significant year-over-year growth in revenue, net profit, and sales volume in the first half of 2026, delivering a brilliant semi-annual financial report.
Article Benefit: Leapmotor releases 2026 first-half financial report, revenue year-over-year growth 57.2%. The financial report document has been prepared for you by Carwest, Reply [Carwest 0994] to download.
01.
Major Technology Release at September Event
New Model Quantity Next Year Greater Than This Year
At the financial report meeting, Leapmotor CFO Li Tengfei answered around 16 related questions. The following is the transcript of the Q&A session of the financial report meeting. Carwest made some readability adjustments without changing the original meaning, and also integrated content of the same type:
1、Can you break down the revenue contribution of Leapmotor's non-vehicle businesses such as carbon credits and R&D services in the second quarter?
Li Tengfei: The overall carbon credit revenue of Leapmotor in the first half of the year was between 800 million to 900 million, around 500 million in the second quarter. Although Leapmotor International achieved a very brilliant sales performance in Europe, the unit selling price of carbon credits decreased compared to last year. Therefore, the overall revenue of carbon credits differs from the sales volume increase proportion compared to last year.
Regarding the contribution of R&D services, in the first half of the year, Leapmotor and FAW, Stellantis and other relevant partners explored R&D services deeper. Everyone will soon receive the good news of our external announcement regarding the reached cooperation.
2、Looking ahead to the second half of the year, will there be some changes in cost-side pressure? Has Leapmotor's latest profit guidance been updated?
Li Tengfei: From the perspective of the full year, we set an annual net profit target of around 5 billion yuan at the beginning of the year. But looking from now, it is indeed very difficult to achieve a net profit target of around 5 billion yuan.
Mainly due to the price increase of raw materials this year, bringing about a decline in gross margin.
From the company's current analysis, we expect the annual net profit level to be around 3 billion yuan, the gross margin level is expected to be around 13 to 14 percent, and the whole vehicle gross margin level should be around 10 to 11 percent.
3、How does Leapmotor realize revenue in cooperation with Stellantis? Will there be model expansion subsequently? Can Leapmotor International use Stellantis's supply chain?
Li Tengfei: We expect further good news to come recently. We reached further cooperation implementation with partners, which is actually more based on Leapmotor's current supply capability of mature three-electric components, empowering our partners in parts supply.
Regarding the revenue brought by cooperation to Leapmotor, I still hope to wait until our cooperation implementation, then elaborate on the specific revenue with everyone.
Regarding localized procurement, including whether to use Stellantis's supply chain, Stellantis Group's supply chain capability locally is certainly a very important resource for us. When we choose the supply chain, Stellantis Group will also give us Leapmotor and Leapmotor International very strong support.
Of course, we will not completely borrow or rely on Stellantis's existing local supply chain. We will also consider comprehensively. Based on the original intention of creating products with better quality and lower cost, we will select the supply chain with Leapmotor International and Stellantis.
Of course, with a flexible international localized supply chain as the foundation, our overall work will be more efficient, and cost control will also be more effective.
4、Can next year's overseas target be updated? How is it divided between regions?
Li Tengfei: This year we gave an overseas sales target of 100,000 to 150,000 units. Looking now, our originally set challenge target for this year, which is 150,000 units, is basically no problem. We expect this year's overseas sales can reach 200,000 units.
So for our next year's overseas sales target, from the company including Leapmotor International, also including Stellantis Group, we are very confident about next year's overseas sales. Our next year's overall overseas sales target is around 350,000 to 400,000 units level. We hope to challenge the sales level of 400,000 units.
Regarding sales distribution, from next year's situation, our overall sales distribution will not have too much difference from this year. The most important market is still Europe. Of course, next year we will further open up the South America market, including Southeast Asia market, Asia-Pacific region market, and Australia market, will also continue to exert effort.
5、What is Leapmotor's overseas capacity situation next year?
Li Tengfei: Actually, we now in Europe, South America, mainly utilize our partners' factories for localized production. We have full discussions with Stellantis Group, and our partners are very capable.
Whether in Europe, South America, or other regions, in the factories Stellantis Group cooperates with us, our partners fully guarantee Leapmotor's capacity, prioritizing Leapmotor's capacity.
Everyone knows, Stellantis Group in Europe, South America and other regions, capacity is still relatively sufficient. So in terms of capacity, this is actually Leapmotor's advantage. Because we have such powerful partners, so we do not need to worry about capacity matters. We both have full communication, also have very good planning for capacity, can fully meet Leapmotor's localization needs in Europe, South America, including other regions.
6、What is the actual profit level per vehicle overseas currently?
Li Tengfei: From the perspective of Leapmotor company, Leapmotor's actual gross margin is the gross margin of this period before selling models to Leapmotor International. We have an agreement between both parties, so our gross margin level is indeed relatively low. Now looking at it, the three-year agreement period is actually gradually coming.
Of course for both of us, we will sit down for full communication. From the actual situation, in these three years, our cooperation has made huge progress. Everyone can see it from sales volume. Also Leapmotor International realized profit last year, this year Leapmotor International's operation situation is also very good. We achieved rapid sales progress under such a model. So next, everyone will also further discuss Leapmotor International's operation.
From our perspective, now we still prioritize overseas market sales volume, because overseas market is currently a rapid growth period. We need to grab the critical period of overseas market development as quickly as possible.
From the perspective of profit, we of course also value profit, but we will put sales volume growth in the most important position.
7、Under the circumstance of small amount of R&D investment, what is the secret of Leapmotor's excellent assisted driving performance?
Li Tengfei: Leapmotor's overall intelligent driving performance this year has gained recognition from the vast number of consumers.
In September this year, we will launch intelligent driving products under the new architecture. I will give a spoiler in advance. Our intelligent driving products under the new architecture have a huge, leapfrogging improvement compared to current products.
As for why investment is small but output is high, actually Leapmotor has always had continuous investment in intelligent driving, not just started investing recently. It is just that the previous stage focused more on laying the foundation. Under the circumstance that the technical route is not clear, we did not rush to invest.
Until we saw technical routes such as physical models, and considered them as the development direction of future intelligent driving, in the second half of last year we overall increased investment in intelligent driving, both in terms of talent and investment.
Plus the models we launched last year, many models carried our own products, generated a large amount of data. So several reasons made our intelligent driving this year have a bigger improvement, which is also the core logic we can launch further products in September.
We have relatively precise grasp of the overall direction, took fewer detours. So our investment was relatively low. But once we determined it, we increased investment strength. Because we have a good foundation, in not too long a time, we achieved significant progress.
8、Is the upper limit of Leapmotor's intelligent driving technical route pure unmanned driving?
Li Tengfei: Actually, whether L2+, L3, or L4, Leapmotor has layout, including intelligent driving software and hardware.
This hardware includes intelligent driving itself's hardware, also includes intelligent chassis hardware. We have a full series layout.
9、In Leapmotor's overseas sales volume, what will be the localization rate? Is there a change in the expectation of Spain factory starting production in October?
Li Tengfei: Regarding Spain factory production start, Leapmotor plans in October for Mr. Zhu (Leapmotor Technology Founder, Chairman and CEO Zhu Jiangming) to lead the company management to Spain factory. Participate in B10 model's localized production start ceremony together with Stellantis executives. Overall timeline progress is very smooth.
Regarding next year's localized production volume, actually next year the main selling local model we have is only B10 one model. So next year in the whole 350,000 to 400,000 units sales volume, the B10 production volume from localized production is not that big.
Because this is also our first year overseas localized production. Involves our and partner's fit. We expect next year's localized production volume is around 50,000 units level.
If policy changes are more favorable, then our overall localized production volume can actually increase. Production is not a problem. Actually we are more with partners to create value for the whole Leapmotor sales volume.
Indeed localization can bring tariff optimization. But we also see localization in parts procurement, indeed compared to domestic parts procurement there will be relatively obvious price increase. Actually after offsetting both, localized gross margin level has improvement, but not as obvious as everyone imagined.
Of course, we are also predicting EU tariff policy changes. We think localization will have more favorable policies, or policies will lean more towards localization.
We think localization's improvement on net profit, actually is not at present, but in the near future. With further policy changes, enhance the important value of localization.
We think whether in Europe, in South America, or in other places in the world, localization is always pursued by Leapmotor. We think localization is always a major strategic direction for us going overseas.
10、Regarding Leapmotor September technology launch event, is there any other information leaked?
Li Tengfei: Regarding September technology launch event, basically set in September 16.
At the technology launch event, besides intelligent driving, actually there will be many major technology information releases. Also there will be many industry senior experts and major guests to participate.
I can tell everyone, whether in intelligent driving aspect, or in battery, electric drive aspects, there will be major technology releases.
11、What are the prospects regarding robotics business?
Li Tengfei: Previously in our newly set company, we added a business scope. This is also a normal addition action.
But I can say this to everyone, we think new energy vehicle enterprises, especially new energy vehicle enterprises with full-domain self-research capability, are one of the enterprises most qualified to do embodied robots.
Leapmotor has its own plan. Moreover, in the near future, everyone will receive our official announcement of Leapmotor's specific information release regarding robots.
12、What is the reason for gross margin expected increase in second half of year compared to previous quarter?
Li Tengfei: First is Leapmotor overall sales volume rise very fast. Product scale effect brought optimization.
Second point is material cost price increase aspect. Everyone can see bulk raw materials price increase. Actually after a wave of price increase in first half of year, now already stabilized. We judge second half bulk raw materials price increase will maintain in relatively stable state.
With our scale improvement bringing cost scale effect release. At the same time under further optimization of material cost and manufacturing expense, come to push our gross margin.
Of course our current gross margin, actually also basically returned to our same period last year level. This cannot be said as a particularly excellent performance. But we also think under such background, able to do this point, still went through whole company above and below unremitting efforts.
13、2027 new car planning currently what can be revealed?
Li Tengfei: Leapmotor this year's new cars already basically launched. Might later have individual model small change launch.
2027 Leapmotor new model launch quantity greater than 2026. D series will have new product launch. C series both has new product launch, also has existing C series new generation product launch. New generation product is our next generation product. C series and B series both will have.
So next year is still Leapmotor's product major year. Moreover it is a very major product year. Our company internal from product itself preparation aspect is not a problem. We are repeatedly pushing our product rhythm.
Due to indeed new products more, plus existing products also have annual change launch. So next year's listing rhythm, launch rhythm, how can ensure each product launch in good time point, this is what we are currently focusing on considering.
14、What is the reason for first half investment income loss?
Li Tengfei: One aspect is Leapmotor International has a little small loss. Main source is exchange gain/loss caused impact. Second half expected to make up first half loss. Leapmotor International this year overall profit. We feel no too big problem.
15、Does Leapmotor have some breakthroughs in shipping capability aspect?
Li Tengfei: Due to China new energy vehicle export explosive growth. Shipping whether RoRo ships or various aspects, indeed in first half presented relatively tense state.
Leapmotor also cooperates with major shipping companies. Also includes cooperating with Stellantis Group in deep communication and cooperation. Overall, currently compared to March, April time shipping speed has certain improvement. We think can guarantee our full year overseas 200,000 units sales.
16、Currently Leapmotor overseas channels exceeded 1,000 stores. Subsequent planning how?
Li Tengfei: Our channels mainly in Europe. In Europe our channels will also further develop. Especially our previously layout relatively small Eastern Europe, Northern Europe etc. countries.
Of course, our overseas channels next step focus point more will be in South America. Leapmotor South America channels quantity now rise speed very fast. Last month Leapmotor formally enter Argentina market. Including Brazil, Chile, Uruguay etc. South America markets. In rapid development and expansion. Also includes our Asia-Pacific region channels further development.
From our perspective, our partners in Europe, South America, Asia-Pacific channels very rich, strength very strong. Like Stellantis Group in South America is market share ranked number one group. Moreover leads second market share very much. So we borrow our partner's strength. Overseas channels progress will be very efficient. Lay foundation for our sales doubling.
02.
First Half Revenue 38.11 Billion Yuan
Net Profit Year-over-Year Growth About 600%
From the financial report meeting, can feel, Leapmotor executives for Leapmotor performance and subsequent development very confident. This naturally has Leapmotor in 2026 first half performance announcement expressed strong momentum support.
According to Zhejiang Leapmotor Technology Co., Ltd. (hereinafter referred to as Leapmotor) released ended June 30, 2026 six-month interim performance announcement. Leapmotor in 2026 first half revenue was RMB 38.11 billion yuan. Compared to 2025 first half 24.25 billion yuan increase 57.2%. Leapmotor side explained mainly due to whole vehicle and spare parts delivery volume increase.

▲Leapmotor 2026 First Half Revenue
Regarding gross margin aspect, Leapmotor 2026 first half gross margin was 11.7%. Compared to 2025 first half 14.1% decreased 2.4 percentage points. Leapmotor side explained mainly due to raw material cost increase impact and whole vehicle product mix changes.

▲Leapmotor 2026 First Half Gross Profit
First half 2026, Leapmotor's net profit was 210 million yuan. While 2025 first half was 30 million yuan. Year-over-year growth about 600%.

▲Leapmotor 2026 First Half Net Profit
Regarding sales volume aspect, first half 2026, Leapmotor total sales volume was 356,500 units. Compared to 2025 same period delivery volume growth 60.8%. In this year already published data first 5 months comparable terminal license quantity, Leapmotor ranked global new energy passenger car brand fourth name.
Among them, Leapmotor in 2026 first half export volume 96,300 units. Year-over-year growth 372.6%. Already exceeded 2025 full year export total. Accounted for 2026 first half Leapmotor total sales 27.0%. July 2026, Leapmotor export volume 17,600 units. 2026 Jan-July cumulative export volume already reached 113,900 units.
In July 2026, Leapmotor delivery volume reached new high, reached 101,300 units. Single month delivery first break 100,000 unit threshold. Become domestic first single month delivery volume break 100,000 units new force brand.
 Zoom In
▲Leapmotor 2026 First Half Sales
Leapmotor 2026 first half R&D expense was 2.32 billion yuan. Compared to 2025 first half 1.89 billion yuan increase 22.8%. Leapmotor side introduced this change mainly due to R&D investment intensity increase and R&D personnel increase.
Leapmotor side also specially mentioned. Currently City Navigation assisted driving function already at Leapmotor ABCD full series models open. At same time will 2026 third quarter to LEAP3.0 architecture models push national city navigation assisted driving. In addition, Leapmotor will 2026 September launch new architecture assisted driving solution.

▲Leapmotor 2026 First Half R&D Performance
Regarding cash reserve aspect, until June 30, 2026, Leapmotor's cash and cash equivalents, restricted cash, financial assets at fair value through profit or loss and bank time deposit balance is RMB 38.59 billion yuan.
Regarding sales channel aspect, until June 30, 2026, Leapmotor's sales service network has covered 298 cities. City coverage rate reached 87.4%. Cumulative layout 1,064 sales stores (including 459 Leapmotor centers and 605 experience centers) and 562 service stores. Compared to 2025 same period increase 258 sales stores and 101 service stores.

▲Leapmotor 2026 First Half Sales Channel Expansion
Regarding going overseas aspect, until 2026 June end, Leapmotor International B.V. (Leapmotor International) already in Europe, South America, North America, Asia-Pacific, Middle East and Africa etc. over 45 international markets established over 1,000 outlets both having sales and after-sales service functions. Among them Europe over 900 stores, Asia-Pacific market over 50 stores, South America market over 30 stores, North America market over 30 stores.
At same time, Leapmotor brand is accelerating promote overseas localized assembly production layout.
In Southeast Asia, Leapmotor Malaysia localized assembly project has achieved substantive progress: Relying on Stellantis Group located Malaysia Kedah State Gurun factory. C10 model completed SOP and entered formal mass production stage. Soon in Malaysia market start sales. B10 model planned to Q3 achieve mass production and simultaneous launch.
In Europe, Leapmotor Spain localized assembly project progressed simultaneously. Stellantis Group Zaragoza factory completed supporting transformation. B10 project expected Q3 formal production start. B05 project planned within year trial production, 2027 formal mass production. For above models matching battery factory also completed transformation, expected Q3 start mass production.
In South America, Leapmotor and Stellantis Group already selected Stellantis Group Brazil Goiania factory as South America localized assembly project assembly base. Will first start Leapmotor B10 localized assembly production. Planned to 2027 second half formally put into mass production.

▲Leapmotor 2026 First Half Globalization Progress
03.
Conclusion: Leapmotor Accelerates Sprinting
In fiercely competitive new energy vehicle market, Leapmotor in 2026 first half handed out a remarkable scorecard. Revenue and sales volume move together. Net profit also 600% growth. Showed strong development momentum.
In addition, Leapmotor single month delivery volume already broke 100,000 units threshold. Overseas market expansion also results splendid. Also is accelerating promote overseas localized assembly production layout. Further push global market performance.
Combining next year new model quantity greater than this year and next year 350,000 to 400,000 units overseas sales target looking, Leapmotor is accelerating sprinting.
Pengarang | Zhang Rui
Editor | Zhi Hao
Eksekutif Leapmotor: September akan ada pelancaran teknologi utama, sasaran jualan luar negara tahun depan 350,000 hingga 400,000 unit.
Khabar Kereta pada 24 Ogos memberi tahu, sebentar tadi, Zhejiang Leapmotor Technology Co., Ltd. (disebut sebagai Leapmotor) telah memulakan mesyuarat telefon prestasi pertengahan tahun 2026.
Ketua Kewangan Leapmotor, Li Tengfei, Presiden Bersama Leapmotor, Wu Qiang, Setiausaha Jawatankuasa Pengurusan Leapmotor, Shen Ke, menghadiri mesyuarat telefon prestasi separuh pertama tahun 2026 Leapmotor. Dalam mesyuarat telefon, Li Tengfei terutama menjawab kira-kira 16 soalan yang berkaitan, di mana ada 4 soalan penting:
1. Perancangan Produk Baharu: Jumlah model baharu Leapmotor yang akan dilancarkan pada 2027 lebih tinggi daripada tahun 2026, merupakan tahun produk yang sangat besar.
2. Kemajuan Memandu Bantu: Produk memandu bantu yang dilancarkan dalam sidang teknologi bulan September, berbanding produk memandu bantu Leapmotor semasa, mempunyai peningkatan besar dan melompat.
3. Jualan Luar Negara: Diraikan jualan luar negara tahun ini boleh mencapai 200,000 unit, sasaran jualan luar negara tahun depan sekitar 350,000 hingga 400,000 unit.
4. Perniagaan Robot: Leapmotor mempunyai perancangan sendiri, dalam masa tidak lama lagi akan mengisytiharkan secara rasmi maklumat khusus Leapmotor berkaitan robot.
Dari laporan kewangan, pendapatan separuh pertama tahun 2026 Leapmotor ialah RMB 38.11 bilion, berbanding 24.25 bilion Yuan pada separuh pertama tahun 2025, bertambah 57.2% secara tahun ke tahun, memecahkan rekod sejarah pada tempoh yang sama.
▲Data Kewangan Utama Leapmotor Separuh Pertama 2026
Dari segi keuntungan bersih, pada separuh pertama tahun 2026, keuntungan bersih Leapmotor ialah 210 juta Yuan, manakala pada separuh pertama tahun 2025 ialah 30 juta Yuan, bertambah kira-kira 600% secara tahun ke tahun.
Dari segi jualan, pada separuh pertama tahun 2026, jumlah jualan Leapmotor ialah 356,500 unit, berbanding tempoh yang sama tahun 2025 bertambah 60.8%, di mana eksport 96,300 unit, secara tahun ke tahun bertambah 372.6%, mewakili 27.0% daripada jumlah jualan Leapmotor pada separuh pertama 2026.
Keseluruhannya, Leapmotor mencatatkan penambahan tahun ke tahun yang besar dari segi pendapatan, keuntungan bersih dan jualan pada separuh pertama tahun 2026, mengeluarkan laporan separuh tahun yang menarik.
Manfaat artikel ini: Leapmotor menerbitkan laporan kewangan separuh pertama 2026, pendapatan bertambah 57.2% secara tahun ke tahun. Fail laporan kewangan telah disediakan oleh Khabar Kereta untuk anda, balas [Khabar Kereta 0994] untuk memuat turun.
01.
Sidang Teknologi September Akan Ada Pelancaran Teknologi Utama
Jumlah Model Baharu Tahun Depan Lebih Tinggi Daripada Tahun Ini
Dalam mesyuarat laporan kewangan, Ketua Kewangan Leapmotor, Li Tengfei, menjawab kira-kira 16 soalan yang berkaitan, berikut adalah transkrip sesi soal jawab mesyuarat laporan kewangan, Khabar Kereta telah membuat beberapa penyesuaian kebolehbacaan tanpa mengubah maksud asal, dan mengintegrasikan kandungan jenis yang sama:
1. Bolehkah menguraikan sumbangan pendapatan daripada perniagaan bukan kereta seperti kredit karbon dan perkhidmatan R&D Leapmotor pada suku kedua?
Li Tengfei: Pendapatan kredit karbon keseluruhan Leapmotor pada separuh pertama tahun ini berada pada 800 juta hingga 900 juta, suku kedua sekitar 500 juta. Walaupun Leapmotor International mendapat prestasi jualan yang sangat menarik di Eropah, harga jual kredit karbon agak menurun berbanding tahun lalu, jadi pendapatan keseluruhan kredit karbon berbeza dengan nisbah peningkatan jualan berbanding tahun lalu.
Mengenai sumbangan perkhidmatan R&D, pada separuh pertama tahun ini, Leapmotor dan rakan kongsi seperti FAW, Stellantis, dan lain-lain telah berbincang lebih mendalam mengenai perkhidmatan R&D, sebentar lagi anda akan menerima berita baik pengumuman rasmi kerjasama yang telah dicapai.
2. Melangkah ke separuh kedua, adakah tekanan dari kos pengeluaran akan ada perubahan? Adakah bimbingan keuntungan terkini Leapmotor telah dikemaskini?
Li Tengfei:Dari sudut tahun penuh, pada permulaan tahun kami menetapkan sasaran keuntungan bersih tahunan sekitar 5 bilion. Tetapi dari sekarang, mencapai sasaran keuntungan bersih sekitar 5 bilion benar-benar sangat sukar.
Terutamanya disebabkan kenaikan harga bahan mentah tahun ini, membawa kepada penurunan margin kasar.
Dari analisis syarikat sekarang, kami jangka tahap keuntungan bersih tahunan sepatutnya sekitar 3 bilion, tahap margin kasar dijangkakan pada 13 hingga 14 peratus, tahap margin kasar kenderaan lengkap sepatutnya pada 10 hingga 11 peratus.
3. Bagaimana Leapmotor merealisasikan hasil dalam kerjasama dengan Stellantis? Adakah akan ada pengembangan model seterusnya? Bolehkah Leapmotor International menggunakan rangkaian bekalan Stellantis?
Li Tengfei:Kami berharap berita baik yang lebih lanjut akan tiba tidak lama lagi. Kerjasama yang lebih lanjut yang dicapai dengan rakan kongsi, sebenarnya lebih berdasarkan keupayaan bekalan komponen tiga sistem yang matang Leapmotor sekarang, memberi kuasa kepada rakan kongsi kami dalam bekalan komponen.
Mengenai hasil kerjasama yang dibawa kepada Leapmotor, saya masih berharap untuk bincang secara terperinci hasil khusus dengan anda apabila kerjasama kami dilaksanakan.
Mengenai pembelian tempatan, termasuk adakah akan menggunakan rangkaian bekalan Stellantis, keupayaan rangkaian bekalan tempatan dalam kumpulan Stellantis sememangnya merupakan sumber sumber penting kami, ketika kami memilih rangkaian bekalan, kumpulan Stellantis juga akan memberikan sokongan yang sangat besar kepada kami dan Leapmotor International.
当然 kami juga tidak akan sepenuhnya meminjam atau bergantung pada rangkaian bekalan sedia ada Stellantis tempatan, kami juga akan pertimbangan secara menyeluruh, mematuhi asal untuk mencipta produk dengan kualiti lebih baik dan kos lebih rendah, untuk memilih rangkaian bekalan dengan Leapmotor International dan Stellantis.
Tentulah jika ada rangkaian bekalan antarabangsa tempatan yang fleksibel sebagai asas, kerja keseluruhan kami akan lebih cekap, kawalan kos juga akan lebih berkesan.
4. Adakah sasaran luar negara tahun depan boleh dikemaskini? Bagaimana bahagikan antara setiap wilayah?
Li Tengfei:Tahun ini kami memberikan sasaran jualan luar negara 100,000 hingga 150,000 unit, dari sekarang kita lihat sasaran cabaran asal tahun ini, iaitu 150,000 unit pada dasarnya tiada masalah, kami jangka jualan luar negara tahun ini boleh mencapai 200,000 unit.
Oleh itu untuk sasaran jualan luar negara tahun depan kami, dari seluruh syarikat termasuk Leapmotor International, malah kumpulan Stellantis, mempunyai keyakinan yang sangat besar terhadap jualan luar negara tahun depan. Sasaran jualan luar negara keseluruhan kami tahun depan berada pada tahap 350,000 hingga 400,000 unit, berharap boleh mencabar tahap jualan 400,000 unit.
Mengenah taburan jualan, dari keadaan tahun depan, taburan jualan keseluruhan kami tidak akan berbeza terlalu banyak dengan tahun ini. Pasaran utama masih di Eropah, tentu saja tahun depan pasaran Amerika Selatan kami akan membuka lebih lanjut, termasuk juga pasaran Asia Tenggara, pasaran wilayah Asia Pasifik dan pasaran Australia, akan terus berusaha keras.
5. Bagaimana situasi keupayaan pengeluaran Leapmotor di luar negara tahun depan?
Li Tengfei:Sebenarnya sekarang kami di Eropah, Amerika Selatan, terutama menggunakan kilang rakan kongsi kami untuk pengeluaran tempatan. Kami mempunyai perbincangan yang mencukupi dengan kumpulan Stellantis, rakan kongsi kami juga sangat sokongan.
Baik di Eropah, Amerika Selatan atau wilayah lain, dalam kilang yang berkerjasama dengan kami, rakan kongsi kami memastikan keupayaan pengeluaran Leapmotor dengan penuh, mengutamakan jaminan keupayaan pengeluaran Leapmotor.
Semua orang juga tahu, kumpulan Stellantis di wilayah Eropah, Amerika Selatan, keupayaan pengeluaran agak mencukupi, jadi dari segi keupayaan pengeluaran ini sebenarnya adalah kelebihan Leapmotor. Kerana kami mempunyai rakan kongsi yang kuat seperti ini, jadi kami tidak perlu bimbang tentang masalah keupayaan pengeluaran, kami kedua-dua pihak ada komunikasi yang mencukupi, ada perancangan yang sangat baik untuk keupayaan pengeluaran, boleh memenuhi sepenuhnya keperluan tempatan Leapmotor di Eropah, Amerika Selatan, malah wilayah lain.
6. Bagaimana tahap keuntungan sebenar per unit kenderaan di luar negara sekarang?
Li Tengfei:Dari sudut syarikat Leapmotor, margin kasar sebenar Leapmotor ialah margin kasar daripada jualan model kepada Leapmotor International sebelum ini, kami ada persetujuan antara kami berdua, jadi tahap margin kasar kami memang agak rendah, dan dari sekarang jangkaan tempoh tiga tahun hampir tiba.
Tentu juga untuk kami berdua, kami akan duduk berbincang secara mencukupi, dari keadaan sebenar, ketiga tahun ini kerjasama kami kedua belah pihak telah mencapai kemajuan besar, semua orang boleh lihat dari jualan, dan Leapmotor International tahun lalu juga telah merealisasikan keuntungan, tahun ini keadaan operasi Leapmotor International juga sangat baik, kami dalam model ini telah mencatatkan perkembangan jualan yang cepat, jadi seterusnya, semua orang akan terus berbincang mengenai operasi Leapmotor International.
Dari sudut kami sekarang masih mengutamakan jualan pasaran luar negara, kerana pasaran luar negara sekarang berada dalam fasa pertumbuhan pesat, harus cuba secepat mungkin merebut tempoh penting pembangunan pasaran luar negara.
Dari sudut keuntungan, kami tentu juga mengutamakan keuntungan, tetapi kami akan letakkan pertumbuhan jualan di tempat paling penting.
7. Dalam keadaan perbelanjaan R&D yang sedikit, apakah rahsia prestasi memandu bantu Leapmotor yang cemerlang?
Li Tengfei:Prestasi memandu pintar keseluruhan Leapmotor tahun ini, telah mendapat pengiktirafan daripada majoriti pengguna.
Dalam September tahun ini, kami akan melancarkan produk memandu pintar di bawah rangka kerja baharu. Saya mendedahkan sikit lebih awal, produk memandu pintar di bawah rangka kerja baharu kami, berbanding produk sekarang ada peningkatan yang besar dan melompat.
Mengenai mengapa投入少 namun output tinggi, sebenarnya Leapmotor sentiasa ada投入 terus dalam aspek memandu pintar, bukan baru-baru ini baru bermula投入, hanya pada awal lebih mengutamakan asas, dalam keadaan rantaian teknologi tidak jelas, kami tidak tergesa-gesa untuk投入.
Hingga kami nampak teknologi rantaian model fizikal seperti ini, menganggap sebagai arah pembangunan masa hadapan memandu pintar, pada separuh kedua tahun lalu kami secara keseluruhannya memperbanyak投入 dalam aspek memandu pintar, baik dalam mahir mahir mahupun投入.
Menambah model yang kami lancarkan tahun lalu, ada banyak model yang dilengkapi produk sendiri kami, menghasilkan data yang banyak, jadi sebab-sedap berbilang membolehkan tahun ini memandu pintar kami ada peningkatan yang besar, juga merupakan logik teras kami boleh melancarkan produk yang lebih lanjut dalam September.
Kami dalam keseluruhan pemantapan arah agak tepat, kurang berjalan sedikit laluan bengkok, jadi投入 kami relatif sedikit. Tetapi kami sekali sudah lihat jelas, maka memperbanyak力量投入, kerana kami ada asas yang sangat baik, dalam masa yang tidak terlalu lama, telah mencapai kemajuan yang besar.
8. Adakah had teknologi memandu pintar Leapmotor ialah memandu tanpa pemandu sepenuhnya?
Li Tengfei:Sebenarnya sama ada L2+, L3 atau L4, Leapmotor ada perancangan, termasuk perisian dan perkakasan memandu pintar.
Perkakasan ini sama ada termasuk perkakasan memandu pintar itu sendiri, malah perkakasan lantai pintar, kami ada perancangan siri lengkap.
9. Dalam jualan luar negara Leapmotor, berapa peratus tempatan? Adakah jangkaan kilang Sepanyol bermula operasi Oktober berubah?
Li Tengfei:Mengenai kilang Sepanyol bermula operasi, Leapmotor merancang pada Oktober oleh En. Zhu (Penciri, Pengerusi dan CEO Leapmotor, Zhu Jiangming) membawa pengurusan syarikat ke kilang Sepanyol, bersama eksekutif Stellantis menghadiri upacara pengeluaran tempatan model B10, kemajuan masa keseluruhan sangat lancar.
Mengenai jumlah pengeluaran tempatan tahun depan, tahun depan sebenarnya model tempatan yang kami utama jualan hanya B10 sahaja. Jadi daripada jumlah jualan 350,000 hingga 400,000 unit tahun depan, jumlah pengeluaran B10 pengeluaran tempatan sebenarnya tidak begitu besar.
Kerana ini juga tahun pertama kami pengeluaran tempatan di luar negara, melibatkan percampuran kami dengan rakan kongsi, kami jangka jumlah pengeluaran tempatan tahun depan pada tahap sekitar 50,000 unit.
Jika perubahan dasar lebih baik, maka jumlah pengeluaran tempatan kami sebenarnya juga boleh ditambah. Pengeluaran bukan masalah, sebenarnya kami lebih banyak sama rakan kongsi untuk menciptakan nilai untuk jumlah jualan keseluruhan Leapmotor.
Kerana tempatan memang boleh membawa pengoptimuman tarif, tetapi kami juga nampak tempatan dalam pembelian komponen, sebenarnya berbanding pembelian komponen domestik ada kenaikan harga yang jelas. Sebenarnya selepas saling tolak, tahap margin kasar tempatan ada perbaikan, tetapi tidak seteruk yang dibayangkan semua orang.
Tentu juga kami sedang mengantisipasi perubahan dasar tarif EU, kami fikir tempatan akan ada lebih banyak dasar positif, atau dasar akan lebih condong kepada tempatan.
Kami fikir peningkatan hasil bersih tempatan sebenarnya bukan sekarang, tetapi dalam masa tidak lama lagi, seiring dengan perubahan dasar, meningkatkan nilai kepentingan tempatan.
Kami fikir baik di Eropah, Amerika Selatan, atau di tempat lain di dunia, tempatan sentiasa dikejar oleh Leapmotor. Kami fikir tempatan sentiasa merupakan arah strategik penting kami keluar dari negara.
10. Mengenai sidang teknologi September Leapmotor, ada maklumat lain yang bocor?
Li Tengfei:Mengenai sidang teknologi September, pada dasarnya定于 16 September.
Dalam sidang teknologi selain memandu pintar, sebenarnya akan ada banyak maklumat teknologi utama yang diumumkan. Dan juga akan ada banyak pakar industri yang berpengalaman dan tetamu utama untuk menyertai.
Saya boleh beritahu anda, baik dalam aspek memandu pintar, mahupun dalam aspek bateri, penggerak, akan ada pelancaran teknologi utama.
11. Apakah jangkaan mengenai perniagaan robot?
Li Tengfei:Sebelum ini dalam syarikat baharu kami yang telah ditambah satu ruang perniagaan, ini juga penambahan tindakan biasa.
Tetapi saya boleh beritahu semua orang, kami fikir syarikat automotif tenaga baharu, terutamanya syarikat automotif tenaga baharu yang mempunyai keupayaan penyelidikan dan pembangunan serba boleh, adalah salah satu syarikat yang paling layak untuk membuat robot badan.
Leapmotor ada perancangan sendiri, dan dalam masa tidak lama lagi, semua orang akan menerima pengumuman rasmi kami tentang pengumuman maklumat khusus Leapmotor berkaitan robot.
12. Apakah sebab peningkatan jangkaan margin kasar tahun kedua separuh?
Li Tengfei:Pertama sekali jualan keseluruhan Leapmotor sangat meningkat, kesan skala produk membawa kepada pengoptimuman.
Titik kedua ialah kenaikan kos bahan, semua orang dapat lihat kenaikan bahan mentah besar, sebenarnya selepas gelombang kenaikan separuh pertama tahun ini kini sudah stabil. Kami menjangkakan kenaikan bahan mentah besar separuh kedua tahun ini akan kekal pada keadaan yang sangat stabil.
Seiring peningkatan skala kami membawa kepada pelepasan kesan skala kos, pada masa yang sama dalam kos bahan dan perbelanjaan pembuatan yang lebih dipertingkatkan, untuk mendorong margin kasar kami.
Tentu juga margin kasar kami sekarang, sebenarnya juga sudah kembali kepada paras tahun lalu pada tempoh yang sama, ini tidak boleh disebut sebagai prestasi yang sangat baik, tetapi kami juga fikir dalam latar besar sedemikian, dapat mencapai ini, masih melalui usaha tidak putus-putus seluruh syarikat.
13. Apakah yang boleh bocor mengenai perancangan model baharu 2027?
Li Tengfei:Model baharu Leapmotor tahun ini sudah pada dasarnya dilancarkan, mungkin kemudian akan ada model kecil ubah suai yang sedikit dilancarkan.
Jumlah model baharu Leapmotor yang akan dilancarkan 2027 lebih tinggi daripada 2026, siri D akan ada produk baharu dilancarkan, siri C ada produk baharu dilancarkan, juga ada produk siri C sedia ada dilancarkan. Produk ganti adalah produk generasi seterusnya kami, siri C dan B akan ada.
Oleh itu tahun depan masih merupakan tahun produk Leapmotor, dan merupakan tahun produk yang sangat besar, dari sudut perancangan本身 produk kami sendiri pada asasnya tiada masalah. Kami sedang secara berulang推进节奏 produk kami.
Kerana produk baharu memang banyak, ditambah model sedia ada ada pengubahsuaian tahunan, jadi节奏 pelancaran tahun depan,节奏 pelancaran, bagaimana boleh pastikan setiap pelancaran produk berada pada waktu yang baik, ini sekarang kami sedang berfikir penting.
14. Mengapa pelaburan keuntungan separuh pertama ada kerugian?
Li Tengfei:Satu pihak ialah Leapmotor International ada sedikit kerugian kecil, sumber utama ialah kesan kerugian keuntungan pertukaran mata wang, pada separuh kedua dijangka akan memulihkan kerugian separuh pertama, Leapmotor International tahun ini keuntungan keseluruhan, kami fikir tiada masalah terlalu besar.
15. Adakah ada lompatan dalam keupayaan pengangkutan laut Leapmotor?
Li Tengfei:Kerana ledakan eksport automotif tenaga baharu China, pengangkutan laut sama ada kapal rol atau dari segi lain, memang pada separuh pertama menunjukkan keadaan agak tegang.
Leapmotor juga sedang bekerjasama dengan syarikat pengangkutan laut besar-besaran, termasuk juga dengan kumpulan Stellantis进行深入 komunikasi dan kerjasama. Keseluruhan, sekarang berbanding masa Mac-April kadar penghantaran ada peningkatan tertentu, kami fikir boleh memastikan jualan luar negara 200,000 unit kami sepanjang tahun.
16. Saluran luar negara Leapmotor sekarang melebihi 1000, apakah perancangan seterusnya?
Li Tengfei:Saluran kami utama di Eropah, di Eropah saluran kami akan berkembang lebih lanjut, terutamanya negara Eropah Timur, Eropah Utara yang sebelumnya pelan lebih sedikit.
Tentu juga, titik usaha seterusnya saluran luar negara kami lebih banyak di Amerika Selatan, jumlah saluran Leapmotor Amerika Selatan sekarang kadar kenaikan sangat cepat, bulan lalu Leapmotor secara rasmi memasuki pasaran Argentina, termasuk Brazil, Chile, Uruguay dan lain-lain pasaran Amerika Selatan, sedang mengembangkan dan memperluaskan dengan cepat, pada masa yang sama termasuk pengembangan saluran wilayah Asia Pasifik kami.
Dari sudut kami, saluran rakan kongsi kami di Eropah, Amerika Selatan, Asia Pasifik sangat kaya, kekuatan sangat kuat. Seperti kumpulan Stellantis di Amerika Selatan adalah kumpulan pertama pasaran, dan memimpin pasaran kedua jauh banyak, jadi kami memanfaatkan kekuatan rakan kongsi kami, kemajuan saluran luar negara akan sangat cekap, meletakkan asas yang baik untuk pelipatgandaan jualan kami.
02.
Pendapatan Separuh Pertama 38.11 Bilion Yuan
Keuntungan Bersih Bertambah 600% Secara Tahun ke Tahun
Dari mesyuarat laporan kewangan boleh merasa, eksekutif Leapmotor sangat yakin terhadap prestasi Leapmotor dan pembangunan seterusnya, antara ini tentu ada sokongan yang Leapmotor tunjukkan pada pengumuman prestasi separuh pertama 2026.
Menurut pengumuman prestasi pertengahan enam bulan Leapmotor Technology Co., Ltd., Zhejiang (disebut sebagai Leapmotor) yang diterbitkan sehingga 30 Jun 2026, pendapatan Leapmotor pada separuh pertama 2026 ialah RMB 38.11 bilion, berbanding separuh pertama 2025 24.25 bilion bertambah 57.2%, pihak Leapmotor menjelaskan utama disebabkan peningkatan jumlah penghantaran kenderaan lengkap dan suku ganti.
▲Pendapatan Leapmotor Separuh Pertama 2026
Dari segi margin kasar, margin kasar Leapmotor pada separuh pertama 2026 ialah 11.7%, berbanding separuh pertama 2025 14.1% turun 2.4 peratus titik, pihak Leapmotor menjelaskan utama disebabkan kenaikan kos bahan mentah dan perubahan gabungan produk kenderaan lengkap.
▲Margin Kasar Leapmotor Separuh Pertama 2026
Pada separuh pertama 2026, keuntungan bersih Leapmotor ialah 210 juta Yuan, manakala separuh pertama 2025 ialah 30 juta Yuan, bertambah 600% secara tahun ke tahun.
▲Keuntungan Bersih Leapmotor Separuh Pertama 2026
Dari segi jualan, pada separuh pertama 2026, jumlah jualan Leapmotor ialah 356,500 unit, berbanding penghantaran tempoh yang sama tahun 2025 bertambah 60.8%, dalam 5 bulan pertama data yang diumumkan tahun ini daripada bilangan plat hujung terminal yang boleh dibandingkan, Leapmotor menduduki tempat keempat jenama kenderaan penumpang tenaga baharu dunia.
Dari mana, jumlah eksport Leapmotor pada separuh pertama 2026 ialah 96,300 unit, bertambah 372.6% secara tahun ke tahun, sudah melebihi jumlah eksport keseluruhan 2025, mewakili 27.0% daripada jumlah jualan keseluruhan Leapmotor pada separuh pertama 2026. Julai 2026, jumlah eksport Leapmotor ialah 17,600 unit, Januari-Julai 2026 jumlah eksort terkumpul sudah mencapai 113,900 unit.
Dalam Julai 2026, penghantaran Leapmotor lagi pecah rekod, mencapai 101,300 unit, penghantaran sebulan pertama kali pecah 100,000 unit, menjadi jenama kekuatan baru domestik pertama yang penghantaran sebulan pecah 100,000 unit.
Paparan Besar
▲Jualan Leapmotor Separuh Pertama 2026
Pengeluaran R&D Leapmotor pada separuh pertama 2026 ialah 2.32 bilion Yuan, berbanding separuh pertama 2025 1.89 bilion bertambah 22.8%, pihak Leapmotor memperkenalkan perubahan ini utama disebabkan peningkatan usaha投入 R&D dan penambahan kakitangan R&D.
Pihak Leapmotor juga secara khas menyebut, sekarang fungsi memandu bantu pengurusan bandar sudah dibuka pada semua model ABCD Leapmotor, pada masa yang sama pada suku ketiga 2026 akan mengesampingkan semua bandar memandu bantu pengurusan kepada model rangka kerja LEAP 3.0. Selain itu, Leapmotor akan pada September 2026 melancarkan pelan memandu bantu rangka kerja baharu.
▲Prestasi R&D Leapmotor Separuh Pertama 2026
Dari segi simpanan tunai, sehingga 30 Jun 2026, simpanan tunai Leapmotor dan setara tunai, tunai terhad, aset kewangan dikira kerugian keuntungan berdasarkan nilai samsar dan baki deposit tetap bank ialah RMB 38.59 bilion.
Dari segi saluran jualan, sehingga 30 Jun 2026, rangkaian perkhidmatan jualan Leapmotor sudah meliputi 298 bandar, kadar meliputi bandar 87.4%, terkumpul 1,064 kedai jualan (termasuk 459 pusat Leapmotor dan 605 pusat pengalaman) dan 562 kedai perkhidmatan, berbanding separuh pertama 2025 bertambah 258 kedai jualan dan 101 kedai perkhidmatan.
▲Pengembangan Saluran Jualan Leapmotor Separuh Pertama 2026
Dari aspek keluar negara, sehingga akhir Jun 2026, Leapmotor International B.V. ("Leapmotor International") sudah di Eropah, Amerika Selatan, Amerika Utara, Asia Pasifik, Timur Tengah dan Afrika dan lebih 45 pasaran antarabangsa membina lebih 1,000 cawangan yang mempunyai fungsi jualan dan perkhidmatan selepas jualan, di mana Eropah lebih 900, pasaran Asia Pasifik lebih 50, pasaran Amerika Selatan lebih 30, pasaran Amerika Utara lebih 30.
Serentak itu, jenama Leapmotor sedang mempercepat memajukan布局 pengeluaran perakitan tempatan luar negara.
Dalam Asia Tenggara, projek perakitan tempatan Leapmotor Malaysia sudah mencapai kemajuan substantif: bergantung pada kilang Gurun di wilayah Kedah, Malaysia yang dimiliki oleh kumpulan Stellantis, model C10 sudah selesai SOP dan masuk fasa pengeluaran rasmi, akan segera di Malaysia pasaran melancarkan jualan; model B10 dirancang pada suku ketiga untuk merealisasikan pengeluaran dan serentak keluar pasaran.
Dalam Eropah, projek perakitan tempatan Leapmotor Sepanyol serentak推进, kilang Zaragoza kumpulan Stellantis sudah selesai pengubahsuaian sokongan, projek B10 dijangkakan suku ketiga bermula operasi rasmi, projek B05 dirancang dalam tahun ini ujian pengeluaran, 2027 keluar pengeluaran rasmi; bateri yang menyokong model ini juga sudah selesai pengubahsuaian, dijangkakan suku ketiga mulakan pengeluaran.
Dalam Amerika Selatan, Leapmotor dan kumpulan Stellantis sudah memilih kilang Goiania di Brazil yang dimiliki oleh kumpulan Stellantis sebagai tapak perakitan projek perakitan tempatan Amerika Selatan, akan segera mulakan pengeluaran perakitan tempatan Leapmotor B10, dirancang pada separuh kedua 2027 secara rasmi masuk pengeluaran.
▲Kemajuan Globalisasi Leapmotor Separuh Pertama 2026
03.
Penutup: Leapmotor Mempercepat
Dalam pasaran automotif tenaga baharu yang sangat kompetitif, Leapmotor pada separuh pertama 2026 telah mengeluarkan prestasi yang menarik. Pendapatan dan jualan berjalan seiring, keuntungan bersih juga ada pertumbuhan 600%, menunjukkan momentum pembangunan yang kuat.
Selain itu, penghantaran sebulan Leapmotor sudah pecah 100,000 unit, pembangunan pasaran luar negara juga mempunyai hasil yang gemilang, sedang mempercepat memajukan布局 pengeluaran perakitan tempatan luar negara,进一步推动 prestasi dalam pasaran global.
Dari segi jumlah model baharu tahun depan lebih tinggi daripada tahun ini dan sasaran jualan luar negara 350,000 hingga 400,000 unit tahun depan, Leapmotor sedang mempercepat.

In the first half of 2026, China's total automotive exports reached 5.31 million units, including 2.42 million new energy vehicle exports, a year-on-year increase of 70%. The image shows Leapmotor's B10 and C10 global models at the 2026 Indonesia International Motor Show.
Statistical data shows that in the first half of 2026, China's total automotive exports reached 5.31 million units, a year-on-year increase of 53%; among them, new energy vehicle exports reached 2.42 million units, a year-on-year increase of 70%, further consolidating China's position as the world's number one automotive exporting country.
On the one hand, geopolitical risks have driven up global oil prices, enhancing the competitiveness of Chinese new energy vehicles; on the other hand, the continuous expansion of the 'Global South' markets has prompted Chinese automakers to rush to accelerate their overseas layouts. For Leapmotor Motors, aiming to challenge the annual sales milestone of 1 million units, the July results further validate the effectiveness of the domestic and international dual-wheel drive.
It is understood that Leapmotor delivered 101,267 units in the domestic market in July, doubling year-on-year, becoming the first new force automaker to break the 100,000 units monthly sales mark. In the first half of this year, Leapmotor's cumulative sales reached 356,487 units, a year-on-year increase of about 97%, making it the only new force brand to break the 300,000 units sales milestone in the first half of this year. Models such as A10, B Series, C10, and D19 bloomed in multiple points, consolidating Leapmotor's growth foundation.
Recently, Leapmotor showcased its two global models, Leapmotor B10 and C10, at the 2026 Indonesia International Motor Show and officially announced its entry into the Indonesian market. Leapmotor also jointly announced with the Indonesian Indomobil Group the official launch of localized KD assembly production in Indonesia. Through deep cooperation with PT National Assemblers under the Indomobil Group, Leapmotor achieved a leap from product output to localized whole industry chain layout. As of now, Leapmotor has formed a dual manufacturing base layout in Malaysia and Indonesia, becoming one of the few Chinese new energy brands with dual KD capacity in Southeast Asia.
Some analysts believe that China's new energy vehicle industry has currently formed a development pattern of 'domestic scaling as a bottom line, global expansion adding volume', and neither aspect should be neglected. For example, Leapmotor's breakthrough of 100,000 units in monthly sales marks that new force automakers have officially entered the volume tier of mainstream automakers. Industry competition has shifted from single-product comparison to a long-term contest of comprehensive systems including supply chain, self-developed manufacturing, and channel services.
In recent years, Chinese new energy vehicles going global have bid farewell to simple whole vehicle exports, shifting to a new stage of 'technology export + local factory construction + ecosystem co-building'. It is understood that relying on the three-party synergy with Stellantis and the Indonesian Indomobil Group, Leapmotor adopts a brand co-store sales model, leveraging local mature distribution networks. The plan is to complete 50 service outlets in Indonesia by the end of the year, covering the full pre-sales and after-sales chain. In fact, localized production not only avoids import tariffs and shortens delivery cycles but also drives local employment and supporting industry chain upgrades, aligning with the policy orientation of ASEAN countries to cultivate their local new energy industries. As of now, Leapmotor's overseas business covers more than 40 countries and regions globally, with over 2,000 stores, and global cumulative deliveries have broken through 1.5 million units. Southeast Asian localized manufacturing will become a key fulcrum for its global expansion.
"Practice proves that Leapmotor is becoming a typical sample of new energy vehicle companies with the 'domestic scaling, global localization' dual-wheel drive." Independent auto analyst Bai De believes that on the one hand, the domestic market is responsible for 'revenue generation, training, building industry chains', and on the other hand, the international market is responsible for 'expansion, setting standards, sharing risks'. Only by making good use of the domestic and international market dual-wheel drive can Chinese new energy vehicles consolidate their global leading advantages and achieve high-quality development of the automotive industry.
Bai De emphasized that on the basis of achieving scaled growth, Chinese new energy vehicles must continue to invest in technological innovation. It is revealed that Leapmotor will hold a Technology Day in September 2026, upgrade the world model intelligent driving system, and achieve universal implementation of high-level intelligent driving with low computing power.
As more Chinese automakers adhere to technology-based enterprise development, delve into cutting-edge self-developed technologies, perfect product matrices, and promote localized industry layouts, China's new energy industry's global competitive advantage will continue to be consolidated, and the process of Chinese automotive industry upgrading and global green transportation transformation will also accelerate further.
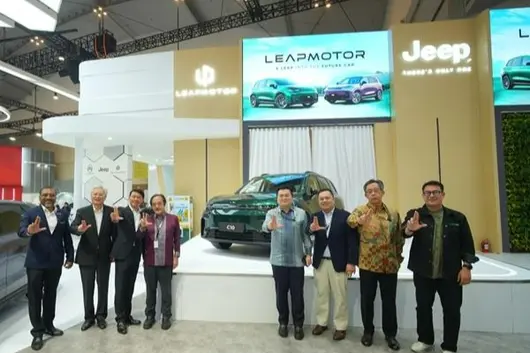
Paruh pertama 2026, jumlah keseluruhan eksport kenderaan China mencapai 5.31 juta unit, di mana eksport kenderaan tenaga baharu adalah 2.42 juta unit, meningkat 70% berbanding tahun lepas. Gambar ini memaparkan dua model global Leapmotor B10 dan C10 yang ditunjukkan di Pameran Kereta Antarabangsa Indonesia 2026.
Data statistik menunjukkan, pada paruh pertama 2026, jumlah keseluruhan eksport kenderaan China mencapai 5.31 juta unit, meningkat 53% berbanding tahun lepas; di mana, eksport kenderaan tenaga baharu adalah 2.42 juta unit, meningkat 70%, seterusnya mengukuhkan kedudukan China sebagai negara eksport kenderaan utama teratas di dunia.
Di satu pihak, risik geopolitik mendorong harga minyak global naik, meningkatkan daya saing kenderaan tenaga baharu China; di pihak lain, pengembangan berterusan pasaran negara-negara Selatan Global, membolehkan pengeluar kereta China bersaing mempercepatkan penempatan luar negara. Bagi Leapmotor yang bercadang menantang ambang jualan tahunan 1 juta unit, prestasi bulan Julai mengesahkan lagi keberkesan penggerak berganda domestik dan antarabangsa.
Menurut maklumat, pasaran domestik Leapmotor menghantar 101,267 unit pada Julai, berkadar dua kali ganda berbanding tahun lepas, menjadi pembuat kereta baharu pertama yang mencatat jualan bulanan melebihi 100,000 unit. Pada paruh pertama tahun ini, Leapmotor mencatat jualan terkumpul 356,487 unit, meningkat kira-kira 97%, merupakan jenama pembuat kereta baharu tunggal yang mencapai jualan melebihi 300,000 unit pada paruh pertama tahun ini. Model seperti A10, siri B, C10, D19 mekar di pelbagai titik, mengukuhkan asas pertumbuhan Leapmotor.
Baru-baru ini, Leapmotor membawa model global B10 dan C10, ditampilkan di Pameran Kereta Antarabangsa Indonesia 2026, dan secara rasmi mengisytiharkan memasuki pasaran Indonesia. Leapmotor bersama Kumpulan Indomobil Indonesia turut mengumumkan, secara rasmi memulakan pengeluaran assembly KD tempatan di Indonesia, melalui kerjasama mendalam dengan PT National Assemblers di bawah kumpulan Indomobil, mencapai lonjakan daripada eksport produk ke penempatan rantaian industri tempatan lengkap. Setakat ini, Leapmotor telah membentuk dua tapak pengeluaran di Malaysia dan Indonesia, menjadi salah satu jenama kenderaan tenaga baharu China yang mempunyai dua kapasiti KD di Asia Tenggara.
Ada analisis berpendapat, industri kenderaan tenaga baharu China saat ini telah membentuk struktur pembangunan 'skala domestik sebagai asas, ekspansi kuantiti global', kedua-duanya tidak boleh diabaikan. Contohnya, Leapmotor adalah yang pertama menembusi jualan bulanan 100,000 unit, menandakan pembuat kereta baharu rasmi memasuki tahap pengeluar kereta arus perdana, persaingan industri berpindah daripada pertandingan produk tunggal ke cabaran jangka panjang sistem komprehensif rantaian bekalan, pembuatan penyelidikan sendiri, perkhidmatan saluran.
Dalam beberapa tahun kebelakangan ini, eksport kenderaan tenaga baharu China telah meninggalkan jualan kenderaan penuh mudah, berpindah ke tahap baharu 'eksport teknologi + pembinaan kilang tempatan + perkongsian ekosistem'. Menurut maklumat, bergantung kepada koordinasi tiga hala dengan Stellantis dan Kumpulan Indomobil Indonesia, Leapmotor menggunakan model jualan dalam kedai yang sama, memanfaatkan rangkaian pengedaran tempatan yang matang, merancang membina 50 pusat perkhidmatan Indonesia pada akhir tahun, merangkumi keseluruhan rantaian pra-penjualan dan pasca-penjualan. Sebenarnya, pengeluaran tempatan tidak hanya mengelak cukai import, memendekkan kitaran penghantaran, tetapi juga memacu pekerjaan tempatan dan peningkatan industri sokongan, sesuai dengan garis panduan polisi negara-negara ASEAN memupuk industri kenderaan tenaga baharu tempatan. Setakat ini, bisnes luar negara Leapmotor meliputi lebih daripada 40 negara dan wilayah di dunia, lebih daripada 2,000 kedai, penghantaran terkumpul global telah mencapai melebihi 1.5 juta unit, pengeluaran tempatan di Asia Tenggara akan menjadi asas utama ekspansi globalnya.
"Amalan membuktikan, Leapmotor sedang menjadi sampel tipikal 'skala domestik, tempatan global' penggerak berganda syarikat kenderaan tenaga baharu China." Penganalisis kereta bebas Bai De berpendapat, di satu pihak, pasaran domestik bertanggungjawab 'menghasilkan dana, melatih pasukan, membina rantaian industri', di pihak lain, pasaran antarabangsa bertanggungjawab 'memperluas kapasiti, menetapkan piawaian, mengagih risiko'. Hanya dengan menggunakan penggerak berganda pasaran domestik dan antarabangsa dengan baik, barulah kenderaan tenaga baharu China dapat mengukuhkan keunggulan kepimpinan global, mencapai pembangunan berkualiti tinggi industri kenderaan.
Bai De menekankan, di atas asas pencapaian pertumbuhan berskala, kenderaan tenaga baharu China mesti terus menambah inovasi teknologi. Difahamkan, Leapmotor akan menganjurkan Hari Teknologi pada September tahun ini, memperbaharui sistem pemanduan pintar model dunia, untuk mewujudkan pemanduan pintar aras tinggi secara luas dengan keupayaan pengiraan rendah.
Seiring lebih banyak syarikat kenderaan China berpegang pada penubuhan berasaskan teknologi, menggiat dalam teknologi penyelidikan sendiri terdepan, memantapkan matriks produk, mendorong susun atur industri setempat, keunggulan persaingan global industri kenderaan tenaga baharu China akan terus diperkukuh, proses transformasi industri kenderaan China dan pengangkutan hijau global juga akan semakin dipercepatkan.
On August 1st, sales data for July for various new energy vehicle brands were released.
Leapmotor Cars revealed its July "achievements" first — 101,267 units, a year-on-year increase of 102%, equivalent to more than double the same period last year.
Leapmotor broke through the 100,000-unit delivery threshold for the first time, becoming the first vehicle manufacturer in the history of China's new car makers to achieve single-month deliveries exceeding 100,000 units.
The drama lies in: Xpeng 38,027 units, NIO 35,934 units, Li Auto 30,468 units — the former "Top 3 of NIO, Xpeng, and Li Auto" now only match Leapmotor when combined. Li Auto even saw double declines month-on-month and year-on-month for three consecutive months. Once the top dog among new forces, it is now far behind Leapmotor by more than three times.
Even Huawei's "Harmony Intelligence" alliance ("Five Realms"), which claimed to "lead far ahead," had July sales of 45,046 units.
Many car enthusiasts only realized at this point: When did Leapmotor become this amazing?

01. Others Make Money from Branding, Leapmotor Makes Money from "Factory" Costs
The core reason Leapmotor has reached today is four words: Full-Stack Self-Research.
Many people don't grasp these four words, thinking isn't it just about developing things yourself? But what Leapmotor does is far more extreme than most imagine.
As of now, Leapmotor's self-developed and manufactured parts account for 65% of the total vehicle BOM cost. What does that mean? From the core "three-electrics" (battery, electric drive, electric control) to smart cockpits, smart driving, and electronic architecture, extending to compressors, headlights, seats, bumpers, and on-board power supplies—things traditionally thought unnecessary to build in-house—as long as the value is high enough, Leapmotor does it all itself.

Zhu Jiangming calculated a figure: Based on the industry average gross margin of 15% for auto parts, just from self-research, Leapmotor's cost per vehicle is about 10% lower than competitors.
What does this 10% mean? It means with the same configuration, Leapmotor can be 10,000 to 20,000 cheaper than others and still make money; while selling at this price causes others to lose money, Leapmotor can still maintain a healthy gross margin.
This is not a marketing gimmick; it is a manufacturing gene carved into Zhu Jiangming's bones. Many may have forgotten that before making cars, Zhu Jiangming was one of the founders of Dahua Technology, engaged in security manufacturing for decades. What was the environment of the security industry? Price wars down to the bone, squeezing costs penny by penny. Others see suppliers that need management; Zhu Jiangming sees how much profit from middlemen can be squeezed out.
A classic example is headlights. When Leapmotor made its first car, supplier quotes were several thousand yuan per set. Zhu Jiangming led the team to calculate it themselves, using Dahua's embedded technology accumulation to self-develop, ultimately cutting the cost in half.
So you find Leapmotor's cars strange: Why is the configuration higher and the price lower than others? It's not Leapmotor losing money to shout for sales; it's because it gives all the profit from the middle of the supply chain to consumers. In Zhu Jiangming's own words: "We just make money from being a contract factory, everything else goes to the users."

02. Does Leapmotor Have Its Own Core Technologies?
Many people have a misconception about Leapmotor, thinking it relies solely on cheapness and lacks technology.
This is actually the biggest misunderstanding.
Low price is just the result; behind it is a whole self-developed technology system supporting it.
The most core is the "Cloverleaf" Central Integrated Electronic Electrical Architecture. This is complex if complicated, simple if simple: Traditional cars use a distributed architecture where dozens of ECUs manage their own tasks; Leapmotor uses one SOC chip plus one MCU to integrate the functions of the Cockpit, Smart Driving, Powertrain, and Chassis four domains together.
What is ruthless is that this architecture isn't just for flagship models; even the 100,000-level A10 has it as standard, which was unthinkable in the past.
With centralized architecture, the whole vehicle's response speed, OTA capability, and failure rate will be much better, and costs will drop instead.
Next is CTC 2.0 Plus Battery-Chassis Integration Technology. Leapmotor is one of the earliest Chinese vehicle manufacturers to mass-produce CTC; now cumulative installations exceed 500,000 units. Simply put, the battery is integrated directly with the chassis, removing the traditional battery pack cover, saving space and reducing weight while increasing body rigidity. Regarding safety, Leapmotor's battery achieves thermal runaway prevention for 48 hours without fire or explosion, which is 24 times the new national standard.

Regarding the three-electrics, Leapmotor's intelligent oil-cooled electric drive is fully self-developed and manufactured. The 8-in-1 integration degree is higher than the industry mainstream 3-in-1 or 6-in-1, with better efficiency and reliability. The 800V High-Voltage SiC platform is not exclusive to high-end cars; from the 200,000-level C series to the 100,000-level B series, everything needed is included. Coupled with 4C supercharging, the energy replenishment speed fully matches the first tier.
Smart driving was previously Leapmotor's weak point, but now it has caught up. The combination of LiDAR + Qualcomm 8650 smart driving chips can already achieve full-scenario navigation from parking spot to parking spot, and it is standard with permanent free use. In September's Technology Day, Leapmotor will also launch the next-generation smart driving based on world models, directly benchmarking the industry's first tier.
To put it plainly, Leapmotor isn't without technology; it puts all technology where users can touch it, rather than spending on marketing and brand premium.
03. Covering Everything from 60,000 to 300,000, This Is the Greatest Open Strategy
Leapmotor's second smart move is that it never had the "baggage of a new force" mindset.
When other new forces started, almost all focused on the high-end market above 300,000 yuan, talking about brand, tone, and user circles, as if they weren't qualified as new forces if they didn't sell a bit more expensive. Result? As soon as the market fluctuates and high-end consumption power drops, sales immediately come under pressure. Li Auto's current predicament is largely because its products are all stuck above 300,000 yuan, unable to go up or down.
Leapmotor is different; it never thought about doing only high-end from the start. Now Leapmotor's product matrix, A, B, C, D four series, covers from the 60,000 yuan entry-level car all the way to the flagship MPV above 300,000 yuan, covering all mainstream price bands without missing a single one.

The sales structure of the just-ended July explains the problem well:
1. A-series A10, monthly sales near 30,000 units; this is Leapmotor's basic base, firmly grasping the widest range of entry-level users;
2. B-series broke 20,000 units in July, with global cumulative sales already reaching 250,000 units;
3. C-series C10 global monthly sales steadily break 10,000, C-series cumulative sales reached 850,000 units;
4. High-end D19 monthly sales broke 10,000, newly launched MPV D99, the average price of the first batch of orders went directly to over 300,000 yuan.
Low-end cars drive volume to dilute costs, mid-range cars contribute profits, high-end cars build brand image, forming a complete pyramid across the entire price band.
Unlike other new forces that walk on one leg and wobble when the market changes, this is the most terrifying part of Leapmotor.
Many people look down on low-end cars, thinking 60,000 or 80,000 yuan cars don't make money.
But the fact is, it is precisely these volume-driving entry models that supported Leapmotor's supply chain scale.
The larger the scale, the lower the cost of self-developed parts; the lower the cost, the more competitive the product, then selling more — this is a positive cycle.
Now this cycle is already turning.

04. Leapmotor's Overseas Business Is More Intense Than Anyone Thinks
Many only see Leapmotor selling well domestically, failing to notice its overseas business has quietly become the number one among new forces.
Leapmotor's internationalization follows the "borrowing a boat to go overseas" route in cooperation with Stellantis. No need to build channels from scratch; directly use Stellantis' dealer network globally. Now Leapmotor has entered 35 countries and regions worldwide, with over 800 overseas sales service outlets.
In 2025, Leapmotor exported 60,000 units for the full year, the most among new forces. This year the speed is even faster; in July, it just started delivery in Mexico and announced local KD assembly production in Indonesia.

In Europe, Leapmotor B10 sells starting from €29,900, which converts to over 230,000 RMB, more than double the domestic price, yet it still sells well — in the Italian market, 1 out of every 3 pure electric cars is a Leapmotor B10.
Zhu Jiangming's goal is even more exaggerated; he says Leapmotor's future overseas sales share must account for 60% of total sales. What does that mean?
If Leapmotor really achieves annual sales of 1 million units next year, that is 600,000 units for export; this number is something even many traditional car manufacturers cannot achieve now.
In contrast, other new forces' overseas efforts, NIO and Xpeng, are still in a small-scale trial phase; Li Auto basically hasn't gone overseas at all. When the domestic market is fighting fiercely, Leapmotor has already opened a second battlefield overseas, using domestic cost advantages to fight the overseas market; this is another dimensional strike.

05. Does Leapmotor Have Weaknesses?
Monthly sales of 100,000 is naturally not the endpoint; Leapmotor itself knows very well where the weaknesses lie.
Previously many complained Leapmotor's smart driving was average, after all, money was spent on hardware and three-electrics, so software algorithm investment came relatively later.
But Zhu Jiangming has already announced that this September on Leapmotor Technology Day, Leapmotor will release a smart driving system based on world models and will catch up on smart driving.
In addition, the all-new model A05 will be released in August, making the product matrix denser.

From monthly sales of a few hundred units 6 years ago to 100,000 units today, the path Leapmotor took is actually not fresh at all — it's just the traditional manufacturing model: keep technology in your own hands, bring costs down, spread products fully, and take the market to the whole world.
It's just that in the industry where everyone wants to tell new stories and overtake on a bend, there are too few willing to put in this kind of hard work.
While other new forces were still struggling hard for monthly sales of 30,000 or 40,000 units, Leapmotor has quietly set its goal at annual sales of 1 million, even 4 million in the future.
Now looking back, it's not that Leapmotor suddenly became popular; it's just the harvest season.
Now looking back, it's not that Leapmotor suddenly became popular; it's just the harvest season.
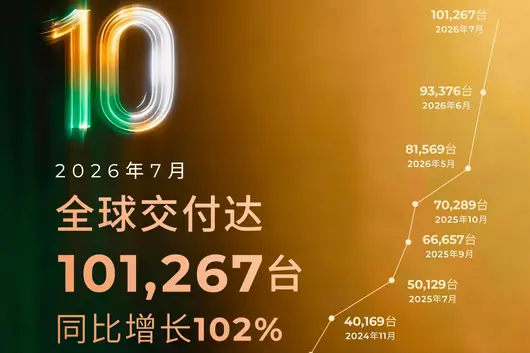
1 Ogos, data jualan Julai bagi pelbagai jenama kereta baharu elektrik secara beransur-ansur dibuka.
Kereta Leapmotor segera memaparkan 'pencapaian' Julai — 101,267 unit, meningkat 102% berbanding tahun sebelumnya, setara dengan lebih daripada dua kali ganda pada tempoh yang sama tahun lalu.
Leapmotor berjaya melepasi ambang penghantaran 100,000 unit buat kali pertama, menjadi syarikat kereta domestik pertama kali melampaui 100,000 unit jualan bulanan dalam sejarah industri pembuat kereta baharu.
Yang menariknya, Xpeng 38,027 unit, NIO 35,934 unit, Li Auto 30,468 unit — tiga pemain utama terdahulu 'NIO, Xpeng, Li Auto', kini jumlah jualan mereka baru setara dengan Leapmotor. Li Auto pula mencatat penurunan serentak bulan demi bulan selama tiga bulan berturut-turut, pemimpin terdahulu dalam kalangan pembuat kereta baharu, kini ketinggalan tiga kali ganda berbanding Leapmotor.
Malah, ia telah 'Terus Memimpin' (Slogan), Jualan 'Lima Domain' HarmonyOS Intelligence pada Julai ialah 45,046 unit.
Ramai rakan kereta pada ketika ini baru sedar, bila Leapmotor menjadi sebegitu hebat?
01, Orang lain untung duit jenama, Leapmotor untung duit 'kilang'
Kerana Leapmotor berjaya sampai ke hari ini, kad teras utamanya ialah empat perkataan: R&D Merentas Segala Kawasan.
Ramai orang tiada konsep terhadap empat perkataan ini, berfikir bukankah ia hanya membangunkan sesetengah barang sendiri? Tetapi apa yang dilakukan Leapmotor, jauh lebih melampau daripada yang dibayangkan kebanyakan orang.
Seterusnya, sehingga kini, bahagian-bahagian yang direka dan dihasilkan sendiri oleh Leapmotor, telah mencecah 65% daripada kos BOM keseluruhan kenderaan. Apa maksudnya? Dari teras 'Tiga Elektrik' seperti bateri, pemacu elektrik, kawalan elektrik, ke kabin pintar, pemanduan pintar, arkitektur elektronik dan elektrik, lalu meluas ke kompresor, lampu kereta, kerusi, penampan, kuasa berkenderaan yang tradisionalnya dianggap tidak perlu dibuat sendiri. Sedikit pun nilai tinggi, Leapmotor melakukannya sendiri.
Zhu Jiangming telah mengira satu pengiraan: Berdasarkan margin kasar purata industri komponen kereta 15%, Hanya bagi item R&D sendiri ini, kos per kenderaan Leapmotor lebih rendah kira-kira 10% berbanding pesaing.
Apakah konsep 10% ini? Iaitu kereta dengan konfigurasi yang sama, Leapmotor boleh lebih murah 10,000 hingga 20,000 berbanding orang lain, tetapi masih untung; Orang lain menjual pada harga ini akan rugi, tetapi Leapmotor menjual pada harga ini masih boleh mengekalkan margin kasar yang sihat.
Ini bukan gaya pemasaran, ini adalah gen pengilangan yang terpahat dalam tulang belakang Zhu Jiangming. Ramai orang mungkin terlupa, sebelum Zhu Jiangming membuat kereta, dia adalah salah satu pengasas Dahua Technology, Berkecimpung dalam pengilangan keselamatan selama beberapa dekad. Bagaimana persekitaran industri keselamatan? Merosakkan harga sehingga ke tulang, mengorek kos satu sen demi satu sen. Orang lain melihat pembekal yang perlu diurus, Zhu Jiangming melihat berapa banyak keuntungan penaja boleh dipadamkan di tengah-tengah.
Contoh paling klasik ialah lampu kereta. Pada masa dahulu apabila Leapmotor membuat kereta pertama, mencari pembekal untuk sebut harga, satu set lampu kereta beratus yuan. Zhu Jiangming menarik pasukan mengira sendiri, menggunakan pengumpulan teknologi terpencil dari Dahua untuk membangunkan sendiri, akhirnya kos ditekan setengan daripada asal.
Jadi apabila anda melihat kereta Leapmotor, anda akan rasa pelik: kenapa konfigurasi lebih tinggi daripada orang lain, harga pula lebih rendah? Bukan Leapmotor rugi untuk menarik perhatian, tetapi ia menyerahkan semua keuntungan di tengah rantai pasokan kepada pengguna. Mengikut kata-kata Zhu Jiangming sendiri: 'Kami hanya untung duit kilang kontrak, yang lain untuk pengguna.'
02, Adakah Leapmotor mempunyai teknologi teras sendiri?
Ramai orang mempunyai salah faham tentang Leapmotor, berfikir ia bergantung pada harga murah, teknologi tidak cukup.
Ini sebenarnya kesilapan terbesar.
Harga murah hanyalah hasil, di belakangnya adalah satu sistem teknologi R&D sendiri yang menyokong.
Yang paling teras ialah arkitektur elektronik dan elektrik terintegrasi 'Sikat Empat Daun'. Mudah-mudahnya, ini rumit, kata mudah juga mudah: Kereta tradisional adalah arkitektur bersebaran, puluhan ECU mengurus masing-masing, Leapmotor menggunakan satu cip SOC ditambah satu cip MCU, mengintegrasikan sepenuhnya fungsi empat domain: kabin, pemanduan pintar, kuasa, dan badan.
Yang paling hebat ialah, arkitektur ini bukan hanya untuk kenderaan flagship, malah A10 kelas 100,000 pun dilengkapi sebagai piawai, ini sebelum ini tidak pernah terbayang.
Apabila arkitektur terpusat, kelajuan respons keseluruhan kenderaan, kemampuan OTA, kadar kerosakan akan jauh lebih baik, kos sebaliknya menurun.
Seterusnya ialah teknologi integrasi bateri dan sasis CTC2.0Plus. Leapmotor adalah antara syarikat kereta domestik pertama yang memasyukan CTC, kini jumlah pemasangan terkumpul lebih daripada 500,000 unit. Secara mudahnya, bateri digabungkan terus dengan sasis, penutup atas bekas bateri tradisional dikeluarkan, Jimat ruang dan berat, kekerasan badan kenderaan malah lebih tinggi. Dari segi keselamatan, bateri Leapmotor telah mencapai tidak terbakar atau meletup selama 48 jam semasa kegagalan termal, 24 kali ganda piawaian negara baharu.
Dari segi 'Tiga Elektrik', Pemacu elektrik penyejukan minyak pintar Leapmotor adalah direka dan dihasilkan sepenuhnya sendiri, Kebebasan integriti 8 dalam 1 adalah lebih tinggi daripada 3 dalam 1, 6 dalam 1 arus perdana industri, kecekapan dan kebolehpercayaan lebih baik. Platform SiC tekanan tinggi 800V juga bukan eksklusif untuk kereta高端, dari siri C 200,000 ke siri B 100,000, semuanya diberikan,配合 pengecasan pantas 4C, kelajuan pengecasan selari dengan barisan pertama.
Pemanduan pintar sebelum ini adalah kelemahan Leapmotor, tetapi kini telah mengejar. Gabungan LiDAR + cip pemanduan pintar Qualcomm 8650, telah mampu navigasi senario penuh dari tempat parkir ke tempat parkir, dan ia adalah piawai percuma selamanya. Pada hari teknologi September, Leapmotor juga akan mempopularkan pemanduan pintar generasi baharu berasaskan model dunia, terus menyaingi barisan pertama industri.
Secara mudahnya, Leapmotor bukan tidak ada teknologi, ia menggunakan teknologi di tempat yang boleh disentuh pengguna, bukan dibelanjakan untuk pemasaran dan premium jenama.
03, Menyerap dari 60,000 hingga 300,000, Inilah 'Strategi Terbuka' Terbesar
Tempat bijak kedua Leapmotor, ialah ia tidak pernah mempunyai 'beban ikon pembuat kereta baharu'.
Apabila pembuat kereta baharu lain bermula, hampir semua menatap pasaran高端 di atas 300,000, bercakap jenama, nada, lapisan pengguna, seolah-olah tidak menjual mahal sedikit tidak layak dipanggil pembuat kereta baharu. Hasilnya? Pasar berfluktuasi, kuasa pengguna高端 menurun, jualan terus tertekan. Kesusahan Li Auto sekarang, besarannya kerana produk terikat pada atas 300,000, naik tidak boleh, turun tidak boleh.
Leapmotor berbeza, ia tidak pernah berfikir mahu hanya buat高端 dari awal. Kini matriks produk Leapmotor, Siri A, B, C, D, dari kereta入门 60,000, sehingga MPV flagship atas 300,000, semua jalur harga utama tidak ketinggalan satu pun.
Struktur jualan Julai baru lalu, sangat menerangkan masalah:
① Siri A A10, jualan bulanan hampir 30,000 unit, ini adalah asas Leapmotor, mengikat pengguna入门 terluas dengan kuat;
② Siri B Julai pecah 20,000 unit, kumulatif global sudah 250,000 unit;
③ Siri C C10 jualan bulanan global stabil pecah 10,000, Siri C terkumpul dijual 850,000 unit;
④高端 D19 jualan bulanan pecah 10,000, MPV D99 yang baru keluar, purata pesanan pertama terus capai atas 300,000.
Kereta低端 laris mengurangkan kos, keretapertengahan sumbangan untung, kereta高端 tegakkan jenama, keseluruhan jalur harga membentuk piramid lengkap,
Tidak seperti pembuat kereta baharu lain, berjalan dengan satu kaki, pasar berubah bergoyang, inilah tempat paling menakutkan Leapmotor.
Ramai orang merendahkan kereta低端, berfikir kereta 60,000, 80,000 tidak untung.
Tetapi fakta ialah, model入门 yang laris inilah yang撑kan skala rantai pasokan Leapmotor.
Semakin besar skala, kos komponen R&D sendiri semakin rendah, kos semakin rendah, produk semakin kompetitif, kemudian dijual lebih banyak — ini adalah kitaran positif.
Kini kitaran ini telah berputar.
04, Luar negara Leapmotor, lebih ganas daripada yang difikirkan semua orang
Ramai orang hanya melihat Leapmotor jualan dalam negeri bagus, tidak perasan perniagaan luarnya telah diam-diam lari jadi nombor satu pembuat kereta baharu.
Internasionalisasi Leapmotor berjalan laluan 'meminjam kapal keluar laut' kerjasama dengan Stellantis, tidak perlu bangun laluan dari sifar sendiri, terus gunakan rangkaian peniaga Stellantis di seluruh dunia. Kini Leapmotor telah masuk ke 35 negara dan wilayah全球, rangkaian perkhidmatan jualan luar negara lebih dari 800.
2025 Leapmotor eksport 60,000 unit sepanjang tahun, yang paling banyak eksport dalam kalangan pembuat kereta baharu. Tahun ini kelajuan lebih pantas, Julai baru mula hantar di Mexico, di Indonesia umumkan produksi rakitan KD tempatan.
Di Eropah, Leapmotor B10 dijual bermula 29,900 Euro, ditukar ke Renminbi 230,000 lebih, lebih mahal daripada dalam negara satu kali ganda lebih, tetap dijual tidak begitu buruk — pasaran Itali, setiap 3 kereta elektrik penuh ada 1 unit adalah Leapmotor B10.
Sasaran Zhu Jiangming lebih aneh, dia kata masa depan jualan luar negeri Leapmotor mesti mencecah 60% daripada jumlah jualan. Apakah konsep ini?
Jika Leapmotor tahun depan betul-betul boleh capai jualan tahunan 1,000,000 unit, itu ialah 600,000 unit eksport, nombor ini sekarang walaupun ramai syarikat kereta tradisional tidak mampu capai.
Membanding pembuat kereta baharu lain, NIO, Xpeng luar negara masih dalam peringkat cuba air kecil, Li Auto malah hampir tidak keluar laut. Apabila pasaran dalam negara bergelut hingga pisau tajam nampak merah, Leapmotor telah membuka medan perang kedua di luar negara, guna kelebihan kos dalam negara menyerang pasaran luar negara, ini satu lagi serangan dimensi turun.
05, Adakah Leapmotor ada kelemahan?
Jualan bulanan 100,000 sudah tentu bukan hujung, Leapmotor sendiri sangat jelas di mana letak kelemahannya.
Sebelum ini ramai orang mengkritik pemanduan pintar Leapmotor, kerana wang dibelanjakan pada perkakasan dan Tiga Elektrik, pelaburan algoritma perisian agak lewat.
Tetapi Zhu Jiangming sudah bersuara, pada hari teknologi September tahun ini, Leapmotor akan mempopularkan sistem pemanduan pintar berasaskan model dunia, ingin mengejar pada pemanduan pintar.
Selain itu, pada Ogos ada model baharu A05 perlu dipopularkan, matriks produk akan lebih padat.
Dari 6 tahun lalu jualan bulanan beberapa ratus unit, hingga hari ini jualan bulanan 100,000 unit, jalan yang dilalui Leapmotor sebenarnya sama sekali tidak baru — Iaitu cara pengilangan tradisional: pegang teknologi di tangan sendiri, tekan kos ke bawah, sebar produk hingga lengkap, buat pasaran hingga seluruh dunia.
Hanya dalam industri pembuat kereta baharu yang semua orang mahu cerita baru, semua orang mahu tikung tikungan, orang yang rela buat kerja bodoh begini, terlalu sedikit.
Apabila pembuat kereta baharu lain masih bergelut dengan jualan bulanan 30,000, 40,000, Leapmotor telah diam-diam tetapkan sasaran jualan tahunan 1,000,000, malah masa depan 4,000,000 unit.
Kini lihat ke belakang, apa masalahnya Leapmotor tiba-tiba popular, hanya musim menuai sahaja.
© 2024 Bitauto.com. All Rights Reserved.
Bitauto (www.yiche.com and www.bitauto.com) is one of the most visited automotive websites in China. We provide detailed info on Chinese car brands available in your area. Please note that the information provided on this website is based on publicly available data and is for reference only. It may not be fully updated or accurate at all times.

Help us improve our website


